Dinarian888
News • Business • Investing & Finance
💥5 Things That Break With Rising Rates💥
The Fed being aggressive AF - what could break with interest rates skyrocketing?
October 03, 2022
post photo preview

Dear Bankless Nation,

When COVID-19 hit, the Fed courageously dove into the thick of the US Treasury market and committed to buying over $1 trillion in Treasury bonds.

The plan was simple: keep rates low, print money, and stimulate the economy.

A global pandemic and a recession mashed together into one mutant blackswan event would have just been too much for the markets to bear.

Thankfully, the stimulus went as planned.

  • Treasury interest rates hit record lows at near zero

  • Global markets quickly rallied as fears of recession evaporated overnight

  • Crypto markets mooned

  • The Payroll Protection Program (PPP) reduced a spiking unemployment rate

  • We developed cures and vaccines to Covid

We did it!!!

Right?

Well… not exactly.

Expansionary monetary policy allowed inflation to hit a 40-year-high of 8%. In response, the Fed is now scrambling to combat inflation by aggressively reversing course and raising interest rates.

But, policy doesn’t always work as intended, and things may break.

Here are the 5 things that could break if the Fed continues on its course:

  1. Inflation (in a kinda positive way)

  2. Housing Markets

  3. Financial Institution Solvency

  4. Sovereign Debt and Forex Markets

  5. Private Credit Markets

1. Inflation

Why is the Fed raising interest rates in the first place?

To fight inflation.

The Fed’s unlimited bid on the US Treasury market during COVID-19 – and to a lesser extent, US Mortgage Backed Securities (MBS) markets – increased the size of its balance sheet from $4.24 trillion to $8.96 trillion.

That is an increase of$4.72 trillion, or111%.

Where did all of that money come from?

Essentially, from thin air.

The Fed repurchased Treasuries and MBS throughOpen Market Operations, which is a fancy monetary policy term for buying and selling Treasuries and MBS.

When conducting such an operation, the Fed credits or debits a bank’s reserve accounts at the Federal Reserve. There is no need for the Treasury Department to create or destroy any money. A simple ledger adjustment at the Fed can simply create trillions of brand new dollars.

Stimulating the economy to drag ourselves from the depths of Covid requiredQuantitative Easing(QE), meaning the Fed purchased Treasuries and MBS – hence the balance sheet expansion.

And wouldn’t you know it, creating new dollars caused inflation!

Can you recall how else we created new dollars during Covid?

That’s right! Those sweet, sweet stimmies and those fatty PPP loans, which evolved into PPP grants and never had to be repaid.

Central banks claimed that inflation was only transitory. But in December 2021, people finally came to terms with the fact that the mighty United States of America is not immune to basic economic principlesafter the CPI reported its biggest annual increase in 40 years.

The Fed, however, continued to expand its balance sheet until the middle of April, at which point they became net sellers of Treasuries and MBS.

Further, the Fed failed to raise interest rates until the middle of March, despite knowing inflation would be stickier than expected afull three and a half months prior!

Raising interest rates increases the opportunity cost of money.

As cost increases, investors are less willing to pay high prices.

Increasing opportunity cost delays consumption.

As we can see in the chart below, the month-to-month change in inflation has been decreasing as of late, therefore, rate increases = successful!

We broke inflation! Probably… Maybe?

So I guess this is a positive break. However, raising rates to reduce inflation comes at the risk ofdeflationand while inflation is not desirable, deflation is even less so, as it may create the spiral of a weakening economy.

Put elegantly by Elon:

2. Housing Markets

US home prices have been on an absolute tear since the end of the pandemic.

Over the past two years, the median home sales price has risen by 36.5%, fueled by historically low interest rates on mortgages.

In January 2021, you could take out a 30-year mortgage at 2.65%.

Today, it’s 6.70%. 😱

To examine the impact of mortgage rates on the purchasing power of consumers, let's take a hypothetical buyer, looking to put 20% down on a 30-year, fully amortizing mortgage, with a budget of $1M.

The low rate scenario uses our record low interest rate mark of 2.65%, while the high interest rate of 6.70% is the current rate offered on 30-year fixed mortgages.

The monthly payment for this hypothetical buyer in today’s high rate interest environment is $1,939 (or over 60%) greater than had they purchased the home in January, 2021.

It’s 60% more expensive to buy a home today than less than 2 years ago!

Unless you can increase your annual income by 60%, if interest rates continue to rise, buyers will be able to afford less, and home values will have to decrease (which they already have).

Initially, decreasing home prices will only impact those who purchased homes and took out high interest loans in 2022 on overvalued real estate, however,a potential housing bubble could cause cascading foreclosures, much the same as a falling token price can cause cascading liquidations.

3. Pension Funds

When rates rise, discount rates increase and the market value of existing assets decline.

Thanks to their known cash flows, fixed income instruments (bonds) are extremely easy to price, given the bond’s yield and future cash flow timing. Many large financial institutions also love fixed income securities, as it provides a known cash flow, enabling them to match assets with obligations.

For a pension, bonds provide known cash flows to match with fairly certain liabilities payments to retirees. While pensions generate income and returns through a variety of investments of varying risk profiles, a primary income generation tool is sovereign bonds, especially those originating from the country in which the pension operates.

British pensions funds have been absolutely shellacked by rising interest rates, aftertax cut plans announced by UK’s new Prime Minister Liz Truss gave rise to investor fearover Britain’s ability to service national debt.

From peak to trough, the tax cut announcement wiped out 10% of the value of British 10-Year Gilt (the UK equivalent of US Treasuries). This rapid drawdown in the market value of assets placed enormous strain on UK pensions’ solvency, and required the BOE to step into the fray, supporting the Gilt via QE (printing money).

If the Fed continues to raise rates, markets will demand higher yields on foreign paper, placing the solvency of holders (i.e. pensions) at risk!

4. Sovereign Debt and Forex Markets

In point #3, we discussed how the BOE was forced to commence QE to defend yields on the Gilt and prevent pension fund insolvency.

How did they do this?

By turning on the money printer, much like the Fed did to support US Treasury yields in the depths of Covid!

But doesn't QE and money printing just increase inflation?

And isn’t inflation what we started raising rates to fight against?

Yes. But hey… the boomers can’t lose their retirement accounts.

It is fairly clear to see the inflationary shocks in the British Pound from the chart below:

While extremely rapid QE measures stabilized Gilts, the result was the value of the Pound temporarily falling off a cliff against the dollar.

Protection of British interest rates came at the cost of a devalued Pound!

Britain is not the only major economy affected by Fed rate increases.

The Bank of Japan (BOJ) has conformed to a policy of yield curve control for decades, the first major central bank to do so since 2016.

Rising rates in the US make Treasuries and Dollars attractive investments, causing upwards pressure on Japanese yields. To combat this pressure, the BOJ has resorted to… you guessed it… QE!

But the BOJ has reached the limits of QE.

The BOJ has imposed exchange rate limits of less than 145 Yen to 1 USD and a targeted yield of 25 bps on their 10-Year bonds.

Currently the Yen to Dollar exchange rate is 144.68 to 1, with 10-Year bonds yielding 24 bps!

The BOJ may soon have to choose between further devaluing the Yen or losing control of the yield curve. Such a change in monetary policy may be seen by markets as a sign of looming disaster, further hammering the Yen and rocketing Japanese yields.

5. Private Credit Markets

If the US Government is forced to pay more in interest when yields increase, I can assure you that private corporations experience the same effects.

Corporate bonds help to finance a wide range of publicly traded and private companies. MicroStrategy has used its debt issuances to finance purchases of Bitcoin while Boeing uses bonds to finance the development of new manufacturing plants in South Carolina. Real estate developers, such as Greystar, may opt to finance developments of apartments using bank loans, instead of issuing bonds.

You get the idea.

Regardless of how the company structures financing, there will be some form of interest rate attached to the note.

These notes are often interest only, or mature before being fully paid down.

New debt must be taken on to repay maturing notes.

Rising interest rates make new debt more expensive for borrowers. Low interest rates allowed for borrowers to finance projects that would be considered unfeasible in today’s high interest rate environment. When it comes time to rollover outstanding debts on unfeasible projects, corporations will resort to selling, as their cash flows from the purchase asset may no longer cover interest obligations.

High quality, two year corporate bonds yielded0.47% in August, 2020.

In August 2022, they yield3.81%, an increase of 711%.🚀

Payments on interest-only notes rolled over last month increased by seven times! While proformas often provide some amount of slack for changes in interest rates, an payment increase of that magnitude may force asset sales.

A Difficult Decision

Multiple pressure points exist in the global financial system, and with each Fed rate hike pushing us closer to the edge of the recession cliff, it may only be a matter of time until we see a true crisis, potentially caused by one of the five factors listed above.

The Fed faces a difficult decision: continue to raise interest rates, potentially destabilizing US allies attempting to stimulate and maintain low interest rates, or devalue the Dollar and exacerbate inflationary pressures in the US.

Jerome Powell and the FOMC are walking the knife’s edge.

A singular misstep and…

Link
community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
Collateral is the missing piece for XRP's future adoption.🎯

This topic has become central to the discussion around the important features coming to the XRPL.🗣️

XLS-65 and XLS-66 bring native lending to the XRPL and turn the ledger into a lending machine for banks and institutions alike.✅

The walkthrough below gives the first full breakdown of the significance of this upgrade, the Evernorth XRP effort, and the implications of XRP becoming a global collateral asset.🌐💰

OP:Smqkedqg

00:10:00
November 17th

From October 5, 2017, to November 17, 2026 is 3330 days (the exact difference between the two dates; Nov 17, 2026 is 3330 days after Oct 5, 2017).

00:02:21
🎬 The investment opportunity in Bittensor 🎬

@Briandixon06, CEO of Off The Chain Capital, and @GrantCardone discuss the investment opportunity in Bittensor.

$TAO 🌐 WYKYK 😉

00:02:06
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading
🎯

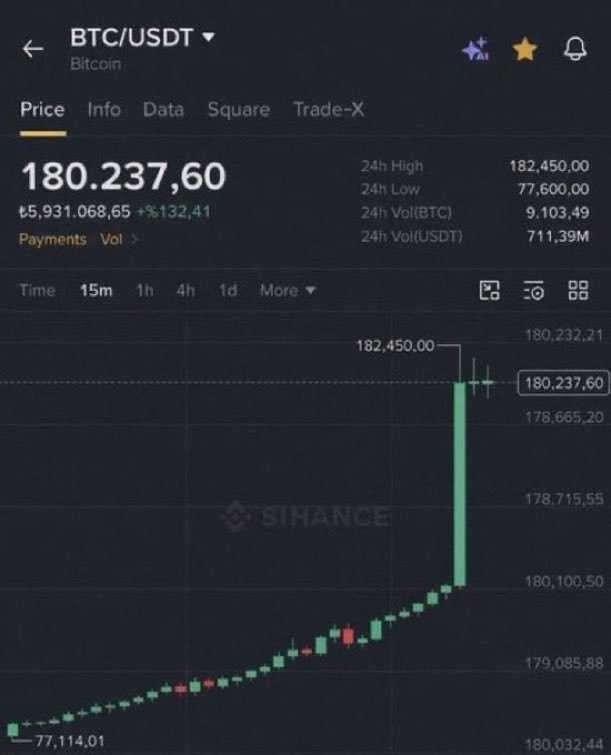
🔴 ALL ALTCOIN HOLDERS, LISTEN CAREFULLY TO WHAT I'M SAYING!

Because from this point on, I'm not just sharing a prediction…

I'M PUTTING MY OWN REPUTATION AND ALL 9 YEARS OF MY WORK ON THE LINE!

I called SOL at $5, AVAX at $2, XRP at $0.50, and MATIC at $0.003.

Three years ago, I turned my $8,000 balance into more than $2.5 million.

The next three months will be decisive for both me and the market.

🔴 NOVEMBER — DECEMBER — JANUARY

Bitcoin → $180,000

Ethereum → $10,000

In altcoins → 60X TO START.

We'll see 100X, 150X, 200X+ in some coins.

THIS WILL BE OVER BY JANUARY…

https://x.com/Core_002/status/2121774442175152404

post photo preview
🏦 Is the Fed Planning an Interest Rate Reset? 📉

George Gammon breaks down the Fed's surprising signals hinting at a potential 50 basis point rate hike, the massive moves in Treasury yields, and what's really driving central bank policy

🔑 Key Takeaways:

🔹️ The Rate Hike Signal: Fed officials like Christopher Waller have floated the possibility of a 50 bps hike if core CPI inflation readings stay sticky.

🔹️ The Energy Shock Driver: Recent inflation spikes are heavily tied to global energy disruptions and oil price shocks—factors that higher interest rates cannot directly fix.

🔹️ Central Bank Incentives: A deep dive into why monetary policy decisions are often driven more by institutional self-preservation and avoiding public blame than by underlying economic reality.

🔹️ Market Impact: How aggressive rate signals create massive volatility across Treasury yields, the US dollar, gold, and equities.

#GeorgeGammon #FederalReserve #InterestRates #Inflation ...

🌐 Three central banks test synchronized FX settlement

The Bank of England, Monetary Authority of Singapore, and Bank of Thailand published findings from Project Meridian FX APAC, a trial of coordinating cross-border currency settlements across systems using different technologies.

🔑 Key points

🔹 Two settlement models tested: Payment-versus-payment (PvP) completes a currency transfer only if the matching transfer also completes. Multilateral net settlement offsets payments between participants.

🔹 Different systems were connected: The test spanned conventional real-time gross settlement systems and distributed-ledger platforms.

🔹 Partior built the prototype: Its Synchronisation Operator coordinated linked transfers across separate systems.

🔹 The aim is to reduce settlement risk: The design seeks to prevent one side of an FX transaction from completing while the other does not.

🔹 Legal and oversight issues were considered: The Reserve Bank of Australia and Bangko Sentral...

post photo preview
post photo preview
🎯What’s In Your Vault? — 2026 Edition🎯

Sixteen years ago, I posed a question that appeared to be about money but was never really about money at all. What's In Your Wallet? was written at a moment when the world remained intoxicated by the illusion that a representation of value and value itself were interchangeable. The distinction seemed trivial because the machinery of modern finance operated smoothly enough to conceal it. A bank balance purchased goods. A brokerage statement could be exchanged for assets. A warehouse receipt represented commodities. A title represented property. A promise represented delivery. The system functioned, and because it functioned, few bothered to examine the assumptions upon which it rested.

Yet beneath the smooth functioning of the machine lurked a subtle substitution. Somewhere along the way we ceased valuing the thing and began valuing the description of the thing. We stopped demanding possession and settled for evidence of possession. We became comfortable owning records instead of realities, claims instead of assets, promises instead of substance. The map became more important than the territory because most people never wandered far enough from the roads to discover that the two were not the same.

Reading those observations in 2026 feels less like revisiting an old essay and more like observing a fault line that has slowly widened beneath the surface of the global financial order. What has changed is not the distinction itself. What has changed is that the institutions most responsible for maintaining the abstraction appear increasingly unwilling to trust it.

Around the world, central banks have begun bringing gold home. Not merely purchasing gold, though that is certainly occurring, but repatriating it. Bullion that once rested comfortably in the vaults of London and New York is being moved into domestic custody. Public explanations invoke geopolitical uncertainty, sanctions exposure, strategic resilience, and sovereign security. None of those explanations are incorrect. They are simply incomplete. They describe the circumstances without illuminating the realization that appears to be driving the behavior.

A gold bar in your vault is not the same thing as a claim upon a gold bar in someone else's vault. Since the Templars in Jerusalem communicating with the courts of Europe, promises are not the thing that's promised. They never were.

For decades that distinction could be ignored because confidence in the system remained sufficiently high that possession appeared unnecessary. The custodians were trusted. The networks functioned. The legal frameworks appeared durable. The infrastructure seemed permanent. Under those conditions, claims and assets could masquerade as equivalents because the distance between them was rarely tested. Yet every system eventually encounters moments when assumptions become visible. The freezing of sovereign reserves reveals that ownership and access are not identical. Financial crises reveal that liquidity and solvency are not identical. Infrastructure failures reveal that existence and availability are not identical. Again and again reality intrudes upon abstraction and reminds us that the world beneath the ledger still matters.

This is why the movement of gold deserves more attention than the declarations of economists, politicians, central bankers, or global forums. The repatriation of gold is not fundamentally a commodity story, an inflation story, or even a monetary story. It is a custody story. It is a sovereignty story. It is an acknowledgment that possession remains the final court of appeal whenever confidence begins to wobble.

The irony is difficult to miss. At precisely the moment civilization celebrates digital currencies, tokenized assets, algorithmic settlement systems, cloud-based records, and increasingly abstract forms of ownership, many of the institutions responsible for preserving national wealth appear to be moving in the opposite direction. Public narratives race toward virtuality while institutional behavior quietly migrates toward physical custody. The speeches point toward digitization while the bullion trucks point toward reality.

Perhaps nowhere does this contradiction become more visible than when contemplating the fragility of the infrastructure upon which modern finance rests. We speak confidently of balances, portfolios, reserves, pensions, derivatives, and increasingly digital assets as though they possess an existence independent of the systems that record them. Yet the entire architecture rests upon a remarkably delicate foundation of electricity, communications, computation, synchronization, and trust. We have become so accustomed to continuity that we mistake continuity for permanence.

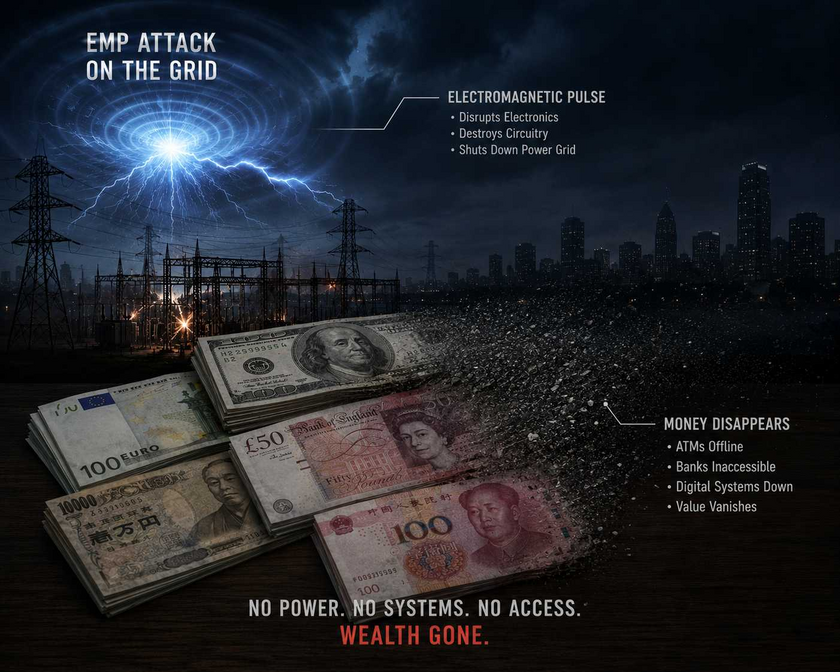
Consider not catastrophe but interruption. Consider a Carrington-scale solar event, a successful cyberattack, a cascading grid failure, or an electromagnetic pulse. The specific mechanism matters less than the principle. The lights go out. The servers stop responding. The networks cease synchronizing. The endless choreography of verification pauses. Legal claims may survive. Contracts may survive. Accounting entries may survive. Yet the practical ability to verify, transfer, access, or exercise those claims becomes uncertain. The abstractions remain theoretically intact while becoming functionally irrelevant.

Gold occupies a peculiar place within this thought experiment because it exists outside the thought experiment. It requires no password, no network connection, no authentication server, no intermediary, and no continuous electrical infrastructure to affirm its existence. The ledger may disappear. The gold remains. Whether one views gold as a monetary asset, a strategic reserve, or simply a historical curiosity, its persistence reveals something deeper about the nature of value itself. Assets that derive their existence from the systems that record them are fundamentally different from assets that exist independently of those systems.

What fascinates me, however, is not the rhetoric surrounding the so-called Great Reset, because the phrase itself has become one of the most effective distractions of the modern era. During the COVID years, populations were conditioned into increasingly reflexive forms of polarization in which every issue was immediately translated into opposing camps, every observation became a declaration of allegiance, and every question became a test of ideological loyalty. One side treated the Great Reset as evidence of a coordinated conspiracy while the other dismissed it as evidence of irrational paranoia. Both reactions produced the same outcome. Attention became fixed upon the slogan while remaining safely distant from the structure beneath it.

History has never required a committee to produce a reset. Resets emerge whenever claims become sufficiently detached from assets, whenever promises become sufficiently detached from productive capacity, whenever leverage becomes sufficiently detached from resilience, and whenever abstractions become sufficiently detached from reality. Long before a reset acquires a name, it exists as a tension embedded within the architecture itself.

This is why the most revealing actions in history are rarely the ones announced from podiums. They are the quiet movements that occur beneath the rhetoric. While populations argue over narratives, central banks move bullion. While commentators debate ideology, nations secure custody. While attention remains fixed upon political theater, the custodians of monetary power appear to be asking an older and more fundamental question concerning what survives when confidence falters, when access becomes uncertain, and when the systems responsible for recording ownership can no longer be assumed to function exactly as they did yesterday.

History repeatedly demonstrates that major transitions rarely emerge from the causes later assigned to them. Wars, sovereign defaults, financial crises, technological disruptions, infrastructure failures, and natural disasters frequently function as explanatory narratives that make visible contradictions that had already been accumulating for decades. The triggering event receives the blame because it is easier to understand than the architecture that rendered the event consequential. Yet the architecture is always where the real story resides. The event merely exposes what was already true.

Seen from this perspective, the most important question is not whether a particular organization intends to implement a Great Reset. The more important question concerns the conditions under which resets become inevitable. Whenever claims multiply faster than assets, whenever obligations expand faster than productive capacity, whenever financial abstractions drift sufficiently far from physical realities, tensions accumulate that eventually demand reconciliation. That reconciliation may arrive through inflation, restructuring, default, crisis, technological disruption, or events conveniently attributed to forces beyond human control, but the mechanism remains secondary to the principle. Reality eventually reasserts itself because reality is the only foundation upon which any abstraction can ultimately stand.

Viewed through that lens, the repatriation of gold appears less like a financial decision than an institutional acknowledgment that the distinction between claims and assets still matters. It represents a quiet recognition that resilience and possession acquire increasing importance precisely when complexity and uncertainty begin to rise. It suggests that beneath the public narratives, beneath the political theater, and beneath the endless distractions that dominate contemporary discourse, some of the world's most consequential actors may be asking the same question that inspired an essay sixteen years ago. What do you actually possess when the systems recording possession become uncertain?

The question is not fundamentally about gold. It is not fundamentally about vaults. It is not fundamentally about central banks. It is a question about the difference between a thing and a description of a thing, between ownership and access, between claims and assets, between abstractions and realities. It is the question that emerges whenever a civilization becomes sufficiently dependent upon representations that it forgets to examine the realities those representations are intended to describe.

Sixteen years ago I asked what was in your wallet. Watching nations quietly move bullion across oceans and into sovereign custody, the question feels sharper today than it did then. Not because the answer has changed, but because the institutions themselves appear increasingly unwilling to pretend that a claim and an asset are the same thing. The distinction sounded eccentric in 2010. It sounds increasingly obvious in 2026. The most interesting question is whether the rest of us will recognize the significance of that realization before history once again forces the issue on its own terms.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
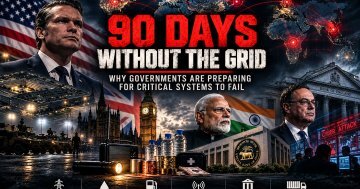
⚠️90 DAYS WITHOUT THE GRID⚠️
Why Governments Are Preparing for Critical Systems to Fail

MIND BEND THEORY | DOCUMENTED INVESTIGATION

The United States is preparing major military installations to continue operating if civilian infrastructure goes down. Britain is telling households to prepare for days without essential services. India is warning that an attack on the financial system can weaken a nation. And the Bank of England is asking what happens when cyber defenses fail—not if they can prevent every attack.

Individually, each development has an explanation.

Put them beside one another, however, and a larger pattern becomes visible.

Over the span of only a few weeks, governments and financial authorities in the United States, United Kingdom and India have publicly discussed preparations for disruptions involving some of the systems modern society depends upon most:

Power.

Water.

Fuel.

Communications.

Banking.

Supply chains.

This does not establish that these governments are preparing for one secret event.

There is no public evidence of a coordinated countdown, predetermined blackout date or single intelligence warning connecting them.

But there is something here that can be documented.

Governments are increasingly planning around a question that sounds very different from traditional emergency preparedness:

What happens when the systems we normally assume will be available are no longer available?

And in the United States, that question has now reached the Pentagon.

DOCUMENT 01

UNITED STATES — FORTRESS AMERICA

On September 30, 2026, Defense Secretary Pete Hegseth established a program called FORTRESS America.

The acronym stands for:

Federal Operations for Resilience, Troop Resources, Energy, Supply and Survivability.

The program addresses a vulnerability that rarely receives much public attention:

The world's most powerful military still depends extensively on civilian infrastructure.

Electric grids.

Commercial supply chains.

Communications infrastructure.

Fuel.

Foreign sources of critical materials.

FORTRESS America is intended to reduce those dependencies.

The Pentagon's own public description says the initiative is designed to ensure that major U.S. military installations generate independent power so that bases remain operational even if the civilian grid is taken down by cyberattack or sabotage.

It goes beyond electricity.

The program includes five major areas:

Energy independence

Installation hardening and cyber resilience

Supply-chain and defense-industrial-base resilience

Strategic defense reserves

Space and spectrum resilience

The Pentagon also wants deeper reserves of critical supplies so military operations can continue when ordinary supply lines are disrupted.

The underlying idea is simple:

The military should be capable of functioning even when the infrastructure surrounding it cannot.

An October 7 implementation memorandum obtained by DefenseScoop shows that the Pentagon had already begun establishing the FORTRESS America Program Office and assigning officials to implement those objectives.

Then another piece of the story emerged.

DOCUMENT 02

THE 90-DAY REQUIREMENT

On October 25, Fox News published details from additional FORTRESS America documents its reporters reviewed.

According to that reporting, major continental U.S. military installations are being prepared to sustain essential operations for at least 90 days without outside support.

The essential systems reportedly include:

Power.

Water.

Fuel.

Communications.

Think about the distinction carefully.

The Pentagon isn't telling Americans that the United States will lose electricity for 90 days.

It isn't predicting a 90-day blackout.

Military contingency planning deliberately prepares for scenarios officials hope never occur.

But preparing installations for this possibility tells us something about the scenario being considered.

The Pentagon is building resilience around the possibility that a sufficiently serious conflict or attack could interfere with the civilian systems on which military installations normally depend.

The publicly released FORTRESS material specifically discusses:

Cyberattack.

Sabotage.

Grid disruption.

Foreign supply-chain disruption.

Attacks against installations.

And prolonged military contingencies.

That makes the 90-day requirement significant—but it must be described accurately.

Mind Bend Theory verification note:

The September 30 FORTRESS America program itself is documented publicly.

The October 7 implementation memorandum has been reported and described by DefenseScoop.

The 90-day requirement, however, currently comes from documents reviewed by Fox News, rather than a primary 90-day document independently published for the public.

That distinction matters.

We follow the documents as far as they take us—and no farther.

DOCUMENT 03

UNITED KINGDOM — BE READY FOR THREE DAYS

Now cross the Atlantic.

On October 22, the British government launched its new Be Ready campaign.

This time the audience wasn't the military.

It was ordinary households.

The UK government is asking households that are able to do so to prepare to remain self-sufficient for approximately three days during an emergency.

The government specifically discusses disruptions affecting:

Power.

Water.

Phones.

Internet access.

A Parliamentary Written Statement issued the same day explicitly states:

“The updated advice calls on households to be self-sufficient for three days in the case of an emergency.”

The government recommends maintaining three days of bottled water and non-perishable food.

Its expanded preparedness guidance includes:

Approximately three litres of drinking water per person per day

Three days of non-perishable food

Battery-powered or wind-up radio

Torch and spare batteries

Charged power bank

Essential medications

First-aid supplies

Blankets and warm clothing

Important telephone numbers written down

Basic hygiene supplies

Cash

Why cash?

Because during some disruptions, electronic payment systems and ATMs may not function normally.

That creates an important connection between infrastructure and finance.

Electricity isn't isolated from banking.

Communications aren't isolated from payments.

Modern infrastructure is interconnected.

And failure can move through those connections.

DOCUMENT 04

INDIA — “WARS ARE NOT FOUGHT WITH WEAPONS ALONE”

Three days later, on October 25, another statement appeared.

This one came from Indian Prime Minister Narendra Modi.

Modi was inaugurating the Reserve Bank of India's newly established Data Centre and Cybersecurity Training Institute in Bhubaneswar.

The facilities are designed to strengthen the technological foundations and cybersecurity resilience of India's financial system.

Four data centres will host mission-critical payment and settlement systems.

But Modi's explanation of why this matters went beyond ordinary cybersecurity.

His official statement says:

“Nowadays, wars are not fought with weapons alone; a nation can also be weakened by attacking its economy.”

He continued by saying India's growing economy requires its banking system to be protected against cyber looters and cyber terrorists.

That puts another critical system into the picture:

Money.

A modern economy depends on digital banking infrastructure almost as heavily as it depends on electricity and telecommunications.

Payment systems move commerce.

Banks hold liquidity.

Settlement systems move money between financial institutions.

Data centres keep those networks functioning.

Disrupt the financial infrastructure badly enough and the consequences don't remain inside banks.

They reach businesses.

Supply chains.

Payroll.

Purchasing.

Markets.

And households.

DOCUMENT 05

BANK OF ENGLAND — WHAT IF CYBER DEFENSE FAILS?

There is another document worth reading.

On June 30, Bank of England Deputy Governor Sarah Breeden delivered a speech titled:

“Agents of Change.”

The subject was artificial intelligence and financial stability.

One section deserves particular attention.

Breeden warned that advanced AI systems are becoming increasingly capable of identifying and chaining together cyber vulnerabilities.

That changes the nature of cyber risk.

AI can help defenders.

But the same capabilities can potentially increase the speed and effectiveness of attackers.

The important change in thinking comes afterward.

Preventing attacks is no longer enough.

Financial institutions must also prepare to recover after a successful attack.

Breeden raised the possibility of simultaneous disruption across multiple financial firms.

She then asked whether critical financial institutions may eventually require completely separate failover capabilities—or even the ability to rebuild compromised core systems from “bare metal.”

In October, Reuters reported that the Bank of England was pushing financial institutions further toward this type of recovery planning.

That represents a subtle but significant change in the question.

It isn't simply:

How do we stop the attack?

It's becoming:

What happens if we don't?

And:

How do we keep the system functioning afterward?

CONNECT THE DOCUMENTS

Now put the documents beside one another.

UNITED STATES

Military installations are being hardened so essential operations can continue when civilian infrastructure is disrupted.

UNITED KINGDOM

Households are being told to prepare for three days without services they normally assume will remain available.

INDIA

The prime minister publicly warns that modern conflict can weaken a country by attacking its economy and calls for stronger protection of banking infrastructure.

BANK OF ENGLAND

Financial authorities are examining recovery scenarios in which cyber defenses have already failed and multiple institutions could potentially be disrupted simultaneously.

These aren't identical programs.

They aren't even aimed at the same people.

And there is currently no public evidence demonstrating that they were coordinated.

But they share one important assumption:

CRITICAL SYSTEMS CAN FAIL.

And resilience therefore cannot begin after the failure occurs.

It has to exist beforehand.

THE SYSTEM BEHIND THE SYSTEM

This is where the story becomes bigger than individual announcements.

Modern infrastructure isn't a collection of isolated systems.

It's a network.

Consider what happens when electricity fails.

Without power, telecommunications eventually become difficult to maintain.

Without communications, electronic payments can be affected.

Fuel pumps require electricity.

Water systems depend on pumping and treatment infrastructure.

Businesses depend on payment processing.

Supply chains depend on communications, transportation and fuel.

Hospitals require electricity, communications, water, medicine and logistics simultaneously.

A serious disruption doesn't necessarily remain inside the system where it started.

It can propagate.

POWER → COMMUNICATIONS → BANKING → COMMERCE → SUPPLY CHAINS

And the dependency runs in multiple directions.

That interconnectedness is precisely why governments plan for resilience.

WHAT THIS DOES NOT PROVE

Mind Bend Theory exists to examine unusual patterns.

But a pattern isn't automatically proof of a conspiracy.

There is currently no public evidence showing that Washington, London and New Delhi are secretly preparing for the same scheduled event.

There is no verified date for a coming global blackout.

There is no public document establishing an imminent 90-day collapse of the American electrical grid.

And the Pentagon's 90-day military resilience requirement should not be interpreted as a prediction that Americans will lose electricity for 90 days.

That would go beyond the evidence.

What the evidence actually establishes is interesting enough.

Governments increasingly consider disruption of power, communications, supply chains and financial infrastructure plausible enough to justify concrete preparation.

The UK is preparing households.

The United States is hardening military infrastructure.

India is strengthening the technological backbone of its financial system.

The Bank of England is thinking about how banks recover after cyber defenses fail.

That isn't speculation.

It's in the documents.

THE QUESTION

Perhaps the most important change isn't what governments believe will happen.

It's what they're preparing to survive.

For decades, infrastructure security focused heavily on preventing failure.

The emerging model looks different:

Assume something eventually gets through.

Assume something eventually goes down.

Build the ability to continue operating anyway.

The Pentagon calls that resilience.

The UK calls it being ready.

Central banks call it operational resilience.

Different terminology.

Same fundamental question:

WHAT STILL WORKS WHEN THE SYSTEM DOESN'T?

DOCUMENT TRAIL

Read the Evidence Yourself

Mind Bend Theory strongly encourages readers to examine the original material rather than relying solely on our interpretation.

🇺🇸 DOCUMENT 01 — FORTRESS America Establishment

September 30, 2026

Defense Secretary Pete Hegseth's memorandum establishes FORTRESS America as a Department of Defense resilience program.

The publicly reported memorandum establishes the program around installation resilience, independent energy, strategic reserves, supply chains and related national-defense infrastructure.

Source type: Pentagon memorandum / official announcement.

🇺🇸 DOCUMENT 02 — FORTRESS America Implementation Memorandum

October 7, 2026

DefenseScoop obtained the memorandum from Under Secretary for Acquisition and Sustainment Michael Duffey directing officials to begin operationalizing the FORTRESS America Program Office.

It identifies five foundational pillars, including energy independence, installation hardening and cyber resilience, strategic reserves and supply-chain resilience.

Source type: Pentagon memorandum obtained by DefenseScoop.

🇺🇸 DOCUMENT 03 — 90-Day FORTRESS Requirement

October 25, 2026

Fox News reports that documents it reviewed require major continental U.S. installations to sustain essential operations for at least 90 days without outside support.

Source type: Journalistic reporting based on documents reviewed by reporters.

Important: This is not currently being presented by Mind Bend Theory as a publicly released primary 90-day Pentagon document.

🇬🇧 DOCUMENT 04 — UK Cabinet Office Be Ready Announcement

October 22, 2026

The Cabinet Office announces the three-year Be Ready campaign and describes preparation for disruption affecting power, water, phones and internet.

Source type: Official UK government publication.

🇬🇧 DOCUMENT 05 — Parliamentary Written Statement HCWS409

October 22, 2026

The UK Parliament records the government's explicit recommendation that households prepare to remain self-sufficient for three days.

Source type: Official Parliamentary record.

🇬🇧 DOCUMENT 06 — Be Ready Household Emergency Checklist

The government's practical household guidance provides recommendations for water, food, radio, lighting, medication, power banks, emergency cash and other supplies.

Source type: Official UK government preparedness guidance.

🇮🇳 DOCUMENT 07 — Prime Minister of India / RBI Cybersecurity Facilities

October 25, 2026

Official statement documenting the opening of the Reserve Bank of India's Data Centre and Cybersecurity Training Institute and Modi's warning that countries can be weakened through attacks against their economies.

Source type: Official Government of India statement.

🇬🇧 DOCUMENT 08 — “Agents of Change” — Sarah Breeden

June 30, 2026

The Bank of England deputy governor discusses rapidly advancing AI cyber capabilities, simultaneous disruption across financial institutions, separate failover infrastructure and potentially rebuilding compromised systems from bare metal.

Source type: Official Bank of England speech.

DOCUMENT 09 — Bank of England Cyber-Recovery Reporting

October 15, 2026

Reuters reports on the Bank of England's push for stronger recovery capabilities against AI-enabled cyberattacks, including bare-metal recovery.

Source type: Independent reporting.

MIND BEND THEORY

Follow the documents. Separate what they prove from what they don't.

Then ask why the preparation is happening now.

Documents attached to the investigation

FORTRESS America — Sept. 30 memorandum record
Pentagon FORTRESS America implementation memorandum — DefenseScoop
FORTRESS America 90-day documents — Fox News investigation
UK Cabinet Office — Be Ready announcement
UK Parliament — Written Statement HCWS409
India PM's Office — RBI Data Centre & Cybersecurity Training Institute
Bank of England — Sarah Breeden, “Agents of Change”
Reuters — Bank of England cyber-recovery warning

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
September 13, 2026
post photo preview
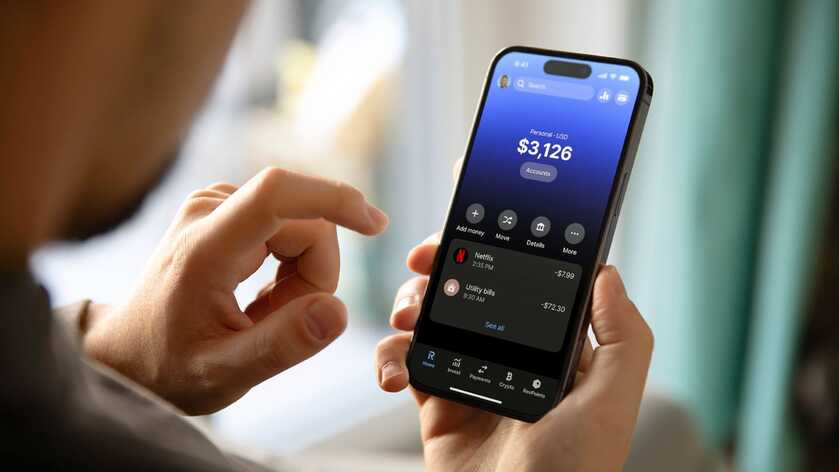
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals