Dinarian888
News • Business • Investing & Finance
Elon Musk & The Transformation of Twitter: By Citizen Of The Future
April 12, 2023
post photo preview


The New-Era Bird App is Fulfilling X.com’s Original Vision

Over the last couple of months, there has been much talk about Elon Musk's acquisition of Twitter and the hate narrative that has emerged in mainstream media. This tells us that there is resistance to change and a desire to maintain the status quo in the financial world.  However, change is inevitable, and the rise of decentralized networks & Truth Twitter applies to that. 

In this report we will delve into X.com and the prior discussions of decentralized trust networks around 2012 and how they are transforming the way we communicate and handle money. We will also review other articles from that time period to try and gain insights into the future of social media and the financial system. This research took me about 25 hours to put together so I hope you enjoy an exclusive reveal of the following content: 

  • What Elon Musk is planning with Twitter infrastructure and his X.com Domain, and paths for the future of Twitter 2.0

  • Results of backlink analysis from X.com and the uncovering of documents that haven’t been shown on mainstream internet since 2012, which showcase some of the original vision of  X.com 

  • Comparisons of Facebook & Twitter users from A Decade of Growth- 2012 to 2022 

  • An article showing how Ripple Trust Networks were an early discussion point from X.com and how they how they are Transforming Money, which lead me to find Ryan Frogger’s original Ripple website which dated back to 2006

  • Snippets from articles relating to X.com in 2012 discussing how The future of money is the Web, towards national cryptocurrencies, and what would happen if social media and payments merge and we discover a new payments utopia - and much more…

Elon Musk & the Twitter Acquisition

Let’s begin with Elon’s acquisition of Twitter that started on April 14 2022, and concluded on October 27 2022, for a price of $44 billion dollars. He has now taken Twitter from a public offering to a private company. Within the first month of his takeover, he provided the Twitter employees with two choices: 

1. Stick around and help build his vision of “Hardcore Twitter 2.0” and that employees who choose to stay will be required to commit to working “long hours at high intensity”.

2. Say goodbye and accept a layoff. This decision allowed him to trim the fat at the company, which led to laying off over 3700 employees, leaving him with ones dedicated to bringing his vision of Twitter 2.0 to life. 

In conversation with Ron Baron in Nov 2022, Musk said he will execute the X product plan “with some improvements”, which will make Twitter “the most valuable financial institution in the world” with his domain of X.com.

The Start to the End of an Era of Censored Speech

We all know the feeling of being censored and not having our voices heard. We all have opinions, and we should be able to share them regardless of whether they are deemed appropriate by others. 

We have witnessed ample censorship on social media platforms. On Facebook, mainstream media outlets disable citizens from commenting on specific stories such as the Maxwell and Epstein articles. Why can’t citizens freely discuss the mainstream news articles? Why do they get to control what the masses can have conversations about when it comes to their content?

The old Twitter - pre-Elon Musk - did not have an edit button and it would censor citizens who did not fit the mainstream narrative. It is great to see some of the previously censored individuals get their voices back, allowing for a neutral town hall where all opinions can be heard and challenged.

Twitter Censored Information Around Leaked Hunter Biden laptop

If you want to learn about how extensively that Twitter manipulated content, please check out the newly released December 2nd 2022 “Twitter Files” that tell an incredible story from the inside of Twitter. It shows the Frankenstein-tale of a human-built mechanism, grown out of the control of its designer.

This story shows the old Twitter wasn’t balanced. Decisions were made based on contacts, and Twitter was overwhelmingly staffed by people of one political orientation. There were more channels for complaint open to the left-leaning individuals versus the right. With the proof from the Twitter Files, it was shown how Twitter took extraordinary steps to suppress the Hunter Biden laptop story by removing links and posting warnings that the link may be ‘unsafe’. They even blocked its transmission via direct message, a tool hitherto reserved for extreme cases. This was all done to prevent citizens from viewing the content involved with the leaked information on Hunter Biden’s laptop right before the 2020 Election.

Note:  Since the time of writing there are now two more Twitter Files:  #TwitterFiles2 #TwitterFiles3

Twitter 2.0 - The Bird App is Evolving & Obtaining a Money License

Twitter has started the registration procedure for processing payments by submitting documentation to the Financial Crimes Enforcement Network (FinCEN) on Nov 3, 2022.

Businesses must register with FinCEN in order to make money transfers, swap currencies, or pay checks. This will end up creating a never before seen “payments utopia'' by combining social media with instant and cheap cross-border payments. I think this is the start to major cryptocurrency adoption for specific networks with real-world utility.

Shoutout to Citizen @ChrisPaulHall on Twitter for sending this document my way!

A Blast From the Past! A Review of Documents Hidden From the Internet for over 10 years - X.Com Research Results…

Currently, when you go to X.com there is nothing to see as nothing on the website is public. Many people would just give up and move on, but I used this as motivation to dig deeper. I used my skill set of backlink analysis and started researching the domain of X.com to see what websites were linking to this domain. I found there were 2.1 million backlinks on the internet that point to X.com. 

**A backlink is when a website links to another website in a piece of content, “A link leading back to their website”.**

With this ocean of information connecting to X.com, I spent hours digging through 25,000 links and seeing what I could find on this untouched topic.  Out of the top 11 out of 25,000 backlinks I analyzed that are linked to X.com, these were the most important links that I found:

While researching, I was shocked at being able to gain access to these documents that have been buried & deleted from the internet - thank God for the great Web Archive!  It's mind blowing to think about the fact that these articles were all written between 2010 - 2014 before PayPal became an independent, publicly traded company. 

Please enjoy the following article summaries and the video above accompanying my research.  

“How Ripple Networks are Transforming Money” | X.com

April 20, 2012 by Manu Sporny

As I was digging through my internet history from 10 years ago, I came across an article that caught my attention. The article was written by Manu Sporny for X.commerce, the e-commerce platform that was being developed by eBay.

In the article, Sporny discusses and explains a concept called Ripple Trust Networks, a decentralized network of payment channels that enables real-time, low-cost transactions between parties. He states it has the potential to greatly reduce the costs and complexities of cross-border payments compared to the expensive and slow correspondent banking system.

He also suggests that the use of the ripple network concept in a decentralized setting would have significant economic implications. This would shift tens of billions of dollars in profit from credit card companies to individuals. Individuals would be able to make payments directly with each other without needing to go through a central intermediary like a credit card company.

Furthermore, he suggests that the ripple network would reduce the cost of short-term loans by providing a highly competitive market in which people could request and receive lines of credit. This is because the decentralized nature of the ripple network would allow for a greater number of lenders to participate in the market, increasing competition and driving down interest rates. Overall, he is emphasizing the potential power of decentralized networks like the ripple network and links to a live implementation to the concept he was speaking about. I clicked it and it brought me to one of the first versions of Ripple in 2012 with 4500 network users. Using this link I was able to dig deeper and find the very very first version of the Ripple website dating back to March 2006. This led me to find the initial Ryan Fugger Ripple white paper from 2004. 

“This is the power of the Web—people-powered finance through ripple networks and decentralized payments.”

Additionally, I learned about W3C's Payswarm initiative, which was a proposed open standard for the secure and efficient exchange of digital assets and payments on the web. This initiative was being developed by the World Wide Web Consortium (W3C) Payments Working Group, which aimed to create a technical framework that would enable web-based payment systems to inter-operate seamlessly and securely. But I cant seem to find anything after 2014 so I think it died or had a name change. If you go to https://www.payswarm.com/ it redirects to a W3C Working Group. 

Reading these articles from 10 years ago made me realize just how much progress has been made in the field of digital payments and blockchain technology. It's exciting to see how far we've come and to think about the potential for even further advancements in the future. It's clear that the Ripple Trust Network concept and other W3C Initiatives are transforming the way we think about money and payments, and I'm excited to see where this technology takes us in the next 10 years.

“How Crypto Currencies Transform Money” | X.com

April 27, 2012 by Manu Sporny

This is a very interesting read that provides insight into some high-level thinking of the X/Paypal crew around FIAT & cryptocurrencies back in 2012! The article breaks down the problem with FIAT currencies and how we moved from a silver/gold backing of currency to nothing backing the dollar. It also explains the centralized concept with central banks that control the money printer. 

They state:

“It truly is a remarkable leap of faith that we make. The US dollar has worth because it is backed by the US government and therefore is backed by its people…”

They have a great breakdown of some character traits regarding a “trustworthy cryptocurrency” which can be still used today. They talk about Bitcoin being in the “Tens of Millions of Dollars” – what a throwback! 

The ending of the article talks about moving toward “National Crypto Currencies” that sound like Central Bank Digital Currencies, an innovation that we have been witnessing the adoption of for the last couple of years:

“A fiat-based crypto-currency could operate alongside these other services as an alternative technology-based mechanism for money transmission. The liabilities—like those held by most banks, credit card companies, and money transmission services—would fall squarely on the companies providing the software to use the crypto-currency.”

Manu explains that to replace cash, it is necessary to have open crypto-currency standards, and that developing nations may be the first to make the switch since they are not politically influenced by the banking and finance sector to the degree that more developed nations are (cough in 2022, SEC Gov). Other nations may choose to adopt crypto-currencies in order to increase the efficiency of their market, thus giving them a competitive advantage. 

“Open Web Payment Standards and the New Economy” | X.com

Written May 11, 2012 by Manu Sporny

This article is important, as it talks about “Open Payment Stands” for the Web and how the W3C could open up the “ivory tower of finance and banking” to the general public. Their goal is to create a more transparent, competitive, and fair financial system. They list important things about open payment standards and talk about the world’s first universal payment standard for the Web, which they call a solution called “PaySwarm”. This named solution is no longer around, and I have not figured out what has happened to it yet.

“The Crisis of Money and Its Metamorphosis” | X.com

April 10, 2012 by Manu Sporny

This is a very important article that everyone should read to really get an understanding of cash (FIAT) and the transformation happening with the global monetary system. This article contains a lot of value:

“The past several years have not been kind to the world’s working class and working poor. The foundations on which we have built the institutions of commerce—the markets, the banks, and government—have proven to be less reliable than we had believed, resulting in a wave of monetary crises around the world. Each was met with our brightest national leaders scrambling to correct the instability through obscene injections of capital and massive creations of debt on behalf of the peoples of this world.” 

It talks about being the time to put forth a plan that uses the web, the best communication platform that we have today, to solve our collective monetary crisis. The article then explains the understanding of how we arrived in this predicament and examines the purposes of debt, money, and banking. It goes and talks about debt and the financial system in the early years of global society and how banks have shifted and taken over the economic system. They describe “The Web as an Engine for Innovation” and talk about “Rethinking the Foundations of Money” 

They also talk about “Ripple Trust Networks” powering people's credit.

“The Future Money & The Web” | X.com

May 18, 2012 by Manu Sporny


This is another great informational article where they talk about the concept of “a ripple”, a trust network, and how we could change the way we provide loans and credit - it talks about how cryptocurrencies are poised to replace physical money. He talks about the web as a lifetime depository and how to standardize digital wallet, with it one day coming in place so you can access it from anywhere. 

It also explains how finance is shifting to the web as fintech can innovate faster, using the web base architecture, then traditional banks, and credit card networks. They state in this article, at the time of writing, that there were 2 billion people who use the web. In 2022, there are now around 5 billion people who have access to the web.

“Perhaps the Web’s biggest contribution to our lives has not been the technology itself, but rather a new way of thinking about how we work together to solve the most pressing problems of our time.”

“The Future of Commerce Will Combine Your Social Network and Mobile Device” | X.com

This was from September 21, 2012, written by Nick Hughes. In this article, they discuss:

“If Those Two Powerful Phenomena Merge, Will We Discover a New Payments Utopia?”

They also state:

“Facebook and Twitter, together making up more than a billion socially connected web users, have positioned themselves well for the possible next phase of commerce. Facebook, for instance, recently reported now having 955 million monthly active users and 552 million daily active users. It also said it had 543 million active mobile users, who are much more engaged than its PC users”.

It was also stated that Facebook had over 11 million business profiles! This means in 10 years, as of 2022. 

Facebook has 3 billion monthly users and 2 billion daily users, with over 200 million Facebook business pages. In 2012, Twitter celebrated its 6th birthday while also announcing that it had 140 million users and 340 million tweets per day. Today those numbers are at 450 million monthly active users and around 500 million tweets per day. This article also talks about combining a user ID with a mobile device ID and connecting a secure payment credential, thus having one quick checkout – online or offline. 

These are the last two important statements I want to point out, then picture what Elon Musk is doing today:

“Now imagine if instant and automatic transactions were coded into those sorts of buttons, allowing the user to transact with a securely stored payment credential on a third-party server in just one click from his or her mobile device.”


“If you are developing a mobile payment platform, it only makes sense to consider the imminent power of social sharing and how it will enhance the commerce experience for people around the world.” 

It’s neat to see how social media is exponentially growing and connecting citizens of the globe. I wonder what life is going to look like, reflecting on this, 10 years from now! They also use a great example of “How Facebook Could Transform the Mobile Commerce Market”.

The Bottom Line…

There is now no doubt about it – we are at the start of a new era of payments and social media. This plan has taken over 10 years to come to fruition, and I am so thankful I am doing my homework now, before the transformation has taken place. 

In conclusion, I hope that my research on the connections of the past has provided an interesting and insightful look at the developments that have shaped the current landscape of freedom of speech and payments. As we enter a new era of technology and innovation, it is important to embrace the opportunities and challenges that come with it. The clock is ticking and the whole world is asleep thanks to mainstream media, but it is up to us to awaken and embrace the potential of this moment in time. I hope you have enjoyed reading this edition of the Genfinity's LightHouse Report, and I look forward to sharing more insights and perspectives with you in the future.

Never stop learning and never stop improving! 

Sincerely, 

Citizen of the Future

community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
Ripple President Monica Long announced the use of XRP-POOLS 🤯

Ripple President Monica Long announced the use of XRP-POOLS to leverage XRP as collateral for funding customers’ payments from credit card institutions.

We are talking here about TRILLIONS of DOLLARS on the XRP-Ledger!

OP: Jacktherippler

00:00:28
🔥 Interview With Jacob "Const" Steeves, Co-Founder of Bittensor 🔥

Insane Interview Jacob "Const" Steeves (@const_reborn), Co-Founder of Bittensor and CEO of Affine, for an deep dive into what's coming next for Bittensor! 🧠⚡️

From fighting the AI cabal and competing with frontier labs to revenue models and Gamma Tokens—we covered it all. 🔥

⏱️ Timestamps:

0:00 Meet Jacob "Const" Steeves 👋
0:27 Fighting the AI Cabal 🛡️
8:40 Competing With Frontier Labs ⚔️
11:02 Templar's Departure & Teutonic 🏛️
15:44 Research, Revenue & Gamma Tokens
21:31 What's Next for Bittensor? 🔮

Catch the full conversation below! 📺👇

00:23:20
🪙 Is a Gold-Backed Dollar Making a Comeback? 🇺🇸🟡

The global financial landscape could be on the verge of a historic pivot. The U.S. Treasury has reportedly hired economist Judy Shelton—a vocal advocate for a gold-backed currency for three decades—sparking intense speculation about the future of the monetary system. 📈📉

The Core Proposal & Historical Context 📜⏳

🔹 The Shelton Plan: The proposed mechanism involves issuing a Treasury bond that holders can redeem for either U.S. dollars or physical gold.

🔹 A Nod to the Past: This exact promise was standard on U.S. war bonds until 1933, when Congress ultimately suspended convertibility during the Great Depression. 🏦💵

The Global Gold Rush 🌍🏦

🔹 The Biggest Stack: The United States currently holds 8,133 tonnes of gold—the largest reserve on the planet.

🔹 Global Accumulation: Central banks worldwide are stacking gold at an unprecedented rate. For instance, China has aggressively purchased gold for consecutive months, and ...

00:02:45
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading

🚀 Why Buying $TAO at $300 Might Still Be Early 🚀

The narrative around Bittensor ($TAO) is shifting from speculative crypto project to fundamental infrastructure for the coming AI era. At around $300, the market is still pricing it as the former, while the evidence points to the latter.

🔑 Key Points:

🔹 It's Not Just a Token, It's a Protocol: $TAO is the native currency of a decentralized machine intelligence network. It's the incentive layer that coordinates and rewards the creation of AI models in a trustless, open marketplace. This is a new asset class: protocol-level AI capital.

🔹 The "AWS Moment" for AI: Bittensor aims to commoditize and democratize machine intelligence, just as AWS did for servers. It allows anyone with a GPU to contribute and earn, creating a decentralized intelligence grid.

🔹 The Valuation Perspective: Compared to trillion-dollar centralized AI companies, the entire Bittensor network has a fully diluted valuation of roughly $20 billion. This is a rounding ...

🤖 Grok Bot adds proactive suggestions that spot work before users ask 🤖

Grok Bot can now identify tasks it may be able to handle and proactively suggest them to users through their selected Primary Bot.

🔑 Key points

🔹 Suggestions are proactive: Users no longer need to initiate every task manually.

🔹 Inbox triage can be suggested: Grok Bot may offer to review, organize, or prioritize incoming messages.

🔹 Meeting preparation can be automated: The Bot can suggest preparing agendas, briefing materials, summaries, or relevant documents.

🔹 Follow-up drafting is included: Grok Bot may identify situations where a follow-up message or response could be prepared.

🔹 Suggestions do not use the weekly quota: The proposal itself reportedly does not count against the user’s weekly usage limit.

🔹 Primary Bot selection is required: The capability becomes available when a Bot is selected as the user’s Primary Bot in the app.

🔹 Memory remains attached to the Bot: The assistant can use the ...

⚡ Chutes’ Kappa matches Llama 3.2 1B using 94% fewer training tokens ⚡

Chutes (SN64) trained Kappa across a decentralized GPU network and reportedly matched or exceeded Meta’s Llama 3.2 1B on several benchmarks using roughly 576 billion tokens instead of up to 9 trillion.

🔑 Key points

🔹 94% fewer tokens: Kappa reached comparable results to Llama 3.2 1B with a much smaller training budget.

🔹 Benchmarks included ARC-C, OpenBookQA, and TruthfulQA: Kappa reportedly matched or outperformed Llama 3.2 1B across those evaluations.

🔹 Training happened across distributed GPUs: Parallax coordinated independently operated hardware in different regions and with different performance levels.

🔹 Training costs were reportedly 90% lower: Chutes estimates Kappa’s cost per training token was significantly below conventional centralized approaches.

🔹 Hybrid architecture improves efficiency: Kappa combines traditional attention with Gated DeltaNet-2 linear attention to reduce memory and compute ...

September 13, 2026
post photo preview
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
This Is The Income A Family Needs To Live Comfortably In Every US State

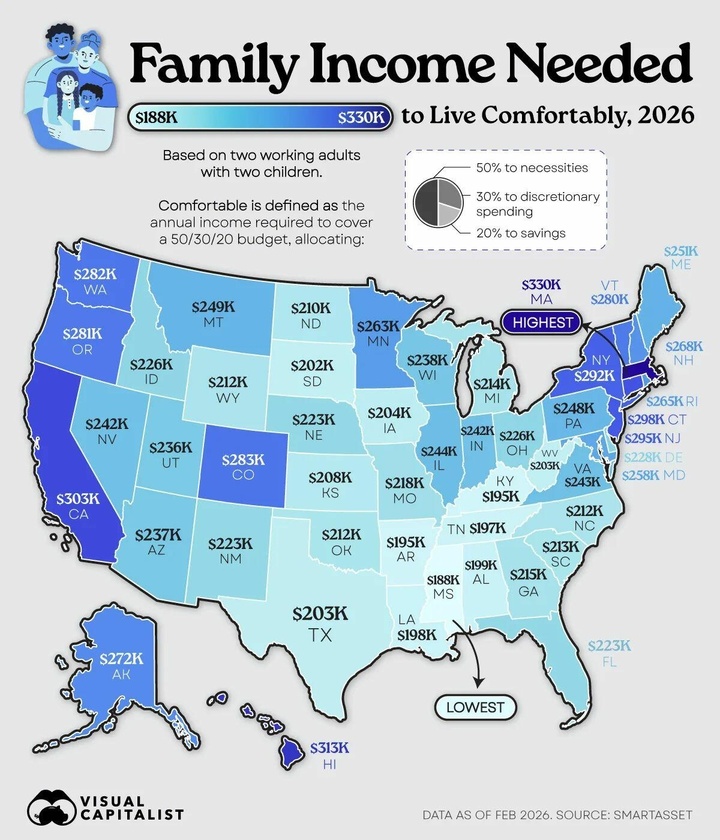
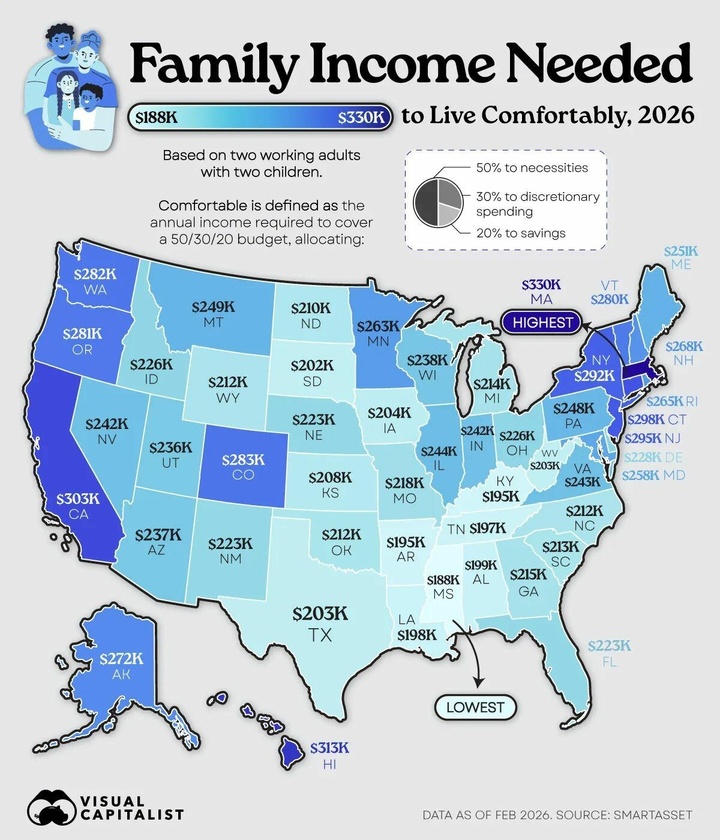
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notes, Massachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals