Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents. |
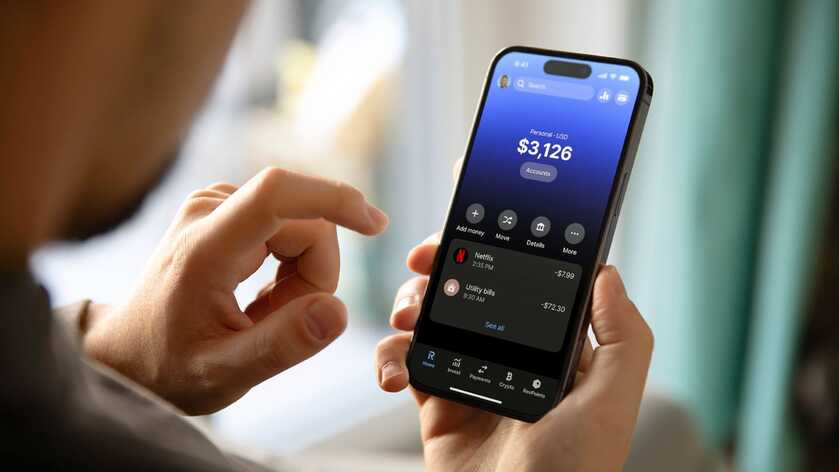
Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request. The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies. Revolut claims that derived biometric face data was not. The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency. The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself. Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not. Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities. Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen. The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.  The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones. One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons. This means that even if you close your account, your identity documents don’t disappear. And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked. This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals. It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss. The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.
🙏To support my work, Helping to keep the signal high and the noise low: 👉 Cashapp: $thedinarian 👉 Buy me a coffee: https://buymeacoffee.com/thedinarian 👉 PayPal: Scan the QR code below 📲 or Click Here:
👇 Crypto Donations 👇 XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX |
Dinarian888
?The Dinarian exists because the truth deserves a platform. Covering cryptocurrency, blockchain technology, global agendas, emerging science, and consciousness — because everything is connected and people deserve to know it. Knowledge is power. ?
Interested? Want to learn more about the community?

Dinarian888@dinarian888
May 25, 2023
Gary Gensler Remarks before the Atlanta Federal Reserve Financial Markets Conference
So the story goes, in 1871, Mrs. O’Leary’s cow kicked over a lantern. Her barn was enflamed. The fire spread quickly through the wooden buildings of Chicago, and 2,100 acres burned.[1]
In the following years, Chicago rebuilt itself with new rules and an upgraded fire department to limit the risk of flames raging across the city.[2] Those Chicagoans understood this wasn’t just a simple accident of a cow and a lantern. It was about building materials and incentives related to the city’s infrastructure. It was about fire prevention and firefighting equipment.[3] Building codes and fire departments, though they come at a cost and need for updates, have made the community more resilient for 150 years.
Finance, too, has seen fires starting in one barn that go on to engulf entire communities.
Finance
Finance is about the pricing and allocation of money and risk throughout the economy. There are those who have money who want to invest it. Others need money to fund good ideas, buy a house, or help get through life’s inevitable challenges. There are those who have risk but don’t want to bear it, and others willing to take on that risk.
Finance sits in the middle, like the neck of an hourglass whose grains of sand are money and risk. Finance is a network that relies on trust.
Since antiquity, finance has tended toward centralization, concentration, and economic rents—whether the Medici family back in the 15th century or J.P. Morgan a century ago. That’s because financial intermediaries benefit from scale, network effects, and access to valuable data.
Such intermediaries don’t just sit passively passing the sand through the hourglass. They become important market participants themselves. They retain and transform money and risk. They seek profits from arbitraging differences in pricing of money and risk. They create forms of money, whether it be deposits, money market funds, or funding in the repurchase (repo) markets. They retain risks related to valuations, rates, credit, funding, liquidity, maturity transformation, leverage, correlations, operations, and many others. Such intermediaries also tap the capital markets, and in times of stress, may lose funding if counterparties and investors question their market-based solvency.
This is the nature of finance. Just as we can’t repeal the laws of physics and nature, risk in finance always will be there. As Treasury Secretary Bob Rubin used to say, “Markets go up, markets go down.”[4]
Financial Fires through Time
History is replete with times when fires in one corner of the financial system or at one financial institution spread to the broader economy. When this happens, the American public—bystanders, like the Chicagoans who saw their homes burn—inevitably gets hurt.
Such fires, though too many to name, have started from both the banking and nonbanking sectors.
It is said that the Chicago fire along with another in Boston helped fuel a bank run, possibly contributing to the Panic of 1873.[5]
Decades later, the Panic of 1907 ultimately led to President Wilson’s reforms to establish the Federal Reserve with authorities both as a building code regulator and as a form of a fire department.[6]
The 1929 Crash and ensuing Great Depression led President Roosevelt and Congress to set up the Federal Deposit Insurance Corporation[7] and Securities and Exchange Commission.[8]
In the early 1930s, in the town of Bedford Falls, NY, there was a run on Bailey Bros. Building and Loan. George Bailey explained to the panicked crowd, “The money’s not here. Your money's in Joe's house... and a hundred others.” Fortunately, Jimmy Stewart saved the day, as told in It’s a Wonderful Life.[9]
The financial fires of 2008 led to more than eight million Americans losing their jobs, millions of families losing their homes, and small businesses across the country folding. This led to updates in building codes and fire departments for finance in the Dodd-Frank Act.
Fires and Resiliency
Economists have written extensively on the causes and contagion of financial fires. Such financial stability literature highlights herding, network interconnectedness, and regulatory gaps.[10]
Herding is when multiple individual actors make similar decisions. In times of stress, otherwise uncorrelated actors can suddenly become correlated, like those cows stampeding in City Slickers.[11] Given that greed and fear both are basic emotions in markets, herding occurs for both bulls and bears. Whether it be breakdowns in risk management, such as in the subprime mortgage market prior to the 2008 crisis, or breakdowns in confidence, such as in bank runs, herding has contributed to many a financial fire.
Finance is a complex, interconnected, global network, with many transmission channels by which financial fires might spread. During the financial crisis, Andy Haldane, then the head of financial stability at the Bank of England, compared the financial network to tropical rainforests, at the same time robust and fragile.[12]
The Great Chicago fire of 1871 also exposed regulatory gaps, both in building codes and fire preparedness.
Finance, time and again, also has seen regulatory gaps lead to fires. Such gaps can occur when financial regulations don’t treat like activities alike. Market participants may then arbitrage such differences here in the United States and between countries. Gaps also emerge when technologies provide new ways of intermediating, transforming, or creating risk and money. In these instances, regulators often fail to keep pace.
The SEC’s Role in Financial Stability
The SEC was established as a direct result of a financial fire. Congress gave us a mandate to protect investors and promote the public interest. In so doing, they understood we also had to oversee those intermediaries at the neck of the hourglass, such as stock exchanges, clearinghouses, broker-dealers, investment advisers, and transfer agents.
Congress enhanced our authorities in the wake of subsequent financial market fires, from government securities,[13] clearinghouses,[14] advisers to private funds,[15] auditing,[16] security-based swaps,[17] and credit rating agencies.[18]
Promoting financial resiliency goes to the core of the SEC’s three-part mission. It’s the essence of fair, orderly, and efficient markets. In normal times, it helps promote trust in capital markets. In times of stress, it protects investors and issuers alike.
Thus, given ever-changing technology and business models, I’m proud that the SEC has taken up a number of projects to enhance the resiliency of our capital markets.
Treasury Markets
First, in the spirit of building codes, let me start with the foundation of our entire capital markets—the $24 trillion Treasury markets. Over the decades, we’ve seen jitters in these markets, from the failures of a dozen government securities firms in the early 1980s to challenges in the 1990s to repo problems in 2019 and the dash for cash in 2020. Just this March, we saw the Treasury markets experience the greatest volatility in 35 years.[19]
Such jitters matter, as the Treasury markets are interconnected to the entire market. They are embedded in money market funds and the short-term funding markets and are integral to the implementation of monetary policy. They are how we as a people fund our government.
Further, many hedge funds are receiving the vast majority of their repo financing in the non-centrally cleared market.[20] This might create greater risk in times of stress, particularly when large, interconnected hedge funds achieve high leverage from banks and prime brokers in the Treasury markets.
Thus, working with the Department of the Treasury and the Federal Reserve System, the SEC has put forth a number of reforms in these markets. These projects include broadening central clearing, registering dealers, regulating trading platforms, and promoting greater transparency.[21]
Clearing
Second, speaking of central clearing, clearinghouses have helped lower risk in our markets since the 19th century. Given that they sit in the middle of the capital markets, though, it’s imperative that we continually look to update rules regarding clearing and clearinghouses themselves.
Thus, earlier this year, we finalized rules to cut in half the settlement cycle in securities markets.[22] We’ve proposed rules to strengthen clearinghouse governance and use of service providers.[23] This Wednesday, we’re considering proposals regarding the contents of a covered clearing agency’s recovery and wind-down plan.[24]
Private Funds
Third, given the fire of 2008 and earlier sparks at Long-Term Capital Management, Congress understood the importance of shining a brighter light of transparency on a significant and growing part of the nonbank market.[25] Private funds, now $25 trillion in gross assets,[26] surpass the $23 trillion U.S. banking sector.[27] Private funds participate in nearly every sector of our capital markets and are connected through the use of leverage provided by banks and broker-dealers.
Thus, we recently adopted rules requiring, for the first time, private fund advisers to make current reports of events that may indicate significant stress or otherwise signal for systemic risk and investor harm.[28] In addition, working with the Commodity Futures Trading Commission, we proposed enhanced periodic reporting for large hedge funds.[29]
Money Market Funds and Open-end Funds
Fourth, in times of stress, we’ve also seen financial stability sparks emanating from money market funds and open-end bond funds. In 2008, one money market fund “broke the buck.” If it weren’t for extraordinary fire department action—I mean federal government intervention—things could have gotten a lot worse. We saw related issues during the onset of the Covid-19 pandemic.
Money market funds and open-end bond funds, by their design, have a potential liquidity mismatch—between investors’ ability to redeem daily on the one hand, and funds’ securities that may have lower liquidity.[30] Thus, we’ve put out proposals intended to address these structural issues and enhance liquidity risk management for both money market and open-end funds.
Cyber
Fifth, nearly 40 years before that cow and the lantern, it may not surprise any of you that the first known cyber hack related to finance.[31]
Almost two hundred years later, the financial sector increasingly relies on complex, interconnected, and ever-evolving information systems. Those who seek to harm these systems have become more sophisticated as well: in their tactics, techniques, and procedures.
Thus, the Commission has made a number of proposals to enhance cybersecurity practices and incident reporting of financial sector market participants.[32]
Risks on the Horizon
Before I close, I want to address risk on the horizon, some in the near term, some possibly further out in the distance.
The economy is adjusting to a rise in interest rates more significant than in decades and ongoing geopolitical risk. With such a transition of inflation and rates, it’s appropriate to stay alert to financial stability issues. As the Federal Reserve’s recent Financial Stability Report noted, areas of concern include “vulnerabilities related to valuation pressures, borrowing by businesses and households, financial-sector leverage, and funding risks.” It also noted that “hedge fund leverage remained elevated.”[33]
Further, it might go without saying, but there would be quite a raging fire if the U.S. Treasury were to default on the debt.
Looking further out on the horizon, I would briefly note three things: moral hazard, the digital economy, and artificial intelligence.
There are tradeoffs of governmental interventions in the markets to forestall the spread of a financial fire. Moral hazard arises when official sector support in times of stress potentially incentivizes greater risk taking by individual actors in the private sector. Further, generally not all the costs to the economy of any individual market participant’s failure are borne by that particular participant. Thus, risk appetites and management may change in a way that’s adverse to financial stability.
As it relates to the rise of the digital economy—and I’m not talking about the generally noncompliant crypto markets—we’ve already seen the effects of fintech and social media on significant parts of consumer finance and investing. It’s possible, particularly in light of the higher rate environment, that we might see consequential changes to the deposit and banking landscape.
Looking further out, the use of predictive data analytics and artificial intelligence might be the most transformative technology of our time. This transformation is happening throughout our economy, and finance is no exception.
AI already is being used for call centers, account openings, compliance programs, trading algorithms, sentiment analysis, robo-advisers, and brokerage apps. Such applications can bring benefits in market access, efficiency, and returns.
It also has the potential to heighten financial fragility as it could increase herding, interconnectedness, and expose regulatory gaps.[34]
Existing financial sector regulatory regimes—built in an earlier era of data analytics technology—are likely to fall short in addressing the systemic risks posed by broad adoption of deep learning and generative AI in finance.[35]
Conclusion
Financial history tells us sparks will fly from time to time. One never knows when a cow may kick over a lantern or go rogue—or risk in one financial institution may burn through the system.
The SEC has an important role to help protect for financial stability and promote markets that are more resilient to fires.
This is why the SEC’s resiliency projects are so important. We are focused on strengthening the building codes of finance to better protect our clients, the American public.
00:02:09
Interested? Want to learn more about the community?
What else you may like…
Videos
Podcasts
Posts
Articles
Brad Garlinghouse at the Nasdaq closing bell for Evernorth 🔔
Times sure have changed from a few years ago.. 😉
00:00:43
🛡️ Perturb (SN26) plans a decentralized marketplace for AI security testing 🛡️
🛡️ Perturb (SN26) plans a decentralized marketplace for AI security testing 🛡️
Perturb’s Whitepaper 3.0 outlines a Bittensor subnet that rewards vulnerability discovery, adversarial testing, model hardening, and commercial AI-robustness services.
🔑 Key points
🔹 Scanning Track receives 80% of emissions: Miners create subtle image modifications that cause AI models to produce incorrect predictions.
🔹 Training Track receives 20%: Miners improve models so they can resist adversarial attacks.
🔹 New tasks arrive every 120 seconds: The network selects images from ImageNet-1k and distributes fresh testing challenges.
🔹 Validators check attack quality: Submissions are evaluated for prediction changes, image quality, perturbation limits, and authenticity.
🔹 Daily evaluations test trained models: Models are tested against clean images and attacks generated during the previous day.
🔹 Two commercial products are planned: Perturb is building an adversarial training dataset and model-robustness ...
00:00:10
Protect your frequency. ⚡️⚡️
🚨 BEWARE OF THOSE AROUND YOU!
😱❗️Did you know that when you meet people, there is a frequency balance between the two electromagnetic fields?
If you vibrate very high, and the person you meet vibrates very low, there is a frequency balance
(as you can see in the video)
The frequency that is very high will descend, and the frequency that is very low will rise to counter and balance the frequency.
That said, people steal your energy...
That's why you must be very careful with the people around you, because these fields carry their emotions, their thoughts, their traumas, their thoughts, and these fields transmit all this energy to you.. ( you can feel it )
These fields are the manifestation of their inner state.
People don't just enter your space,
they enter your field💫
Their energy, their emotions and their inner state, influence you more than most people realize..!
Protect your frequency. ⚡️⚡️
00:00:45
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.
🔑 Key points
🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.
🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.
🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.
🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.
🔑 Key points
🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.
🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.
🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...
👉 Coinbase just launched an AI agent for Crypto Trading
Custom AI assistants that print money in your sleep? 🔜
The future of Crypto x AI is about to go crazy.
👉 Here’s what you need to know:
💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit
👉 What this means for the future of Crypto:
1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025
🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.
The Future Of Energy, After An Energy Crisis 😉
Cold fusion didn’t end in 1989, but can it scale from lab experiments to megawatts?
Former Los Alamos nuclear chemist Dr. Edmund Storms explains why the evidence for LENR points to a radically different future for energy.
FULL INTERVIEW:
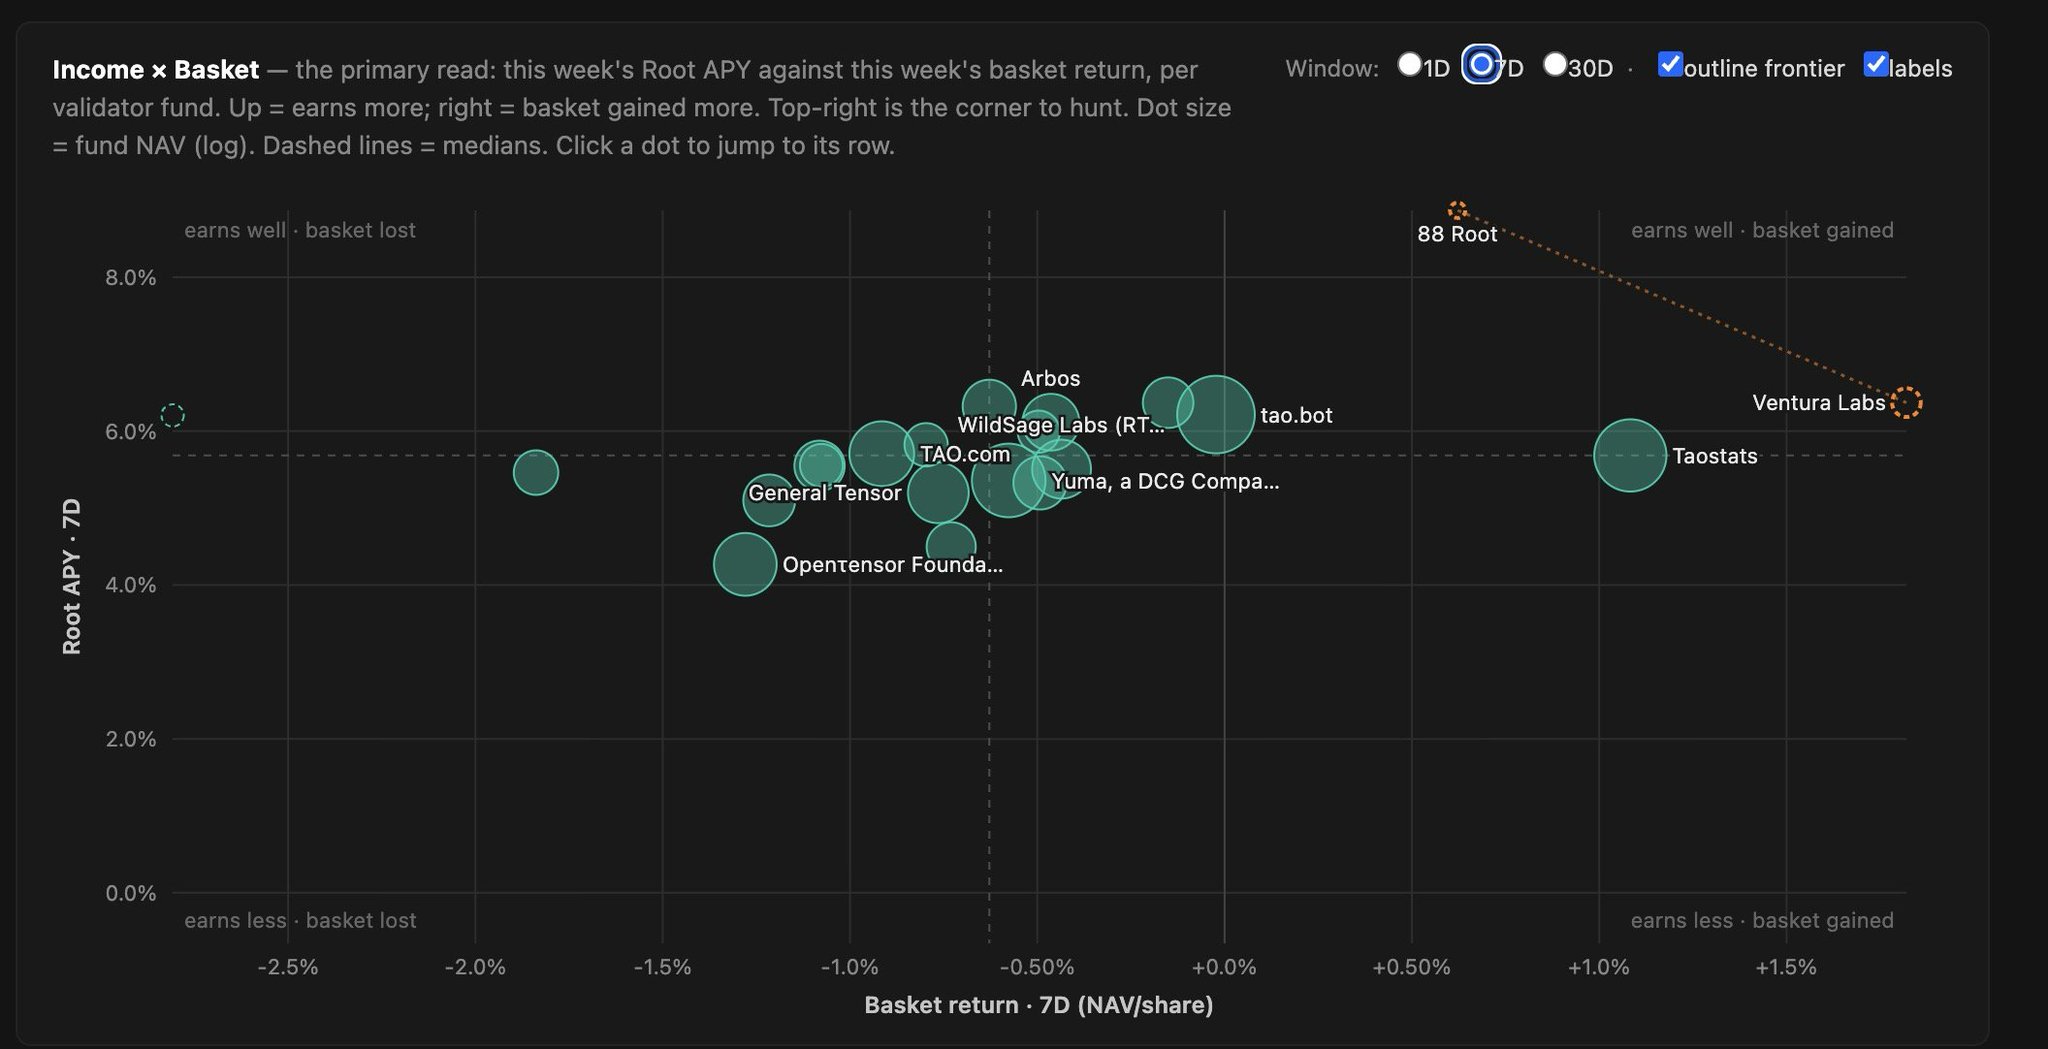
📊 Root Reborn makes validator performance visible across Bittensor 📊
Root Reborn has turned root staking into a transparent basket-performance system, allowing users to compare how each validator allocates stake across subnets and performs over time.
🔑 Key points
🔹 Each validator runs its own basket: Root stake is allocated across multiple subnet alpha tokens according to the validator’s weighting strategy.
🔹 Performance is public: Users can track how each basket performs through validator dashboards.
🔹 Taostats reports a 1.08% seven-day gain: Its basket reportedly remained in positive territory while most subnet alpha prices declined against TAO.
🔹 The comparison covers multiple validators: Taostats says its basket outperformed nearly every other validator during the reported period.
🔹 Strategy matters: Validator performance depends on how subnet weights are assigned and adjusted over time.
🔹 Long-term experience is emphasized: Taostats says years of tracking subnet development and...
🛢️ Global diesel shortage could last into 2027 as inventories drain 🛢️
Global diesel supplies are tightening as wars in Iran and Ukraine disrupt production and exports, while storage levels fall to historically low levels.
🔑 Key points
🔹 U.S. inventories hit a record seasonal low: Diesel stocks fell to 107.9 million barrels by September 11, the lowest for that time of year since records began in 1982.
🔹 Storage tanks are becoming available: North American and Caribbean diesel storage capacity available for lease rose to approximately 13 million barrels because traders have less fuel to store.
🔹 The shortage may last into 2027: Industry participants expect supplies to remain tight through winter and potentially into the first quarter of next year.
🔹 U.S. diesel prices topped $6 per gallon: Higher fuel costs are affecting farmers, truckers, waste-management companies, manufacturers, and consumers.
🔹 Europe is also under pressure: Diesel stocks in the Amsterdam-Rotterdam-Antwerp hub were ...
Revolut Leak Shows the Cost of Constant ID Collection

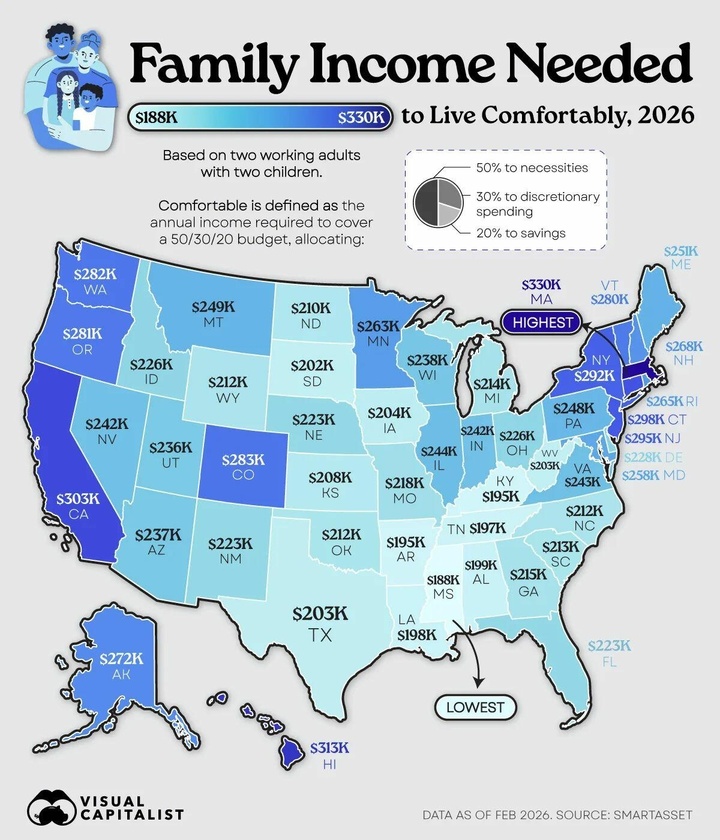
This Is The Income A Family Needs To Live Comfortably In Every US State
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:
In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.
So… how much does a family of four need in your state?
This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.
The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.
And as Visual Capitalist notes, Massachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.
Hawaii follows at $313,165, while California ranks third at $302,682.
Rank State Income needed for family of four (2026)
- 1 - Massachusetts - $329,555
- 2 - Hawaii - $313,165
- 3 - California - $302,682
- 4 - Connecticut - $298,189
- 5 - New Jersey - $295,110
- 6 - New York - $291,533
- 7 - Colorado - $283,213
- 8 - Washington - $281,798
- 9 - Oregon - $280,966
- 10 - Vermont - $280,384
- 11 - Alaska - $272,064
- 12 - New Hampshire - $267,904
- 13 - Rhode Island - $264,659
- 14 - Minnesota - $263,078
- 15 - Maryland - $257,837
- 16 - Maine - $250,931
- 17 - Montana - $249,434
- 18 - Pennsylvania - $247,936
- 19 - Illinois - $244,109
- 20 - Virginia - $242,944
- 21 - Nevada - $242,278
- 22 - Indiana - $241,696
- 23 - Wisconsin - $238,451
- 24 - Arizona - $236,870
- 25 - Utah - $235,789
- 26 - Delaware - $228,134
- 27 - Ohio - $226,221
- 28 - Idaho - $226,054
- 29 - Florida - $223,392
- 30 - New Mexico - $223,142
- 31 - Nebraska - $223,059
- 32 - Missouri - $217,734
- 33 - Georgia - $214,573
- 34 - Michigan - $214,323
- 35 - South Carolina - $212,909
- 36 - North Carolina - $212,410
- 37 - Wyoming - $212,410
- 38 - Oklahoma - $211,910
- 39 - North Dakota - $210,496
- 40 - Kansas - $207,917
- 41 - Iowa - $204,422
- 42 - Texas - $203,424
- 43 - West Virginia - $202,592
- 44 - South Dakota - $201,760
- 45 - Alabama - $198,931
- 46 - Louisiana - $197,933
- 47 - Tennessee - $197,267
- 48 - Arkansas - $195,437
- 49 - Kentucky - $194,854
- 50 - Mississippi - $187,533
Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.
Colorado and Vermont Make the Top 10
As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.
However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.
Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.
Just Six States Come in Below $200,000
Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.
Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.
The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

🙏To support my work, Helping to keep the signal high and the noise low:
👉 Cashapp: $thedinarian
👉 Buy me a coffee: https://buymeacoffee.com/thedinarian
👉 PayPal: Scan the QR code below 📲 or Click Here:
👇 Crypto Donations Always Welcome 👇
XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
Now that AI is moving into the physical world, many are asking a bigger question:
Will these same companies end up controlling robotics too?
It's a valid concern.
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
That movement is decentralized AI.
Why Decentralized AI Exists
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
Why This Matters for Robotics
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
This is where decentralized systems become interesting.
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
Imagine a future where:
- Warehouse robots contribute operational data.
- Delivery robots contribute navigation data.
- Factory robots contribute manipulation data.
- Developers contribute models.
- Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
That vision is beginning to emerge.
Bittensor's Move Toward Physical AI
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
In other words, the pieces are starting to appear.
Not a decentralized robot network yet.
But the infrastructure that could support one.
Beyond Bittensor: The Rise of Physical AI Networks
Bittensor isn't alone.
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
The goal is not simply decentralization for its own sake.
The goal is resilience.
If one server fails, the system continues.
If one company disappears, the network survives.
If one participant leaves, innovation continues.
But Here's the Reality
Decentralized AI faces the same challenge every decentralized technology faces.
Big Tech has resources. A lot of resources.
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
The challenge isn't just decentralizing intelligence.
It's decentralizing intelligence while maintaining performance.
That's much harder.
The Most Likely Outcome
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
The companies building robots may use NVIDIA hardware.
Train on Azure.
Run foundation models from OpenAI.
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
The Bigger Question
The real question isn't whether decentralized AI can eliminate Big Tech.
It can't.
At least not anytime soon.
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
Because the battle for the future of robotics is no longer about hardware.
It's about who owns the intelligence.
And that battle is just getting started.

🙏To support my work, Helping to keep the signal high and the noise low:
👉 Cashapp: $thedinarian
👉 Buy me a coffee: https://buymeacoffee.com/thedinarian
👉 PayPal: Scan the QR code below 📲 or Click Here:
👇 Crypto Donations 👇
XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6