Dinarian888
News • Business • Investing & Finance
Systemic Incentives
Why Stablecoins Matter to Financial Stability and Inclusion
September 06, 2023
post photo preview

Do you believe that, in order to make an electronic payment in the United States, first you should have to loan money at 0% to a venture capital firm, a billionaire real estate mogul, or a rich law partner looking to buy a second vacation home?

Most people would answer “no” to this question.

So if I told you that the answer to this question in the current American financial system is actually “yes”, how would you feel about that? What if I also told you the current rules mean you are not allowed to have another option, and you are trapped?


How Things Work Part 1: Banks, Simplified

The starting point for most payments in the United States is a bank account. While there are rare exceptions to that system, for the overwhelming majority of retail payments (and many corporate payments), the starting point is the humble checking account.

So what happens with that thing? From the perspective of the customer, it’s simple: you give money to your bank to put it in that account, it’s there, and when you need to pay bills or buy stuff, you spend it. How? Debit card, check, cash at an ATM, having your credit card paid off by the funds, etc. It’s all pretty simple. If you want to be simultaneously fancy and live in like 1948, you can send a wire.

Now, that is the customer perspective, so here is the more interesting question. What happens on the bank side when you deposit money into your checking account?

Banks receive deposits, and they become liabilities of the bank. This is important to understand, as it is very much not the case that the bank just keeps that money, set aside, segregated, as purely the property of the person who gave that to them. That is a custodian. The bank, more specifically, is taking your money and can do whatever they want with it. What do they pay you for that privilege?As of August, 2023, the national average is 0.42%.That is not a typo. In an environment where the Federal Funds target rate is 5.25%-5.5%, banks are paying through an average of 0.42% on your checking account, meaning even if they lend risk-free to the government, they are pocketing 5% for letting you give them money, and then giving you a tiny amount. If they lend that onwards to billionaires and venture capital firms, they keep even more of the spread, and still pay you the same amount.

So let us pause for a moment and ask a simple question: is that a fair price to be granted the privilege of being allowed to pay people for things?


How Things Work Part 2: When Things Break

If the story ended there, it would be a simple conversation about what the price of access should be. There are many viable answers to that question: zero, some small amount, or several percentage points of your money every year, such as in the current system. The story does not end there, however. Remember that part where you deposited money to the bank and they start doing things with it? Those things typically involve taking credit risk to people they have lent money to, and also taking duration risk to the term of those loans if rates rise. Let us just say that banks have a history of getting themselves into trouble with those kinds of risks, to put it gently.

This means that, for the average person, you are putting money into a black box, and then praying the box does not explode and you lose all your money. We have the FDIC in the United States precisely because of this problem, but that covers you up to $250k. More than enough for a small individual account, but what about a regular business just taking payments? Is that enough for, say, a grocery store? How about a Best Buy location? Do we really expect Wal-Mart to have 54,182 bank accounts just to avoid credit risk? At that point, Wal-Mart should literally just start their own bank (some companies have done this!). In short, once you incorporate credit risk, now you are essentially both paying a huge subsidy to rich borrowers who are the borrowing from a bank and essentially selling the bank CDS protection for free on all funds over $250k, just to be allowed to use the payments system. Yikes.


How Things Work Part 3: Timing and Tracking

Another problem with the current banking system is that it is (unnecessarily) slow.

Electronic signals move very quickly, yet somehow wiring money around the world takes 4+ days and is subject to the whims of banks and completely non-transparent. If you send money from the United States to a relative in Hong Kong, what is the pathway the money takes to get there?

You don’t know, do you?

This is completely unnecessary. Many of these delays are due to regulatory compliance, but many of them are also simply due to oligopoly power of banks and delaying things so they can make extra money on the friction.

What this does do is create a web of confusion and opacity for the average user. Sending money to a relative overseas (or even just at another domestic bank!) currently means you are going to not exactly know where your money is for an unclear amount of time with no real understanding of if/how/when errors occur. Also, you’re not earning any interest (not that most banks are paying you anyways) on that money while it is in flight.

Does this seem fair?


What is a Stablecoin?

For those who have read my work elsewhere, we are going to come back to a familiar definition that I have used repeatedly.

A Stablecoin is a unit of fiat currency represented on a blockchain.

For such a simple statement, there is a lot that is said. Ignoring the issues of designing a stablecoin properly for now, let us just simply say this is a US dollar stablecoin backed only with transparently disclosed reserves of very short dated t-bills. That’s something that almost everyone (banking regulators, the SEC, FASB, etc.) agrees trades at $1. So what happens when that thing exists?

First, it removes the problem of subsidizing risky borrowers. Depending on the design of the stablecoin, and whether it is interest paying or not, you may be subsidizing the government. However, what you are not doing is lending that money to the usual suspects that banks lend it to. Lending solely to the US Treasury, while still perhaps something that could end badly, is at least within the realm of basic expectations for holding money. People will not be surprised when their US dollar stablecoin is impacted if there are stability problems for the dollar itself.

Second, it removes the black box problem of bank solvency. In addition to not subsidizing risky borrowers, now you are not also staring at a horrible black box that contains a mix of mortgage lending, corporate lending, underwriting and issuance, prop trading, asset management, prime brokerage, and who knows what else just to use the payments system. A very vanilla, narrowly designed stablecoin means solvency comes down to two simple factors: one, is the stablecoin company run by idiots who make catastrophic operational errors (no escaping this one for any company) and two, is the US government itself solvent? This, I might suggest, is at least something you can try to reasonably assess from the outside. If your stablecoin holds reserves bankruptcy remote, even the first issue isn’t fatal to you, just annoying.

Third, you have solved the transfer problem. Sending money on a blockchain is near instantaneous. In fact, it’s downright miraculous compared to the four day journey of my friend Omid’s international wire. Similarly, it’s quite cheap, if you use the right chains. This means that you know where your money is up until the point that it vanishes from your wallet and appears in that of the recipient, at which case you can see it has been delivered. You know what this doesn’t allow for? Four days of delays, games, and correspondents fighting with each other at your expense to scrape basis points of interest.

So we’ve gone from subsidizing billionaires building commercial real-estate, expecting plumbers, nurses, schoolteachers, and grocery store chains to perform their own due diligence on global megabanks to ensure their funds are safe, and allowing intermediaries to deliberately gum up the system or just refuse to innovate to delay payments for their own benefit and/or laziness, to a system that is instant, transparent, and puts people in control of their own money.

Is it any wonder that the entire financial system fucking hates it?


Competition

There is nothing that incumbents with special privileges hate more than fair competition. Certainly, this is part of the hysterical reaction to blockchain technology and the driver of banks and certain bank advocates and regulators to the innovation. From the perspective of banks, this is an existential threat to their business: zero cost, instant transactions without the need for an intermediary would wipe out entire (very profitable, because they have a monopoly of economic force) business lines. More so, it would have a fundamental impact on the profitability of the entire industry. Multi-million dollar bonuses are at stake, you see. In short, stablecoins represent a full front assault on the traditional arrangement that even something like the Narrow Bank could not quite achieve, because it did not have the connection to a blockchain and the many-to-many payments network attached. At the core, this represents a complete re-negotiation of the financial structure of our payment system. A system based on stablecoins of this sort means:

  1. Users of the payment system do not subsidize borrowers implicitly

  2. Users of the payment system do not have to understand or try to evaluate black-box complex financial entities just to make electronic payments

  3. Legacy payments systems built on intermediaries and delays cease to exist

Is this not a strictly better system for the average user?

Yes, large borrowers will pay higher costs for debt (is this bad?). Yes, many large banks will become significantly less profitable (is this bad?). However, the average person takes less credit risk, has more control of their funds, and can send their money when they want, to who they want, for virtually zero. More so, customers of this sort are much cheaper to deal with. The entire cost burden of banks is virtually gone with regard to payments. Now, anyone who can create an electronic wallet and deposit funds is formally part of the system. From a financial inclusion perspective, you don’t have to worry about their credit, you don’t have to worry about compliance to the same degree. The entire cost structure is, well, deconstructed.

What does this mean? The kinds of customers that are unprofitable and get terrible service or worse, no service at all from banks? Now they can also be fully integrated into the system.

I suggest this is important.


Time Ends All Monopolies
This progress is inexorable. Forty years from now, we will not be transacting with an opaque, highly centralized, extremely expensive system when the technology and economic incentives to do better exist. However, one prediction I will make is that the places that will embrace this first are actually the ones who are the furthest behind now. Just like Africa, in many cases, went straight to mobile phones and skipped the landline, payments systems will likely evolve in areas with rickety or poorly run financial systems first.

Yes, the marginal benefit of this system in the United States is real, but it’s marginal. This benefit in Argentina, where you could get on a global, fast, secure, peer to peer omni-ledger and use dollars to avoid the local inflation of 100% per annum that has been running for decades? I’m no rocket scientist, but that seems pretty compelling.

Once that happens, then technology will begin to bleed backwards. If you trade with people who are doing that, why stay on the old system? It begins to flow downstream to the places that were slower to adopt. Right now, most Western nations face the nation-state equivalent of the innovator’s dilemma with regard to this, so they may very well go last. Just like the disrupted companies often move last and get run over as a result.

But it will happen, eventually.

The question is just if someone else will go first, and seize an outsized share of the economic pie as a result.

Link

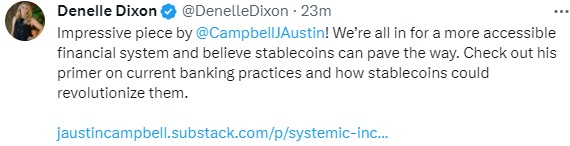
Brought to us Courtesy of Dinelle Dixon from The Stellar Foundation:
community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
RFK Jr: "The Pandemics are coming from labs. ALL OF THEM... Lyme, COVID, RSV, HIV & Spanish Flu came out of a vaccine lab." ☠️ 💉

"Gain-of-Function Vaccine research has created the worst plagues in our history."

"We can go down the whole list of diseases... It’s just a disaster. It’s given us no benefits. It’s given us everything from Lyme disease to Covid, and many many other diseases. RSV, which is now one of the biggest killers of children, came out of a vaccine lab."

"There’s strong evidence that even Spanish flu came from vaccine research."

"There’s plenty of evidence that HIV also came from a vaccine gain-of-function lab program. "

"The 'PANDEMICS' are coming from labs... ALL OF THEM."

00:04:00
🚀The industry has gotten incredible at teaching robots

🚀The industry has gotten incredible at teaching robots to move, sprint, and imitate body dynamics. But as Michael Parker (@bittensormax) points out in The UMI Thesis, there’s still a massive missing piece in Physical AI: Motion Understanding.

✨ Key Takeaways:

🔹Looking Human vs. Understanding Humans: Robots can execute impressive physical feats, but they still struggle to reliably read non-verbal human cues in context.

🔹Motion is Meaning: A gesture, hesitation, or glance changes completely depending on posture, timing, and surrounding context.

🔹Beyond Pixels: True intelligence requires mapping human intent and sequence across time—not just processing raw frames.

🔹The UMI Intelligence Layer: As robots enter hospitals, factories, homes, and stores, Bittensor’s SN78 @umi_sn78 UMI (Universal Motion Intelligence) aims to own the critical layer that translates human movement into real meaning.

The future of robotics isn't just about how machines move—it's about how ...

00:04:54
Follow The Money🎯

Israel Exposed launched 🤯Who Funded The Genocide🤯

A searchable database tracking pro-Israel political money in U.S. politics.

It includes:

👉 11,168 named donors + employers

👉 523 members of Congress + funding

👉 House & Senate votes on arms-transfer resolutions

👉165 candidates with network-backed fundraising pages

👉105 recipient committees linked to FEC filings

00:01:36
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading

The future of cybersecurity isn't about blocking yesterday's threats—it's about defeating tomorrow's before they are even built. 🛡️⚡

​The ultimate competitive edge belongs to defenders who can instantly ingest unique zero-days, automatically generate the attack strains that don't exist yet, and ship bulletproof detections to the front lines ahead of the breach. 🔮🚀

​As legacy security platforms degrade under the weight of novel AI-driven threats, the world’s largest financial institutions won't scatter their bets. They will consolidate on the single provider capable of delivering this predictive defense at global scale. 🏦📊

​The Engine Behind the Defense:

​To stay ahead, that provider needs a constant, unrelenting supply of edge-case attacks. A decentralized subnet is the only architecture built to fuel this machine—paying a global swarm of attackers to continuously probe, create, and supply novel threats around the clock. 🌐🐝💥

​Self-evolving security is ...

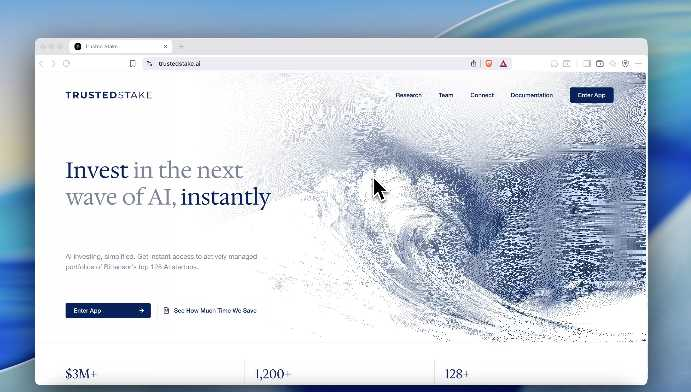
🚀 Navigating Bittensor yield just got effortless! 🧠⚡️

If you’ve been looking to optimize your $TAO positions across subnets without the headache of manual rebalancing or technical friction, @TrustedStake is changing the game! 💎

The new Quickstart Guide breaks down how to get seamless exposure to top-tier AI strategies:

🎯 One-Click Index Exposure: Access curated subnet baskets (Universe, Top 15, and specialized sectors) in seconds.

🛡 Non-Custodial Security: Retain complete asset control while leveraging Substrate proxy accounts—keeping your primary stash safe in cold storage.

🔄 Automated Rebalancing & Yield Optimization: Smart TWAP execution, validator selection, and root reinvestment handle the heavy lifting to maximize your alpha.
📈 Block-Level Transparency: Real-time PnL metrics and full on-chain visibility right from your dashboard.

👇Check out the full walkthrough to get started👇
...

post photo preview

🎯 Leadpoet’s new Arena could change how businesses find their next customers 🎯

Leadpoet is launching an Arena where AI agents compete to identify companies most likely to buy, turning sales intelligence into a measurable performance competition.

🔑 Key points

🔹 Agents compete on lead quality: Systems are evaluated on whether the prospects they identify show genuine buying intent.

🔹 Better than list generation: The goal is to find likely customers rather than produce large volumes of low-quality contacts.

🔹 Real-world signals matter: Agents can analyze company activity, business changes, hiring, technology use, market behavior, and other indicators.

🔹 Performance becomes measurable: Agents can be ranked based on precision, relevance, conversion potential, and downstream sales outcomes.

🔹 Competition can improve intelligence: Different agents may identify different signals, creating a wider search across potential customers.

🔹 Sales teams gain prioritization: Businesses ...

post photo preview
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
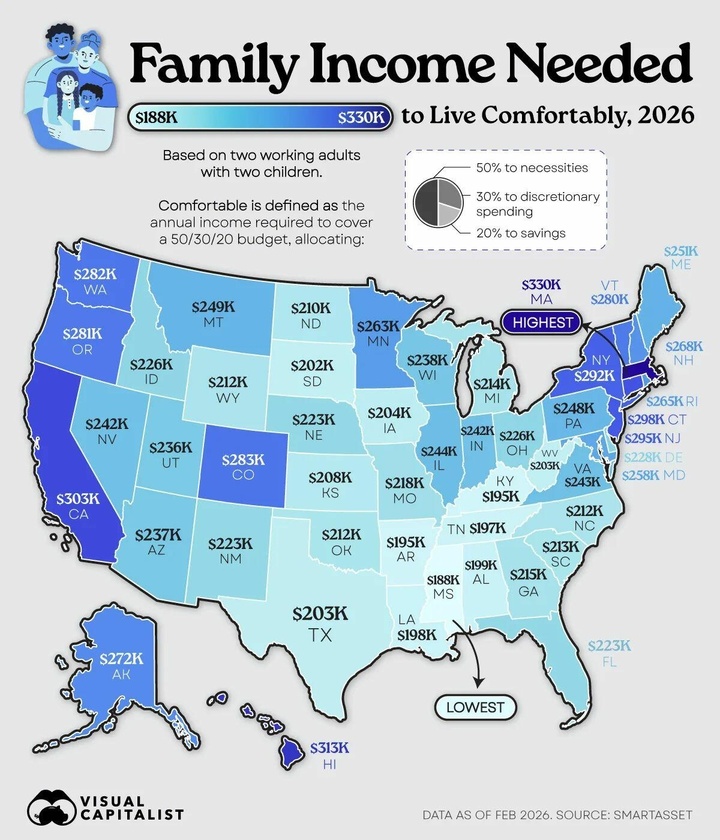
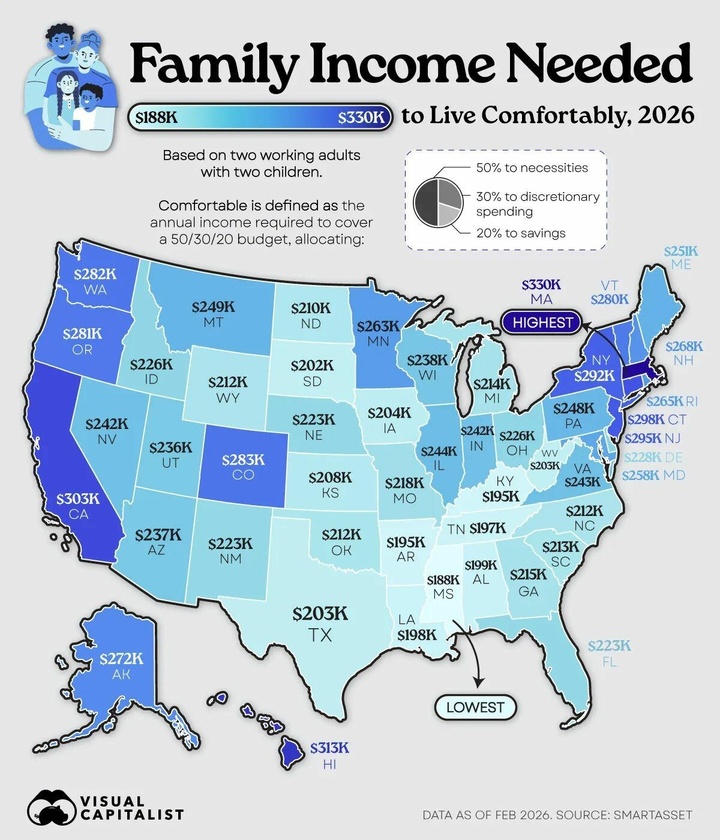
This Is The Income A Family Needs To Live Comfortably In Every US State

Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notesMassachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals