Dinarian888
News • Business • Investing & Finance
What Is PayFi? The Future Of Payments With Tokenized RWAs And On-Chain Credit
February 13, 2025
post photo preview

What Is Payment Finance (PayFi)? 

Payfi, or Payment Finance, is a broad term that generally refers to the intersection of financing payments and decentralized finance (DeFi). It leverages blockchain to offer faster, more efficient, and potentially cheaper financial transactions to unlock the time value of money.


Key Takeaways

  • PayFi focuses on real-time settlement and bridging DeFi with real-world assets (RWAs), addressing the limitations of both ecosystems.

  • PayFi enables users to unlock TVM (Time Value of Money) through decentralized finance, offering instant access to future cash flows for reinvestment.

  • Solana supports PayFi with high performance (400ms block times), deep liquidity, and a growing developer community.

  • PayFi use cases include accounts receivable financing, creator monetization, and "Buy Now Pay Never" models that leverage interest for payments.

Satoshi Nakamoto's whitepaper introduces Bitcoin as peer-to-peer (P2P) electronic cash for online payments among peers without third-party intervention. Fast-forward 15 years, Bitcoin is still not widely used as a digital payment medium for daily activities. 

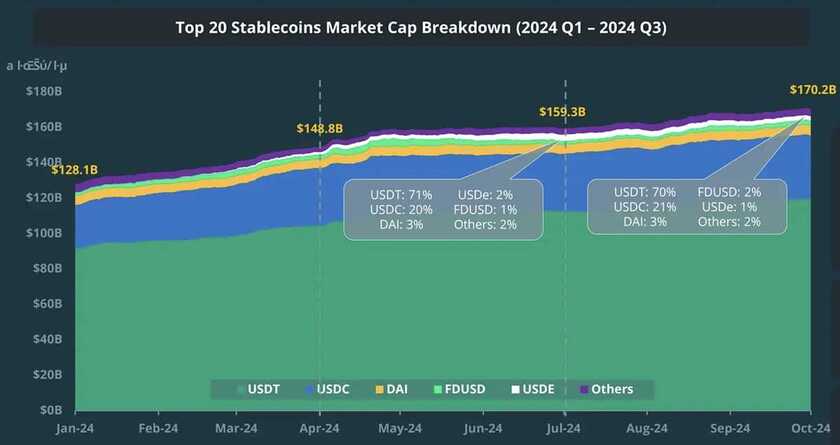
Instead, stablecoins’ popularity seemed to have found a better product-market fit (compared to L1 tokens like BTC) for settlements, and since 2020, they’ve grown to a market cap of over $170 billion (as of October 2024).
For instance, stablecoins’ transaction volume is more than double that of Visa’s in the second quarter of 2024, according to a report by Andreessen Horowitz.
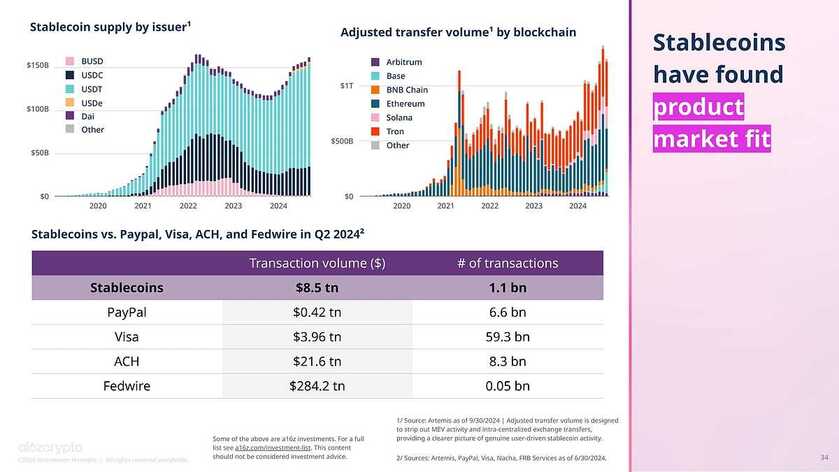
However, while stablecoins have facilitated everyday transactions, they haven't fully bridged the gap between traditional finance and the decentralized world. More importantly, they have not addressed the challenge of realizing the time value of money.

This is where Payfi comes in.

PayFi's solutions aim to make real-world financial transactions more efficient through innovations in cross-border payment financing and instant settlement for real-world assets (RWAs).

Understanding PayFi: DeFi Meets Payments Financing 

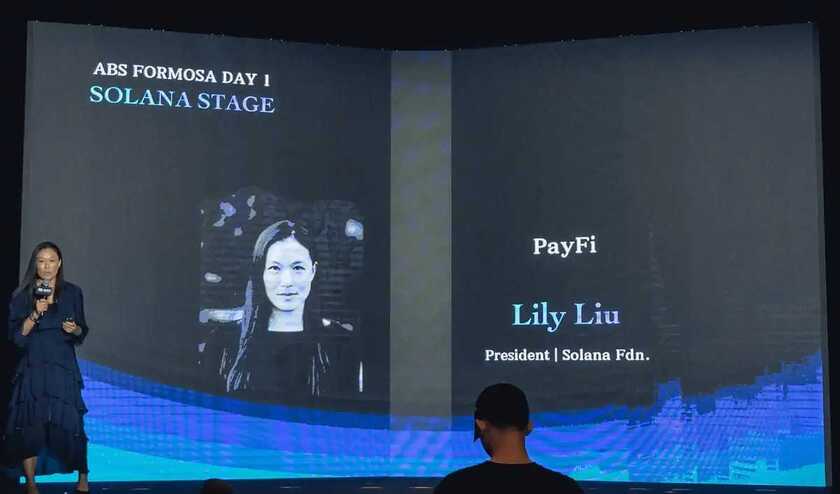
Lily Liu, President of the Solana Foundation, is credited with coining the term PayFi, which she describes as the creation of new financial markets centered on the time value of money. Liu asserts that on-chain finance can unlock innovative financial products and experiences that are not possible in traditional or web2 finance.
While DeFi provides a vast array of financial services, think staking, lending, and more, PayFi's primary focus is on real-time settlement to help individuals and businesses access and utilize the time value of money more efficiently.

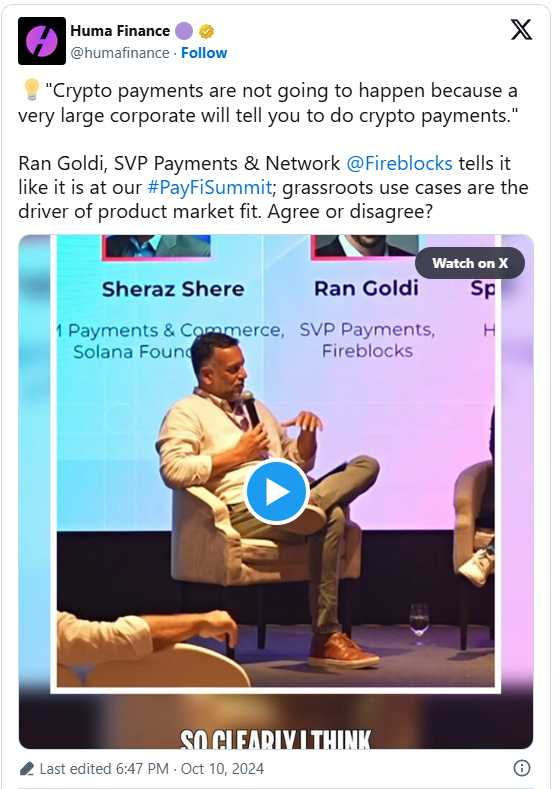
Also mentioned in Messari's "The Crypto Theses 2025" report, PayFi helps to bridge two highly potential ecosystems, RWA and DeFi, by tackling their major challenges. RWAs’ illiquidity, despite its massive value and DeFi's detachment from the real econhttps://x.com/humafinance/status/1844510148082929797omy, can potentially be addressed with the efficient implementation of PayFi solutions.
Time Value of Money (TVM): PayFi's Core Concept from The Financial Industry 

Time Value of Money (TVM) is a fundamental financial concept that emphasizes the idea that a dollar's value today is greater than its value in the future. This concept is relevant in today's world because money invested now has the potential to generate higher returns compared to money received at a later time, as its value decreases over time due to inflation.
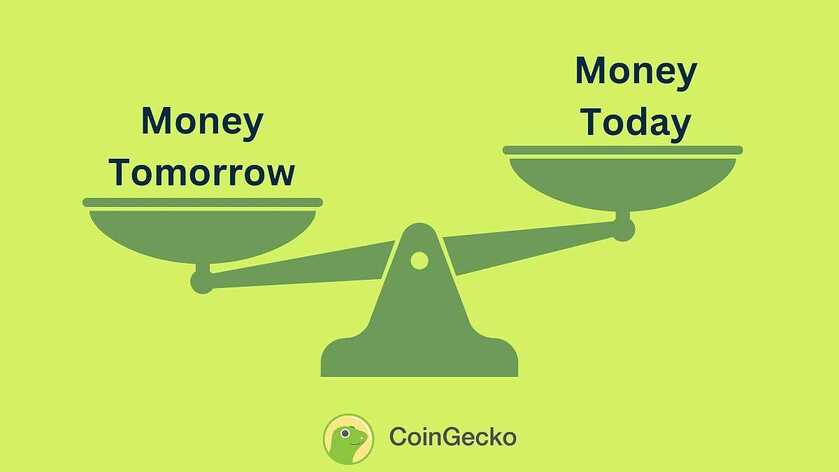
For example, suppose a person won a prize of $100,000 and needs to choose between receiving the full amount today or receiving it in equal monthly installments over the next five years. According to the TVM principle, taking the lump sum today would likely be more beneficial than opting for a monthly passive income, as the money can be invested immediately to generate returns, whereas the future installments would lose purchasing power due to inflation.

PayFi uses blockchain’s ability to be borderless to help users realize TVM via decentralized money markets. Besides reducing transaction costs, users can benefit from faster transaction times to reinvest their money or assets effectively.

Solana With PayFi: Transforming Global Financial Markets 

According to Solana Foundation President Lily Liu, there are three key requirements for a blockchain for PayFi-based applications to flourish on the network:

  • High performance

  • Large capital liquidity

  • Ample talent liquidity

1. Performance 

Near-instant settlements and T+0 cross-border transaction times are some of the biggest USPs of PayFi. To achieve such performance, a fast and reliable blockchain infrastructure is paramount.

Through Proof of History (PoH), Solana achieves block times of 400 milliseconds, allowing it to process (theoretically) over 100,000 transactions per second (TPS).
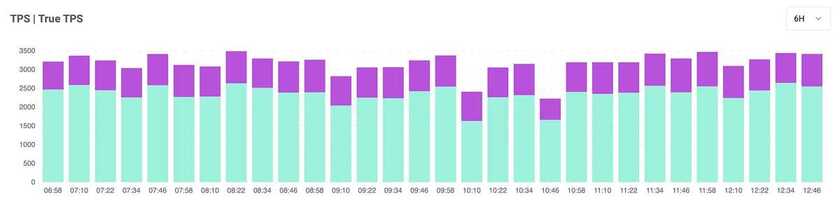
Along with this performance, the transaction fee of below $0.01 makes the blockchain more attractive for users and projects to try their hands on PayFi.

2. Capital Liquidity 

The availability of highly liquid capital is crucial for smooth operation, including real-time transactions, which the Solana ecosystem effectively provides. Solana has a total value locked (TVL) above $6 billion, ensuring ample liquidity for PayFi transactions.
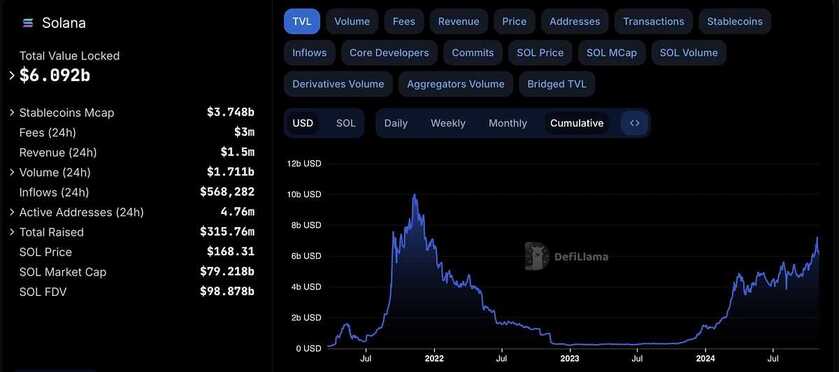
USD Coin (USDC), the largest stablecoin on Solana, with a market cap of close to $2.5 billion, makes it a key pillar in maintaining liquidity and helping PayFi networks like Huma facilitate on-demand, cross-border lending, and remittances.

3. Talent Liquidity

A strong developer community is essential for building PayFi for a larger number of crypto users. Solana has a growing number of monthly active developers in the crypto ecosystem. To emphasize,  the number of total monthly active Solana developers rose from 244 in April 2020 to more than 3,300 in April 2024.  
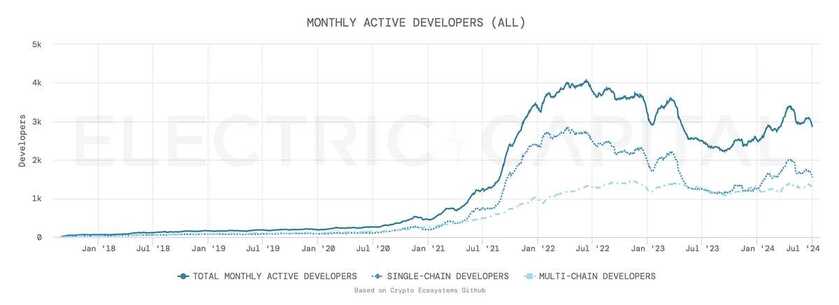
Considering these, Solana is a suitable blockchain for practical PayFi use cases. The chain is capable of combining the best performance with low fees, capital liquidity, and an active developer community.

Potential Applications Of PayFi

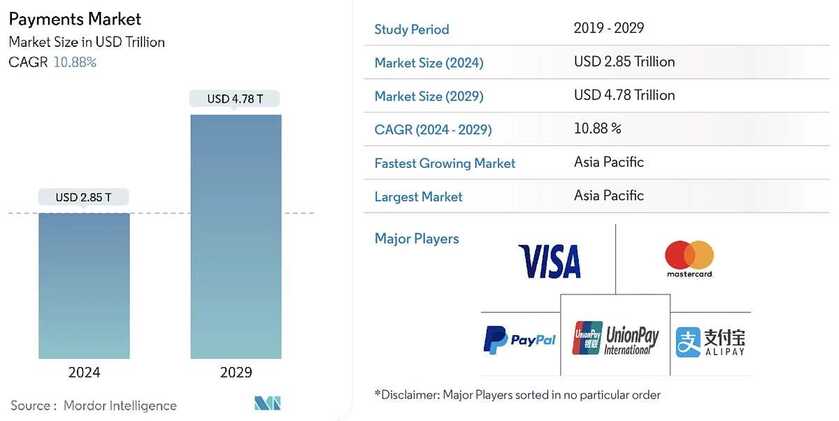
According to Mordor Intelligence, the global payment financing market is expected to reach $2.85 trillion in 2024 and grow to $4.78 trillion by 2029. The Asia Pacific region is expected to grow the fastest during this period and account for the largest market share.

This immense growth highlights the critical need for efficient, scalable, and accessible financial infrastructure — exactly what PayFi aims to deliver.

Here are some potential applications of PayFi that can reshape the future of finance.
Buy Now Pay Never

Buy Now Pay Never allows users to benefit from the time value of money principle, where users can buy a product or service without the need to pay for it later. In this case, the user deposits an adequate amount of funds to PayFi-supported products and uses its interest as a payment method.

Imagine you want to buy a new phone that costs $1,000. Instead of paying upfront or taking out a traditional loan, you could use a PayFi platform to commit a portion of your future earnings toward the purchase. Let's say you agree to pay $100 per month from your salary.

Here's where yield-bearing stablecoins come in. These stablecoins generate interest while they are held. The PayFi platform could use your committed $100 monthly payments to purchase these stablecoins. These stablecoins are then locked into a smart contract that automatically generates yield. Over time, the accumulated interest and principal from the yield-bearing stablecoins will eventually cover the cost of the phone.

Once the total amount reaches $1,000, the smart contract automatically executes the final payment to the seller, and you officially own the phone without ever having to make a lump-sum payment.

Account Receivable

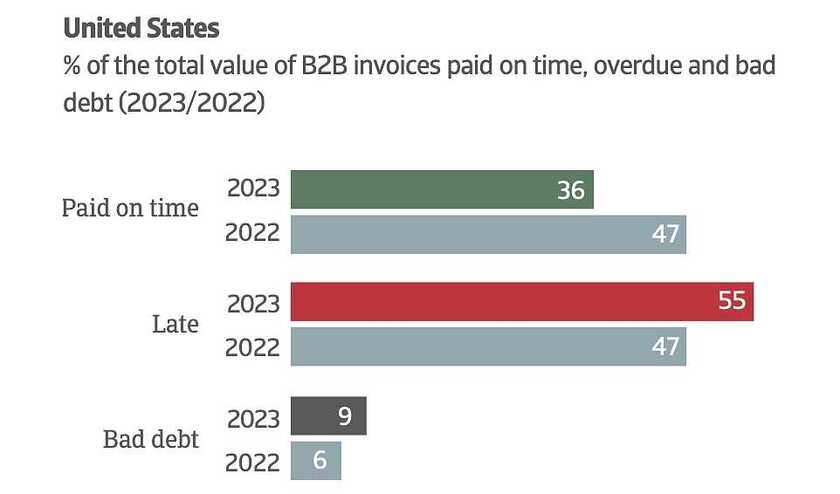
Accounts receivable financing bothers the majority of businesses without surplus funding or financial institutions' backup, which might even lead to operational failures due to a lack of money. According to the Atradius report, 55% of businesses in the US receive late invoice payments, and 9% face bad debt.
To address this issue, PayFi introduces a decentralized and automated approach to accounts receivable financing. Traditional invoice financing relies heavily on intermediaries such as banks or financial institutions, causing delays, added fees, and restrictive credit evaluations. With PayFi, businesses can access instant liquidity by tokenizing their invoices or receivables and using them as collateral on blockchain-based platforms.

The availability of faster funds helps businesses maintain a safety cushion, allowing them to have a runway fund for unexpected expenses or to expand their growth opportunities without the constraints of delayed payments.

Creator Monetization

The creator economy is on a rapid upsurge with the global market size expected to surpass $500 billion by 2030. However, even on popular platforms, creators have to wait weeks to earn revenue for their latest videos. 

In this scenario, PayFi can help content creators finance their video production by providing funds beforehand to create the complete video, which they can return automatically based on the return generated from streaming revenue.

This PayFi service allows creators, especially micro-influencers, to continuously deliver videos without waiting until their next pay.

Notable Players In PayFi Space

As slow remittances and settlement times continue to slow down commerce, many teams are coming together to tackle the challenges head-on.

Here, we will look at three notable projects in the PayFi ecosystem:

  1. Huma Finance

  2. PolyFlow

  3. TLay

1. Huma Finance

Huma Finance is an innovative platform focusing on bridging DeFi with real-world financial applications, particularly through income-backed lending and payment financing solutions.

The project positions itself as a pioneer in the Payment Finance (PayFi) space, using blockchain’s capabilities to offer real-time, borderless liquidity for businesses and individuals.

Huma Finance provides an on-chain factoring market, allowing businesses to borrow against future income or invoices. This solution helps companies with cash flow challenges, offering immediate liquidity by transforming receivables into digital assets on the blockchain.

The platform's integration with networks like Circle, Superfluid, and Request Network showcases its focus on making decentralized invoice financing accessible and efficient for various stakeholders​.

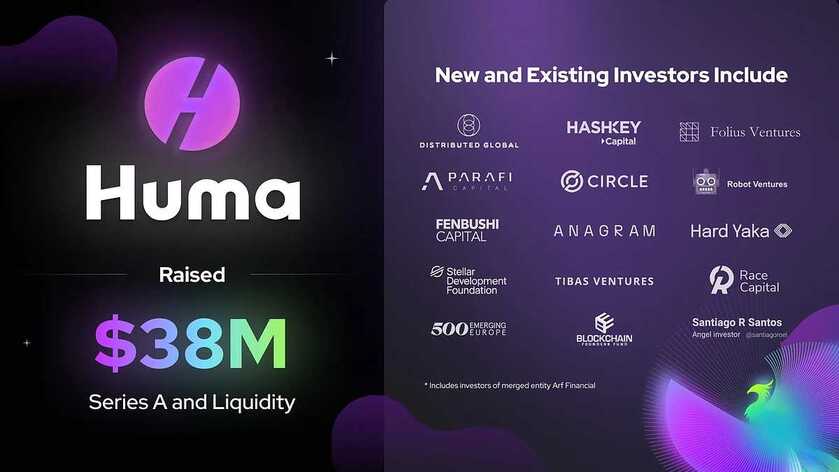
With recent funding of $38 million and a partnership with Arf to expand liquidity offerings, Huma is growing its PayFi network across blockchains like Stellar and Solana. Its approach enables faster settlements and makes financial services more accessible by moving away from asset-based lending towards cash-flow-based underwriting.

Core Focus

  • PayFi: Huma is a pioneer in the PayFi space, aiming to bring traditional payment financing processes onto the blockchain. This includes invoice financing, supply chain financing, and more.   

  • Global lending: They facilitate cross-border lending and borrowing, making it easier for businesses and individuals to access capital regardless of location.   

  • Real-world assets (RWAs): Huma is working to connect real-world assets to the blockchain, enabling new financing opportunities and unlocking liquidity for previously illiquid assets.

2. PolyFlow
PolyFlow is a blockchain-based infrastructure designed to improve the Payment Finance (PayFi) ecosystem by integrating DeFi with real-world payments and assets. Its primary goal is to address the limitations of traditional and blockchain-based payments by improving compliance, scalability, and transparency.

PolyFlow introduces two key elements:

  1. Payment ID (PID): This decentralized ID system securely manages transaction flows, protecting user privacy through zero-knowledge proofs while ensuring regulatory compliance. PID functions similarly to a digital wallet, containing various elements like payment methods, digital identities, or NFTs, enhancing cross-functional use.

  2. Payment Liquidity Pool (PLP): This component facilitates the secure and efficient movement of funds without relying on centralized institutions. Using smart contracts, PLP automates fund flows, reducing settlement risks and enhancing capital utilization for both TradFi and DeFi systems.

PolyFlow is working to create a unified financial infrastructure by decoupling the information and fund flows, which were traditionally managed by centralized systems. This modular framework ensures compliance with regulatory requirements and mitigates custodial risks.

The project is already collaborating with partners like OKX Wallet and exploring innovative use cases like “Scan to Earn”.

Core Focus

  • PayFi infrastructure: PolyFlow is developing basic infrastructure for the PayFi ecosystem. They're focused on bridging the gap between traditional payment systems and decentralized finance (DeFi).   

  • Regulatory compliance: A key aspect of their approach is ensuring regulatory compliance. They aim to build a system that meets regulatory requirements while still making the best of what blockchain has to offer.

  • Security and efficiency: PolyFlow prioritizes security and efficiency in its design to support net settlements and micropayments on blockchain networks, reflecting Bitcoin’s original vision.

3. TLay
TLay (Trust Layer for DePIN) is a decentralized infrastructure layer designed for Decentralized Physical Infrastructure Networks (DePIN). Its goal is to bridge the physical and digital worlds by offering modular tools that facilitate large-scale collaboration among machines and devices, and enabling the management of RWAs through blockchain-based solutions.

TLay integrates various technologies, including trusted chipsets, IoT oracle services, and DePIN-specific appchains. This structure simplifies the development process for projects in the DePIN ecosystem by providing ready-to-use frameworks and tools for bootstrapping new applications. Developers can use these components to quickly launch innovative distributed digital finance and business solutions.

One of TLay’s main objectives is to ensure data authenticity, privacy, and transparency. For example, its BoAT3 IoT Oracle Service authenticates data from physical devices directly onto the blockchain, preventing data manipulation while supporting privacy. This setup is crucial for creating trust within DePIN ecosystems, where accurate real-time data feeds are necessary.

In collaboration with partners like Huma Finance, TLay also plays a role in PayFi (Payment Finance) innovations by ensuring trust and data security. This partnership allows PayFi systems to leverage trusted on-chain data to provide credit and real-time lending solutions, helping drive the development of machine-based economies where automated payments and financing are key drivers of growth.

Core Focus

  • DePIN infrastructure: TLay focuses on decentralized physical infrastructure networks, which include things like wireless networks, renewable energy grids, and sensor networks.

  • Digital twin technology: They create digital representations (or "digital twins") of physical assets on the blockchain. This allows for secure and transparent tracking, management, and monetization of these assets.

  • Data integrity: TLay ensures the integrity of data coming from physical assets using cryptographic proofs and decentralized consensus mechanisms. This is crucial for building trust and reliability in DePIN networks.

Conclusion

Payment Finance (PayFi) changes the way payments are conducted in the financial space, including traditional decentralized finance. With the proper implementation of PayFi solutions, users can access future capital “now” and finance their other interests.

We're still in the early stages of the PayFi revolution, but the potential is enormous. By connecting RWAs, automating payments, and merging DeFi with TradFi, PayFi is transforming the financial landscape.

Further, with events like the 2024 PayFi Summit, co-hosted by Solana, the word is spreading rapidly and community growth is accelerating. Given the nature of the technology, PayFi applications will very quickly go beyond the virtual world and impact the real-world economy.
 

Link


community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
September 26, 2026
The true enemy of peace is NOT Russia, China, or Iran…

“The Rothschilds claim to be Jewish, but are actually Khazars from Mongolian Eastern Europe…”

The true enemy of peace is the Rothschild-Khazarian Mafia!

Forbidden Knowledge 📚

00:02:55
September 26, 2026
Just as Guns Don't Kill People...

🚨 BIG NEWS: Speaking to a packed room of over 1,000 attendees at ETH Zurich, Edward Snowden called for Sam Altman to face IMPRISONMENT to establish legal liability for harms caused by OpenAI's models—drawing massive, thunderous applause! 👏💥

Time to cut through the corporate "safetyism" PR distraction 🎭 and demand true accountability. Lock him up! 🔒🏛️

00:03:45
September 26, 2026
🚨 BREAKING: BlackRock lays off 600 employees, hitting the ESG division hardest. 📉💼

The global collapse of ESG is accelerating:

💸 $5 Trillion Lost: Global ESG investments have plummeted by $5 trillion in just 2 years as investors pull back.

⚖️ The Mechanism of Control: ESG has been used by massive institutional asset managers like BlackRock and Vanguard as a leverage system to force corporate alignment with social and political agendas.

🗣️ In Their Own Words: Watch BlackRock CEO Larry Fink (seated alongside the CEO of AmEx) explicitly explain how ESG metrics are deployed to "force behaviors" across the corporate landscape.

The narrative is crumbling, and the markets are responding in real time 🛑📉

00:00:29
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading

🏦 Quant partners with The Clearing House on tokenized-deposit infrastructure 🏦

Quant has been selected as the technology partner for The Clearing House’s On-Chain Money Initiative, a project backed by major U.S. banks to develop interoperable tokenized-deposit settlement.

🔑 Key points

🔹 25 major banks are involved: The initiative reportedly includes institutions such as Bank of America, Citi, JPMorgan, Wells Fargo, HSBC, BNY, PNC, U.S. Bank, and Truist.

🔹 Quant provides interoperability infrastructure: Its technology is designed to connect tokenized deposits across banks, blockchains, and existing payment systems.

🔹 RTP and CHIPS will be connected: The project is intended to link blockchain-based settlement with The Clearing House’s existing real-time and large-value payment networks.

🔹 Tokenized deposits differ from stablecoins: Tokenized deposits represent bank liabilities, while stablecoins are issued by private entities and backed by reserves.

🔹 Overledger is ...

Bittensor could be more impactful than Bitcoin, according to @BarrySilbert

🟠 “The boldest prediction that I could make for Bittensor is it could be a better version of Bitcoin as a global store of value"

⚫️ "Instead of spending $10–12 billion a year to secure the Bitcoin network, imagine using that to incentivize a global problem solving network”

$TAO

post photo preview

🚀 The race to infinity: exploring new paths to other worlds 🚀

A new presentation explores possible routes toward interstellar travel, from advanced propulsion and warp-drive concepts to wormholes, quantum computing, simulated worlds, and consciousness-based experiences.

🔑 Key points

🔹 The distance problem: A journey to a nearby star such as Proxima Centauri would take approximately 4.4 light-years, while conventional propulsion could require thousands of years.

🔹 Advanced propulsion is explored: The presentation covers ion and plasma engines, nuclear fission, fusion, solar sails, laser sails, and antimatter propulsion.

🔹 Generation ships are proposed: Entire communities could travel through space, allowing descendants to reach the destination.

🔹 Cryogenic travel is considered: Travelers could potentially be preserved while the journey takes place.

🔹 Genetic arks offer another path: DNA, biological information, and raw materials could be transported and reconstructed at another ...

September 13, 2026
post photo preview
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
This Is The Income A Family Needs To Live Comfortably In Every US State

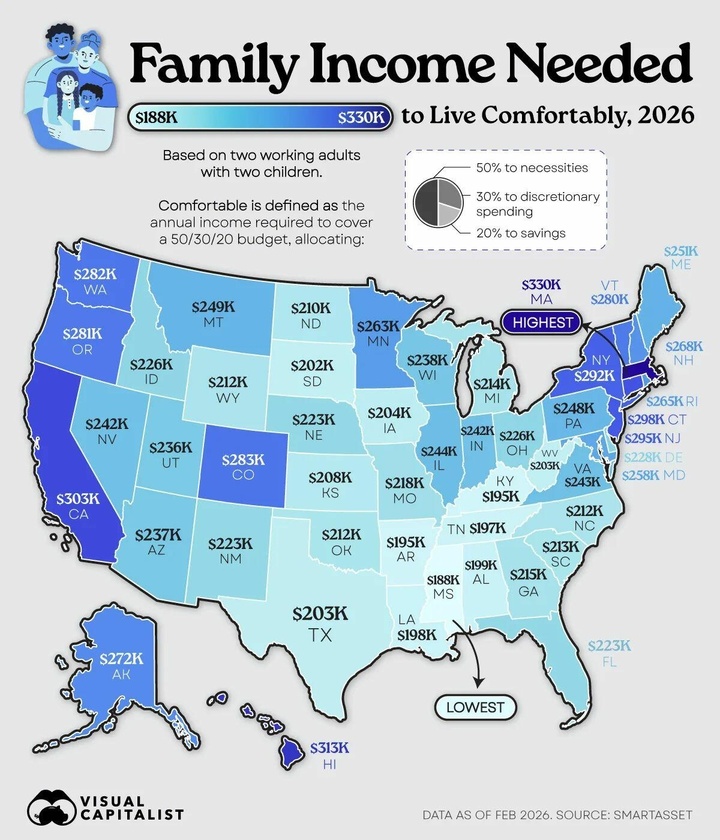
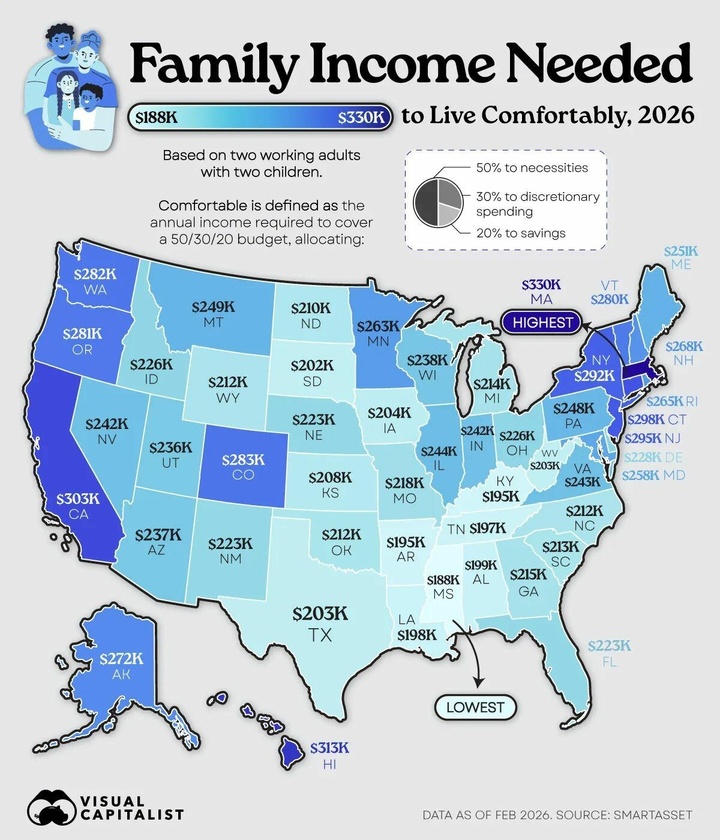
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notes, Massachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
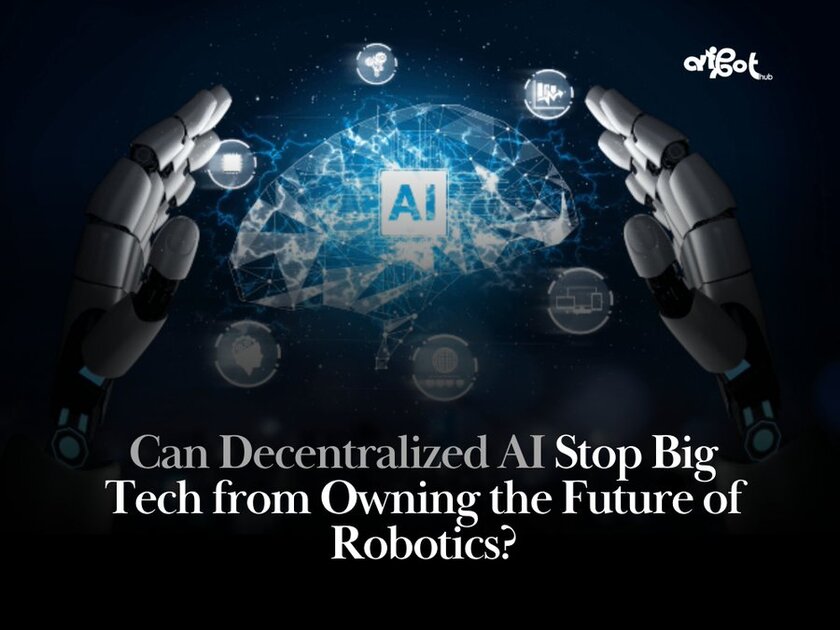
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals