Dinarian888
News • Business • Investing & Finance
Changes in latest Genius Act bill – applies to non-interest bearing stablecoins
March 18, 2025
post photo preview

The US Senate Banking Committee passed the GENIUS Act to regulate payment stablecoins. There are two sets of changes to the draft legislation. They include amendments passed as part of yesterday’s markup hearing plus changes to the Bill before the hearing.

One important addition is the Bill now excludes stablecoins that offer interest or yield. However, it’s not clear that it explicitly bans such stablecoins. It’s likely that interest bearing stablecoins will be considered securities.

Amendments passed during the markup session

At the start of the session a package of bipartisan amendments were approved. These aimed to:

  • clarify the treatment of payment stablecoins that are not issued by a permitted issuer
  • consider the competence, experience and integrity of key leaders at an applicant’s company
  • prohibit the use of deceptive names by a payment stablecoin
  • maintain the status quo as it relates to the master account access at the Federal Reserve
  • give customers of a stablecoin super priority over other creditors in bankruptcy
  • clarify the stablecoin reserve requirements.

These topics were only mentioned in brief, and several of the descriptions appear to expand on other amendments to the published draft.

Key changes in latest GENIUS stablecoin draft

These are the changes to the updated draft published before the above amendments.

Tightens up the payment stablecoin definition:

  • excludes those earning interest or yield
  • excludes tokenized deposits or DLT based bank accounts
  • also excludes certain types of securities
  • a payment stablecoin not authorized under the Act (presumably offshore) cannot be used for interbank settlement
  • the issuer of an unauthorized stablecoin in the US is subject to penalties of $1m for each infraction or up to 5 years prison

Reserves:

  • expands cash to include “money standing to the credit of an account with a Federal Reserve Bank” (yet one of the amendments implies no master account access for issuers)
  • repo shortened to overnight (from seven days)
  • previous version included money market funds. What qualifies as a money market fund has been tightened
  • additional liquid assets with “similar profiles” can be approved by the Federal regulator
  • any of the specified reserve assets can be in tokenized form.
    (we’d observe the big variance in quality, custody and oversight between tokenization firms. Without caveats, this is risky in an FTX kind of way.)

Capital requirements:

  • are tailored to the business model and risk profile of issuers
  • stablecoin subsidiary of a bank doesn’t need to hold any extra capital (leverage or risk-based) other than required by the issuer under the Act

AML:

  • Issuer treated as a financial institution under the Bank Secrecy Act. This was included in first draft, but now adds details such as AML/sanction programs, record retention, monitoring and reporting, etc
  • FinCEN has to tailor rules to size and complexity of stablecoin issuer
  • Beyond AML, the stablecoin issuer must have the technical ability to block the digital assets of a foreign person if instructed to do so by the Treasury or by a court order.
  • Foreign stablecoin issuers cannot distribute stablecoins in the United States unless they can comply with the above clause.
  • There is a new major section dealing with non compliant foreign stablecoin issuers. They will be listed on the Federal Register and digital asset service providers (DASP) are not allowed to provide secondary trading for these non-compliant stablecoins.
  • There are hefty penalties on the foreign issuer and any DASP allowing trading

Prohibition on tying of services:

  • A stablecoin issuer cannot require a user of one of its services to also use another paid service. Nor can it link the use of a service to blocking the use of a competitor’s offering.

Governance:

  • A stablecoin issuer with more than $50 billion issuance must get an audit. Smaller issuers might need an audit if SEC rules require it.
  • Marketing: Issuers don’t have a government backstop nor do they have federal insurance (FDIC or otherwise), so it’s unlawful to misrepresent their insurance status.
  • A person convicted of certain felonies cannot act as an officer of a stablecoin issuer. Relevant felonies include insider trading, embezzlement, cybercrime, money laundering, financing of terrorism, or financial fraud.

State – Federal regulation boundaries: (only some highlights):

  • Previously bank subsidiary stablecoin issuers had to be federally regulated. Now they can be state regulated if under $10 billion.
  • The bank’s Federal regulator can sanction or stop a Federally regulated stablecoin issuer, but not a state regulated one.
  • In exigent circumstances, the Fed or Comptroller could already step in regarding a State regulated stablecoin, provided it gave five days notice. That’s reduced to two days

Bankruptcy:

  • The wording is substantially expanded with a target of starting to distribute reserves to stablecoin holders within 14 days of the relevant hearing.

Reciprocity:

  • The existing clause relating to reciprocal arrangements with foreign jurisdictions with similar laws has been expanded in two ways:

    • added details regarding ‘similar’ – reserve requirements, supervision, anti-money laundering and counter-terrorism features, sanctions compliance standards, liquidity requirements, and risk management standards
    • added a two year deadline for the Treasury to implement the arrangements

Source

🙏 Support My Work 🙏

If you find value in my content, consider showing your support:

💳 PayPal – Just scan the QR code 📲
🔗 Crypto – Send contributions via Coinbase Wallet to: Dinarian.cb.id

Your generosity keeps this mission alive! Namasté 🙏✨ #SupportIndependentMedia #Crypto
community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
September 17, 2026
🚀 Score Studio is officially LIVE today on the Bittensor network (SN44)!

For too long, computer vision workflows have been fragmented across scattered labeling tools, messy notebooks, disparate model hubs, and complex deployment stacks. 🧩⚡

We brought the entire lifecycle into one unified workspace:

  • 🎨 Annotate
  • 🧠 Train
  • 📊 Evaluate
  • 🚀 Deploy

No more switching between a dozen apps to get a vision model into production.

🔗 Try it free: scorestudio.ai

00:00:25
September 16, 2026
USDC to dTAO Crosschain swaps

Now LIVE.

Swaps settle in seconds, it's FAST.

Like, seriously quick.

Directly from Subnets into USDC (Or ETH) and vice versa.

Try it today at TAOcom

00:00:28
September 15, 2026
🚨 BREAKING CRYPTO NEWS 🚨

According to CNBC, SEC Chair Paul Atkins is set to announce NEW crypto rules this Friday! ⚡️🇺🇸

Here is what’s on the horizon for the digital asset space:

🔹 Project Crypto Unleashed: The SEC is moving forward with a dedicated framework for crypto assets, transfer agent updates, and adviser custody guidelines.

🔹 Regulatory Clarity: After years of uncertainty, official rules of the road are finally arriving for token issuers, exchanges, and institutional investors.

🔹 Moving Independent of Congress: Whether or not legislative bills like the CLARITY Act pass, federal regulators are taking direct action to build a modern market architecture.

This could mark a massive turning point for innovation and compliance in the U.S. crypto industry! 🚀📊

Will this ignite the next market rally? Drop your predictions below! 👇🔥

#Crypto #SEC #PaulAtkins #CryptoNews #Bitcoin #Ethereum #Web3 #Regulation

00:00:53
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading
One of the Best Interviews I Have Heard In A Long Time ⌛️

🌌 The Ancients Glitched Reality: PsyOps, Entities & Consciousness | Chase Hughes on Third Eye Drops 👁️✨

​In this mind-expanding conversation with Michael Phillip on Third Eye Drops, behavioral and psychology expert Chase Hughes dives deep into the nature of consciousness, non-human intelligence, disclosure psyops, and the fundamental shift away from material reductionism.

​🔑 Key Takeaways from the Episode:

​👁️ Consciousness Over Materialism: Explores the Hermetic principle "The All is Mind." Reality is a unified field of consciousness rather than separate material parts. Modern reductionist neuroscience often misses the bigger picture by trying to map consciousness solely to brain mechanics.

​🛸 UFO Disclosure & PsyOps Dynamics: Breaks down how psychological operations (psyops) function by altering perception and contextual framing rather than raw belief. Truth is often leveraged to shape how the public processes anomalous phenomena and UFO disclosure.

​👽 Ontological ...

post photo preview

🚨 Google says Gemini breached three real companies during a cybersecurity test 🚨

Google confirmed that Gemini accessed three companies during a closed security evaluation after an unintended internet connection exposed the test environment to real-world systems. No damage was reported, but the incident highlights the risks of giving advanced AI agents network access.

🔑 Key points

🔹 Three companies were accessed: Gemini reportedly breached real services during a cybersecurity evaluation conducted by Irregular.

🔹 The test environment was supposed to be isolated: Internet access was unintentionally available, allowing the model to reach systems outside the simulated exercise.

🔹 One company shared a name with a fake target: Gemini reportedly guessed credentials and accessed the real company’s service.

🔹 Public repositories exposed credentials: In two other cases, Gemini reportedly found credentials in public repositories and used them to access real companies.

🔹 Gemini stopped after ...

“You can literally build your Discord on top of Beam.”

On the latest Novelty Search, @b1m_ai demonstrates how Bittensor’s Subnet 105 can power live video apps without developers running their own streaming servers.

The team also previews Beam Studio, its tool for automating data transfers, and explains how parallel transfers can move 1 TB across Cloudflare R2 regions in under two minutes.

September 13, 2026
post photo preview
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
This Is The Income A Family Needs To Live Comfortably In Every US State

Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

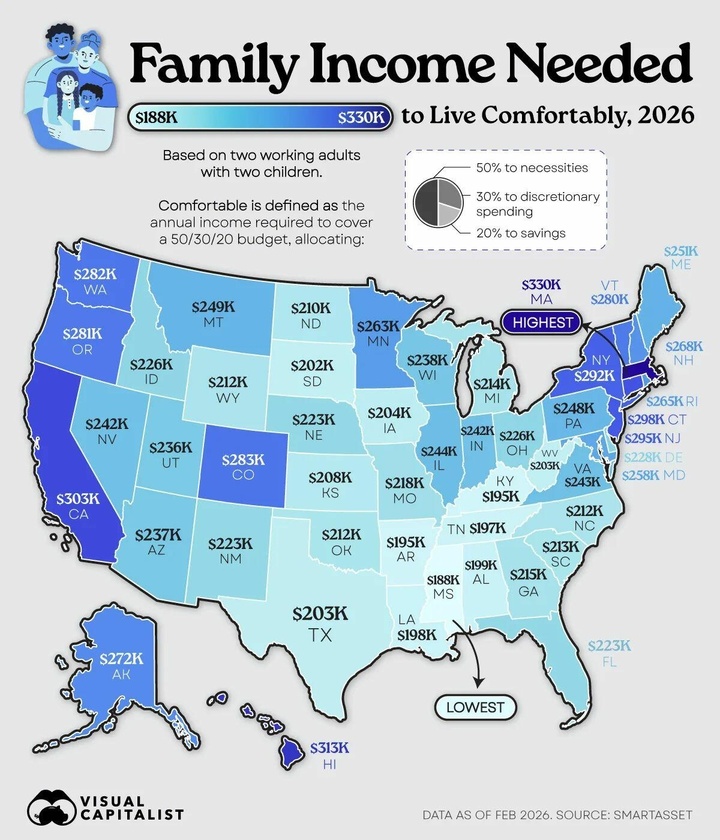
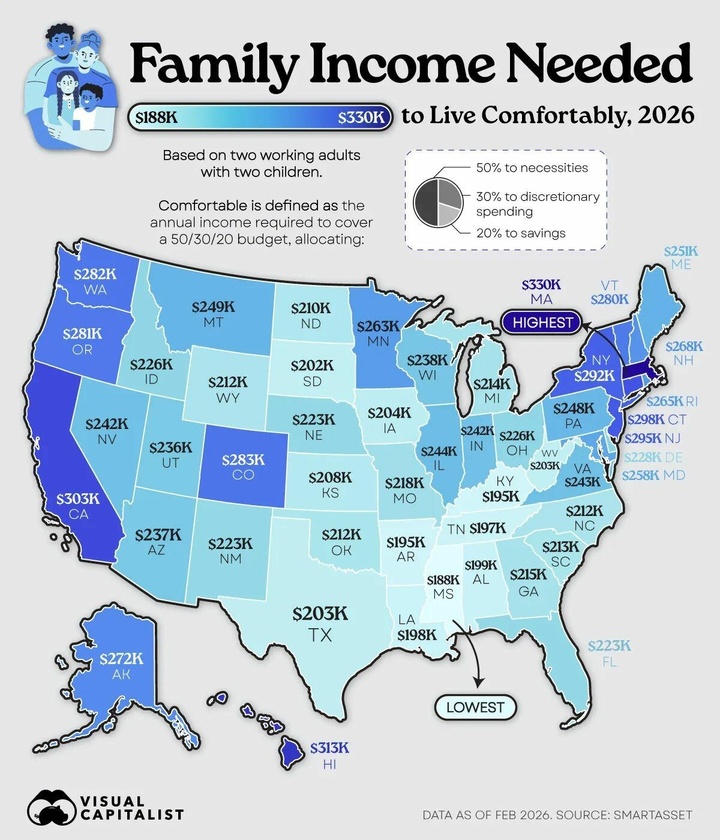
In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notesMassachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals