Dinarian888
News • Business • Investing & Finance
💳Citi’s Strategy to Dominate Institutional Payments💳
February 08, 2026
post photo preview

Citi's Institutional Payments Strategy

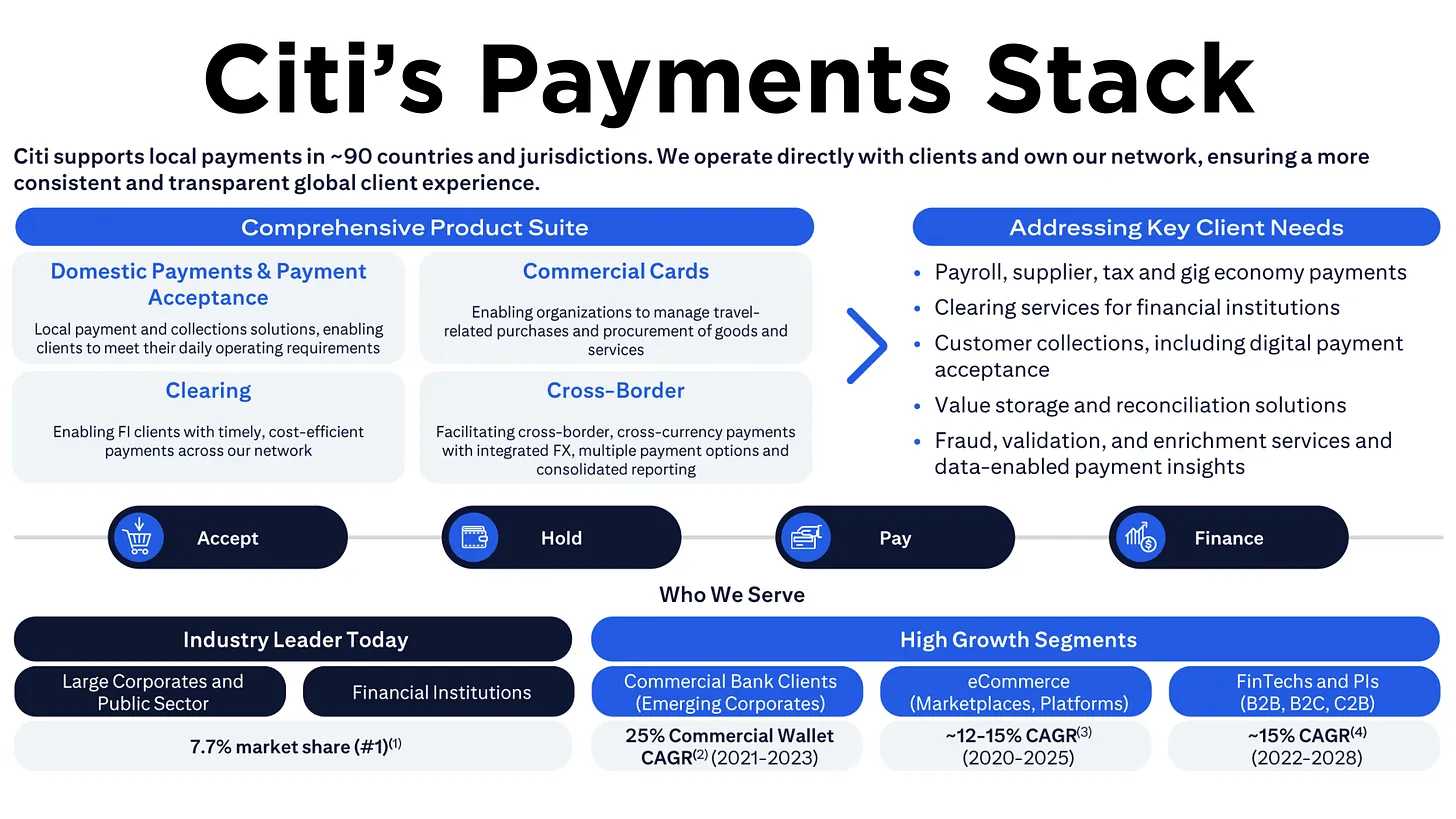
Citi’s Strategy to Dominate Institutional Payments is built on a foundation of technological innovation, strategic simplification, and a laser focus on institutional clients. The bank has transitioned from a fragmented global retail bank to a streamlined provider of high-margin institutional services, with its Treasury and Trade Solutions (TTS) and Securities Services segments now considered its "crown jewel." This shift, led by CEO Jane Fraser, involved exiting 14 international consumer markets and slashing decades of "tech debt" through a multi-billion-dollar partnership with **Google Cloud**, creating a modern, unified data and cloud infrastructure.

At the core of Citi’s dominance in institutional payments is Citi Token Services, a blockchain-powered platform launched in September 2023. This service converts client deposits into digital tokens, enabling 24/7, real-time cross-border payments, automated trade finance, and just-in-time liquidity management. By using private blockchain technology managed entirely by Citi, clients avoid the need to host their own nodes. The solution has been successfully piloted with Maersk and a canal authority, demonstrating how smart contracts can reduce transaction times from days to minutes—mirroring the functions of traditional bank guarantees and letters of credit.
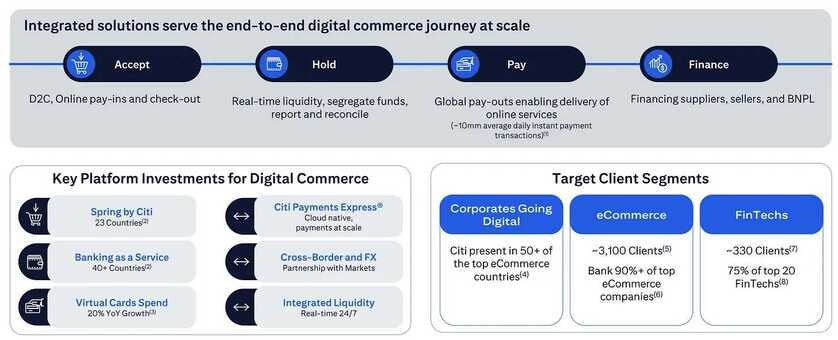
Citi is further strengthening its position through strategic partnerships, such as its collaboration with Coinbase to expand digital asset payment solutions for institutional clients, enabling seamless fiat-to-crypto transitions. The bank is also leveraging generative AI to automate regulatory compliance, improve cash forecasting by 50%, and reduce operational case times by 90%, directly enhancing the efficiency and reliability of its payment services.

With a global network spanning 95 countries and a focus on real-time, transparent, and programmable financial services, Citi is redefining the institutional payments landscape. Its strategy—centered on infrastructure modernization, digital asset innovation, and client-centric automation—positions it to capture market share from both traditional banks and fintechs, particularly as cross-border instant payments become the norm by 2028.

As blockchain infrastructure inches closer to the core of global finance, a consequential debate is taking shape inside banks and among institutional investors.

What form of digital money will ultimately dominate on-chain settlement?

Stablecoins have so far captured the spotlight, buoyed by rapid adoption and growing regulatory attention. But a different shift is underway inside the banking sector, where executives are increasingly confident that tokenized bank deposits, and not privately issued stablecoins, could become the preferred on-chain dollar for institutional and wholesale use.

“We don’t start with the asset,” Biswarup Chatterjee, global head of partnerships and innovation, Citi Services at Citi, told PYMNTS. “We typically start with our client need, and then we look at the pros and cons of each type of asset or financing instrument.”

For institutional money, innovation can often begin with constraint.

“When you’re dealing with money as a financial institution, you’re acting in a fiduciary capacity,” Chatterjee said, framing why safety and soundness dominate early conversations with clients.

From that perspective, the critical questions around new digital instruments are regulatory and operational before they are technological. Are these assets well-regulated? Do they operate within clearly defined legal frameworks? Can they be governed with the same rigor as traditional deposits or securities?

For institutions that manage systemic liquidity, and their clients, those questions are becoming non-negotiable. Within that context, tokenized deposits are what is emerging as a natural evolution of existing bank money.

“Within the bank’s network, tokenized deposits are an efficient way for our clients to be able to get that 24/7, always-on availability,” Chatterjee said.

The Race to Define the On-Chain Dollar for Institutional Use

By anchoring decisions in client economics and workflows, banks are positioning themselves less as promoters of specific technologies and more as integrators tasked with assembling the right mix of tools for each use case. Institutional clients are not simply looking for digital replicas of existing money; they are grappling with the friction of moving funds across use cases and jurisdictions.

“There’s this constant need to transform money across its various forms and shapes,” Chatterjee said, adding that payments, working capital and financing increasingly overlap, and inefficiencies emerge when money cannot move fluidly between those roles.

By representing deposits on distributed ledgers, banks can offer real-time movement of money across accounts, entities and geographies without leaving the regulated perimeter. For enterprises and institutions, this promises faster settlement, improved liquidity management and reduced operational friction, all without introducing new balance sheet or counterparty risks.

In this sense, tokenized deposits may turn out to be less disruptive than they appear. They modernize the plumbing of banking rather than bypassing it, extending familiar money into programmable environments.

Regulation, Interoperability and the Velocity of Money

The moment money exits a bank’s direct network, however, the strengths of tokenized deposits begin to fade. Cross-border payments, underbanked regions and counterparties outside major financial institutions can expose gaps in reach and efficiency when it comes to tokenized deposits.

This is where Chatterjee said he sees a role for stablecoins, not as competitors to banks, but as connective tissue.

“When money leaves the bank’s network and goes out into the external ecosystem, that’s where we see the role of stablecoins coming in,” he said, assuming they operate in a “very safe and sound and regulated manner.”

The result is likely to represent not a binary choice but a continuum. Just as checks, wires, cash and instant payments coexist today, digital money is likely to fragment into specialized forms optimized for different environments.

At the heart of the impact financial blockchain is having on digital money’s evolution lies a deceptively simple question: What makes money “good”?

For Chatterjee, the answer hinges on universal acceptance and trust.

“What makes a currency strong … has a lot to do with universal acceptance,” he said.

Assets that cannot be readily transferred or accepted risk becoming stranded, unable to circulate productively; while trust is fundamental to the value and stability of money, no matter its form. That logic applies equally to tokenized deposits and stablecoins. Without trust and transferability, neither is likely to function as a true institutional settlement asset.

Despite the focus on tokens and technology, Chatterjee was clear about where long-term value resides. It is not in the token itself, but in service.

“Client service and the client experience is what is going to drive the winning proposition,” he said.

Source 1

Source 2

🙏 Donations Accepted, Thank You For Your Support 🙏

If you find value in my content, consider showing your support via:

💳 Stripe:
1) or visit http://thedinarian.locals.com/donate

💳 PayPal: 
2) Simply scan the QR code below 📲 or Click Here: https://www.paypal.com/donate/?business=8K3TZ2YFZ7SMU&no_recurring=0&item_name=Support+Crypto+Michael+%E2%9A%A1+Dinarian+on+Locals+Blog&currency_code=USD


🔗 Crypto Donations Graciously Accepted👇
XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

 

community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
Ripple President Monica Long announced the use of XRP-POOLS 🤯

Ripple President Monica Long announced the use of XRP-POOLS to leverage XRP as collateral for funding customers’ payments from credit card institutions.

We are talking here about TRILLIONS of DOLLARS on the XRP-Ledger!

OP: Jacktherippler

00:00:28
🔥 Interview With Jacob "Const" Steeves, Co-Founder of Bittensor 🔥

Insane Interview Jacob "Const" Steeves (@const_reborn), Co-Founder of Bittensor and CEO of Affine, for an deep dive into what's coming next for Bittensor! 🧠⚡️

From fighting the AI cabal and competing with frontier labs to revenue models and Gamma Tokens—we covered it all. 🔥

⏱️ Timestamps:

0:00 Meet Jacob "Const" Steeves 👋
0:27 Fighting the AI Cabal 🛡️
8:40 Competing With Frontier Labs ⚔️
11:02 Templar's Departure & Teutonic 🏛️
15:44 Research, Revenue & Gamma Tokens
21:31 What's Next for Bittensor? 🔮

Catch the full conversation below! 📺👇

00:23:20
🪙 Is a Gold-Backed Dollar Making a Comeback? 🇺🇸🟡

The global financial landscape could be on the verge of a historic pivot. The U.S. Treasury has reportedly hired economist Judy Shelton—a vocal advocate for a gold-backed currency for three decades—sparking intense speculation about the future of the monetary system. 📈📉

The Core Proposal & Historical Context 📜⏳

🔹 The Shelton Plan: The proposed mechanism involves issuing a Treasury bond that holders can redeem for either U.S. dollars or physical gold.

🔹 A Nod to the Past: This exact promise was standard on U.S. war bonds until 1933, when Congress ultimately suspended convertibility during the Great Depression. 🏦💵

The Global Gold Rush 🌍🏦

🔹 The Biggest Stack: The United States currently holds 8,133 tonnes of gold—the largest reserve on the planet.

🔹 Global Accumulation: Central banks worldwide are stacking gold at an unprecedented rate. For instance, China has aggressively purchased gold for consecutive months, and ...

00:02:45
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading

🤖 Grok Bot adds proactive suggestions that spot work before users ask 🤖

Grok Bot can now identify tasks it may be able to handle and proactively suggest them to users through their selected Primary Bot.

🔑 Key points

🔹 Suggestions are proactive: Users no longer need to initiate every task manually.

🔹 Inbox triage can be suggested: Grok Bot may offer to review, organize, or prioritize incoming messages.

🔹 Meeting preparation can be automated: The Bot can suggest preparing agendas, briefing materials, summaries, or relevant documents.

🔹 Follow-up drafting is included: Grok Bot may identify situations where a follow-up message or response could be prepared.

🔹 Suggestions do not use the weekly quota: The proposal itself reportedly does not count against the user’s weekly usage limit.

🔹 Primary Bot selection is required: The capability becomes available when a Bot is selected as the user’s Primary Bot in the app.

🔹 Memory remains attached to the Bot: The assistant can use the ...

⚡ Chutes’ Kappa matches Llama 3.2 1B using 94% fewer training tokens ⚡

Chutes (SN64) trained Kappa across a decentralized GPU network and reportedly matched or exceeded Meta’s Llama 3.2 1B on several benchmarks using roughly 576 billion tokens instead of up to 9 trillion.

🔑 Key points

🔹 94% fewer tokens: Kappa reached comparable results to Llama 3.2 1B with a much smaller training budget.

🔹 Benchmarks included ARC-C, OpenBookQA, and TruthfulQA: Kappa reportedly matched or outperformed Llama 3.2 1B across those evaluations.

🔹 Training happened across distributed GPUs: Parallax coordinated independently operated hardware in different regions and with different performance levels.

🔹 Training costs were reportedly 90% lower: Chutes estimates Kappa’s cost per training token was significantly below conventional centralized approaches.

🔹 Hybrid architecture improves efficiency: Kappa combines traditional attention with Gated DeltaNet-2 linear attention to reduce memory and compute ...

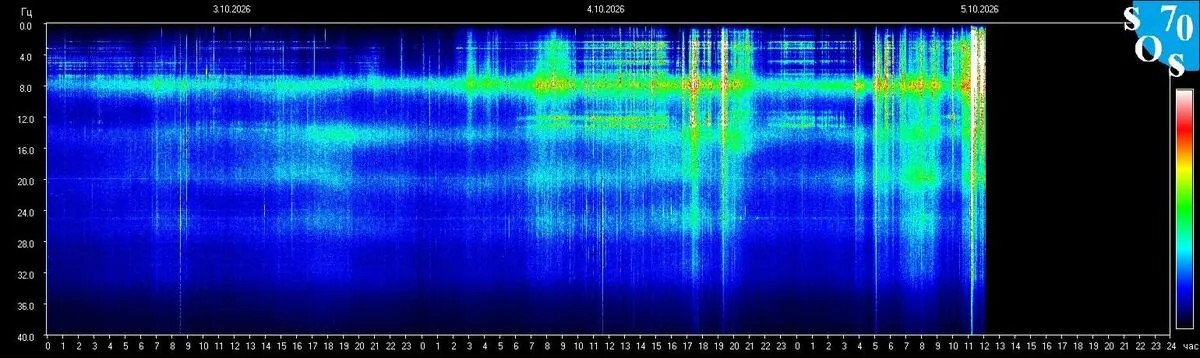
🌎 Schumann Resonance Today 10/5 🌎

Right now the Schumann resonance fundamental sits at 7.83 Hz, with geomagnetic activity unsettled (Kp 3.3).

Low Solar Pressure, Earth Stays Composed
A Kp of 3.3 and slow solar wind keep geomagnetic conditions subdued.

post photo preview
September 13, 2026
post photo preview
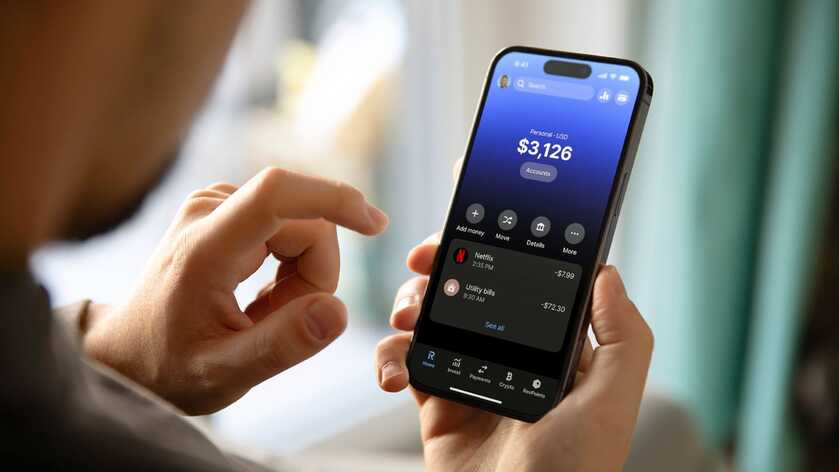
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6
Read full Article
post photo preview
This Is The Income A Family Needs To Live Comfortably In Every US State

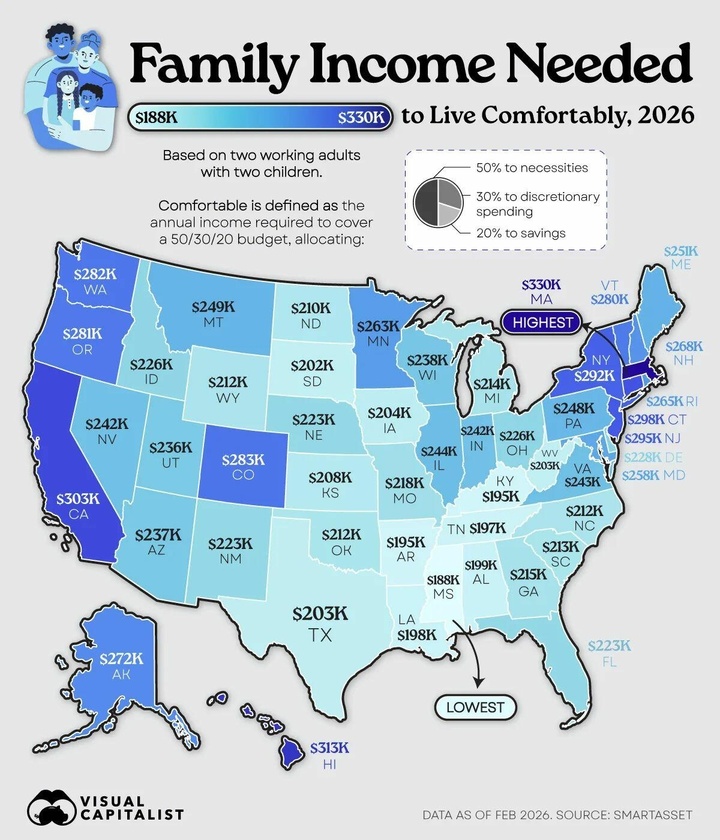
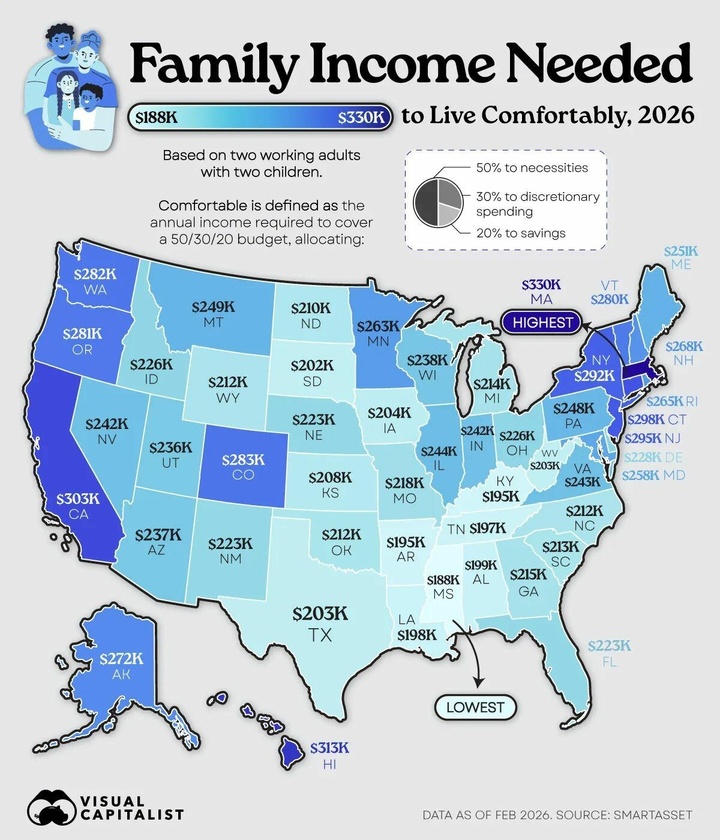
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notes, Massachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6
Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6
Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals