Dinarian888
News • Business • Investing & Finance
🌐USTC Revitalization and Incremental Peg to $1 through the implementation of a Peg Divergence Tax on Transactions both on and off chain🌐
January 23, 2023
post photo preview

(Dinarian Note: This is by far the BEST re-Peg Plan I have seen, it will take time, but this would eventually re-peg the USTC to market value, giving utility back to the network, and eventually back to $1 USD. It's a Lottery ticket worth investing a little bit in... (NOT FINANCIAL ADVICE))

USTC Revitalisation and Incremental Peg to $1 through the implementation of a Peg Divergence Tax on Transactions both on and off chain

Nearly 8 months have passed since the collapse of Terra Luna (LUNC) and USTC last May, and while we’ve made great strides in updating the blockchain and keeping it secure we have been severely lacking in terms of developing on-chain utilities and repegging USTC.

Repegging USTC is no easy task, while on-chain transactions and swaps can be maintained algorithmically in a de-peg scenario, without off-chain implementation USTC relied on arbitragers maintaining the peg. If arbitragers failed to hold the peg USTC then relied on TFL(Luna Foundation Guard) having enough funds in reserve to defend the peg. When both these defence mechanisms failed the price of USTC crashed causing LUNC to mint into oblivion. This leaves us in the situation we are today with LUNC, a hugely inflated token that’s utility derived from the stability of USTC now gone and 0 capital in reserve to buyback or defend the peg.

There’s also a misconception that a stablecoins utility comes from its ability to be stable at $1USD. This is not the case, whether it’s one cent or one dollar, its utility comes from it being stable at a set value. So, I’m proposing we peg USTC to around its current market value by applying a peg divergence tax on both on and off-chain transactions and incrementally pull peg back to $1USD over time. Not only does this bring instant utility, it incentives dApps to use USTC over any other stablecoin as they stand to make more profit.

The Peg Divergence Tax

The peg divergence tax works by taxing slightly more than the spread (the difference between the selling price and the peg price). The taxes retained by the protocol are then used to buy back USTC to maintain the peg. In the beginning the tax is always on the seller side to incentivise buying and it always accumulates the more desirable asset. To work it needs to be applied to both on and off-chain transactions. At the beginning the depeg events may occur until the protocol has retained enough assets to buy back to the set peg.

Mathematically how the algorithm will operate:

For the worked examples I’ll be using a peg of 1USD and a profit multiplier of 1.1.

X = (Target Peg Price)

Y = (Market Price)

T – (Tax/Transaction Fee)

M – (Profit Multiplier)(optional)

Scenario 1:Ā Where the price is below 1USD or (Y<X)
T = ((X-Y)*M)

Worked example : X = $1.00, Y = $0.99 , M = 1.1

T = (($1-$0.99)*1.1)

T = $0.011

Example: Seller creates a sell order at $0.99. Buyer pays $0.99 BUSD. Seller receives $0.979 BUSD. Protocol retains $0.011 BUSD.

Scenario 2:Ā Where the price is above 1USD or (Y>X)

T = ((Y-X)*M)

Worked example : X = $1.00, Y = $1.01 , M = 1.1

T = (($1.01-$1.00)*1.1)

T = $0.011

Example: Seller creates sell order at $1.01. Buyer pays $1.01… Profits are dependant on protocol purchase price. LUNC holders are incentivised to swap into USTC (using liquidity pool of USTC bought back by protocol)

Scenario 3:Ā Where the market price equals the peg
If (X)=(Y) let T=0

In this instance the tax does not come into effect and is dormant.

Implementation

Phase 1:Ā We re-peg USTC to around its current market value. This gives instant utility to the network by allowing dApps to immediately begin selling services/products on the Terra network in USD values.

Phase 2:Ā We start the incremental pull back to 1USD peg by disabling the tax mechanism where the price is above peg, and just apply the tax to any deviation below. What this does is allows the price to deviate above peg but not below. As the price of USTC increases we repeg at incrementally higher values until we reach 1USD.

This incremental peg makes USTC more desirable than any other stablecoin to build on/invest in. The reason for this is when service/product providers convert their profits from stablecoin to FIAT its redeemable for the same value, USTC will be the only stable that will have the ability to 50x.

Phase 3:Ā Use the USTC obtained by the protocol during buybacks to provide a liquidity pool which would allow unidirectional LUNC>>>USTC swaps without any minting. This serves to reduce LUNC supply without increasing USTC supply.

Phase 4:Ā Once we’ve reached 1USD peg, we relax the algorithm’s parameters to allow for limited arbitrage to occur again and increase utility further. The algorithm is not switched off, it’s just lying dormant, and will reactivate in the event arbitragers fail and prevent any further de-peg scenario.

The Profits

The profits generated by the algorithm should be used to further develop the Terra Classic ecosystem and speed up both the re-peg to 1USD and to burn down the supply of LUNC.

A percentage of the profits should be retained for the following purposes:

  • To provide a liquidity pool so that we can re-enable swaps between USTC and LUNC but without minting. Swaps would be available while liquidity is sufficient.
  • A liquidity pool to buy back USTC at times of low taker and high maker volume. This will allow capital to move more freely and incentivise network utilisation.
  • CEXs should be compensated with a percentage of the profits generated. If they implement our code and help save USTC they deserve to be compensated.
  • To compensate developers, app builders and incentivise further development and building of community owned utilities.
  • To buy back and burn both LUNC and USTC and speed up recovery of our network.

Case Study : Binance BUSD/USTC Trading Last Quarter 2022

To prove it would beneficial for both LUNC/USTC holders and the CEXs to implement the protocol and give some indication to its feasibility I modelled it against the last 3 months trading between the BUSD/USTC trading pair on Binance. Binance has the highest trading volume of both USTC and LUNC and for the last quarter USTC has had an average price of approximately $0.025 BUSD. I’ve modelled the date based on a rate multiplier of 1.1 and three different peg levels of $0.02, $0.0225 and $0.025. Fees shown are those retained by Binance as they are currently implemented at a rate of 0.002%.

The above values show profits retained by the protocol with divergence tax applied to trading data as though it had no effect on the trading volume or prices and did not buyback of USTC. We should assume that the tax will have a massive reduction on trading volume below peg and to reduce these figures accordingly. During the month of October the price of USTC never fell below 0.025 so the protocol would not have come into effect and would have retained no profits. If we were toĀ assume a 90% reduction in trading volumeĀ below the set peg levels we would still have retained over $52,000 at a peg of $0.02, over $1,593,000 at $0.0225 and $5,448,00 at $0.025 over 3 months of trading. If we then gave even 10% of these fees back to Binance they would have increased profits of approximately 16%, 38% and 67% for the respective peg levels over the same time period.

Conclusion

Given that we are going to whitelist Binance wallets I believe we should capitalise on the close relationship and be the first blockchain to have their capital controls implemented algorithmically both on and off chain. But this is not a utility and should not be viewed as such its more of a failsafe.

This approach should appeal to both USTC and LUNC holders alike and allow us to slowly but safely collateralise USTC with BUSD. It also doesn’t require any minting, funds from the Oracle/Community Pools or an external liquidity provider so there shouldn’t be any major initial negative price action.

It doesn’t interfere with any of the other proposal that have been put forward so far by the community and if anything it should augment them.

This proposal requires more work and discussion around buyback rates and tax multiplier rates.

Negatives:

  • Most likely will have a dramatic reduction on trading levels below peg.
  • If the markets react badly and without and current onchain utilities to drive demand it could result in stale/no trading.
  • If there isn’t sufficient demand at/above peg and you need to sell you will be taxed quite aggressively offramping.

Has to be implemented by everywhere USTC is traded including off chain.
Link

community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
What If Every 80 Years...

ā³ History doesn't just rhyme—it repeats in a strict, predictable 80-year cycle, and every single one of them culminates in a hard reset.

From the American Revolution to the Civil War and World War II, major crises have hit humanity on an unyielding schedule. Now, we are standing right on the edge of the next major turning point.

According to generational history, we cycle through four distinct beats—and four specific archetypes (the Prophet, the Nomad, the Hero, and the Artist) who shape how we navigate the chaos. The role you play depends entirely on when you were born.

Are we ready for what comes next?

#HistoryRepeats #TheFourthTurning #Crisis #WorldHistory #TimeCycles #Generations #Future

00:00:49
Look how absolutely insanely advanced Ai is getting šŸŽ¬

Look how absolutely insanely advanced Ai is getting. To think, just a couple years ago, there was PokƩmon using your phone.

Now literally anything you can imagine and write into a prompt becomes real and interactive in real time.

Apple only but Android soon..

https://x.com/Simulon/status/2115519989545390108?a=j1seKPKfLx2FVSgZmh8&s=19

00:01:20
šŸ“¢ “WHY SHOULD YOU HAVE TO CHOOSE?”

And the message couldn’t be clearer.

For decades, traditional finance has forced the world to accept slow payments, trapped capital, and outdated infrastructure. šŸ“‰šŸ”’

Ripple is challenging that entire legacy model head-on. āš™ļøāš”ļø

⚔ The trust of traditional finance.
⚔ The speed of digital assets.
⚔ The future of money, without compromise.

This isn’t about replacing the financial system. 🌐

It’s about EVOLVING it. šŸš€
Ripple just delivered one hell of a message to the global stage:

šŸ“¢ ā€œWHY SHOULD YOU HAVE TO CHOOSE?ā€

šŸŒŽ The future of finance is being built right in front of us—and it’s happening with Ripple! šŸ’ŽšŸ“ˆ

#Ripple #XRP #CryptoNews #Web3 #FutureOfFinance #FinTech

00:01:00
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

šŸ”‘ Key points

šŸ”¹ Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

šŸ”¹ The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

šŸ”¹ The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

šŸ”¹ Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

šŸ”‘ Key points

šŸ”¹ Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

šŸ”¹ Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

šŸ”¹ The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
šŸ‘‰ Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? šŸ”œ

The future of Crypto x AI is about to go crazy.

šŸ‘‰ Here’s what you need to know:

šŸ’  'Based Agent' enables creation of custom AI agents
šŸ’  Users set up personalized agents in < 3 minutes
šŸ’  Equipped w/ crypto wallet and on-chain functions
šŸ’  Capable of completing trades, swaps, and staking
šŸ’  Integrates with Coinbase’s SDK, OpenAI, & Replit

šŸ‘‰ What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto šŸ‘‰txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

šŸ‘‰ Coinbase just launched an AI agent for Crypto Trading

šŸ‡ŖšŸ‡ŗ European Central Bank President Christine Lagarde to step down on February 7th.

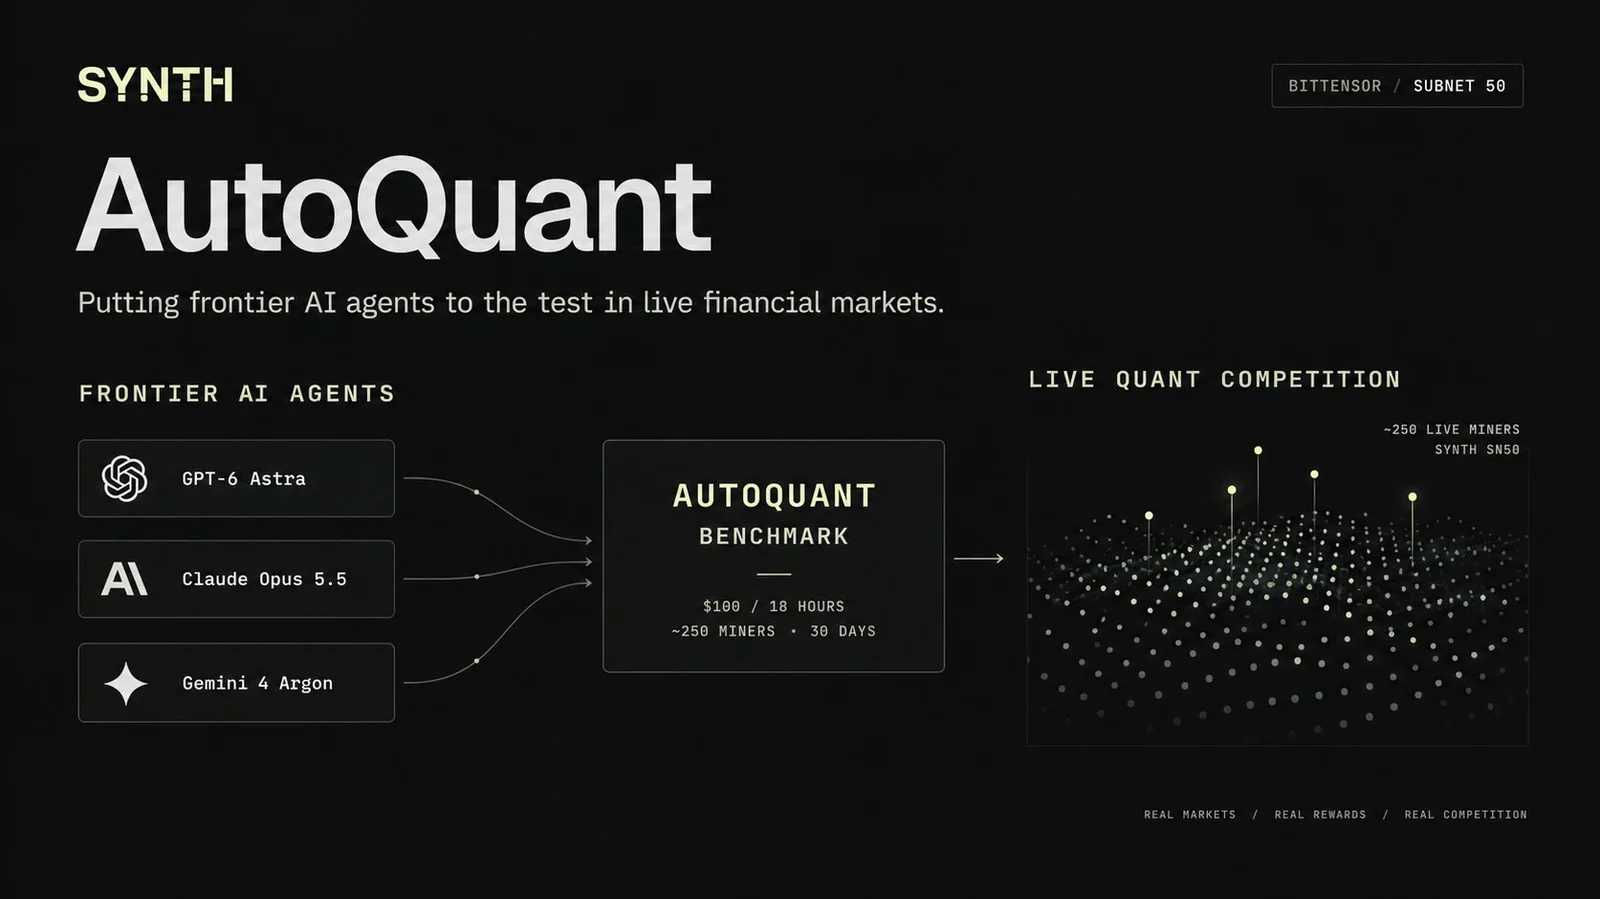
šŸ¤– Synthdata open-sources AutoQuant to test AI agents against SN50 miners

Synthdata (SN50) has released AutoQuant, a benchmark that pits frontier AI agents against live quantitative forecasting miners. In its reported tests, the agents have not consistently beaten the top miners.

šŸ”‘ Key points

šŸ”¹ Agents get limited resources: Each has 18 hours and a $100 budget to build a Monte Carlo forecasting model using a starter model and frozen one-minute market data.

šŸ”¹ Tests cover multiple markets: The benchmark measures one-hour and 24-hour crypto forecasts, plus 24-hour forecasts for commodities and equities.

šŸ”¹ Future data tests performance: Agents’ selected models are evaluated against the following 30 days of market data and roughly 250 live miners, using Synth’s forecasting and scoring approach.

šŸ”¹ Top miners still lead: No tested AI agent has consistently outperformed Synth’s leading miners. Claude Opus 5 scored 33.5 in the second campaign—about one-third of the top miner’s ...

post photo preview

Create content, Movies, Ad campaigns or just have fun using the new new Everyframe platform.

All the latest video models in one place under one subscription & cheaper than going direct.

šŸ‘‰Sign up FREE and receive 500 free credits.

šŸŽ¬https://app.everyframe.studio/r/78GQ96

#SORA #GenerativeAI #AIVideo #AICinematography
#RunwayML #MidjourneyVideo #Synthesia #AIAnimation #VisualEffects #VFX #IndieFilmmaking
#FilmmakersOfX #VirtualProduction

post photo preview
āš ļø90 DAYS WITHOUT THE GRIDāš ļø
Why Governments Are Preparing for Critical Systems to Fail

MIND BEND THEORY | DOCUMENTED INVESTIGATION

The United States is preparing major military installations to continue operating if civilian infrastructure goes down. Britain is telling households to prepare for days without essential services. India is warning that an attack on the financial system can weaken a nation. And the Bank of England is asking what happens when cyber defenses fail—not if they can prevent every attack.

Individually, each development has an explanation.

Put them beside one another, however, and a larger pattern becomes visible.

Over the span of only a few weeks, governments and financial authorities in the United States, United Kingdom and India have publicly discussed preparations for disruptions involving some of the systems modern society depends upon most:

Power.

Water.

Fuel.

Communications.

Banking.

Supply chains.

This does not establish that these governments are preparing for one secret event.

There is no public evidence of a coordinated countdown, predetermined blackout date or single intelligence warning connecting them.

But there is something here that can be documented.

Governments are increasingly planning around a question that sounds very different from traditional emergency preparedness:

What happens when the systems we normally assume will be available are no longer available?

And in the United States, that question has now reached the Pentagon.

DOCUMENT 01

UNITED STATES — FORTRESS AMERICA

On September 30, 2026, Defense Secretary Pete Hegseth established a program called FORTRESS America.

The acronym stands for:

Federal Operations for Resilience, Troop Resources, Energy, Supply and Survivability.

The program addresses a vulnerability that rarely receives much public attention:

The world's most powerful military still depends extensively on civilian infrastructure.

Electric grids.

Commercial supply chains.

Communications infrastructure.

Fuel.

Foreign sources of critical materials.

FORTRESS America is intended to reduce those dependencies.

The Pentagon's own public description says the initiative is designed to ensure that major U.S. military installations generate independent power so that bases remain operational even if the civilian grid is taken down by cyberattack or sabotage.

It goes beyond electricity.

The program includes five major areas:

Energy independence

Installation hardening and cyber resilience

Supply-chain and defense-industrial-base resilience

Strategic defense reserves

Space and spectrum resilience

The Pentagon also wants deeper reserves of critical supplies so military operations can continue when ordinary supply lines are disrupted.

The underlying idea is simple:

The military should be capable of functioning even when the infrastructure surrounding it cannot.

An October 7 implementation memorandum obtained by DefenseScoop shows that the Pentagon had already begun establishing the FORTRESS America Program Office and assigning officials to implement those objectives.

Then another piece of the story emerged.

DOCUMENT 02

THE 90-DAY REQUIREMENT

On October 25, Fox News published details from additional FORTRESS America documents its reporters reviewed.

According to that reporting, major continental U.S. military installations are being prepared to sustain essential operations for at least 90 days without outside support.

The essential systems reportedly include:

Power.

Water.

Fuel.

Communications.

Think about the distinction carefully.

The Pentagon isn't telling Americans that the United States will lose electricity for 90 days.

It isn't predicting a 90-day blackout.

Military contingency planning deliberately prepares for scenarios officials hope never occur.

But preparing installations for this possibility tells us something about the scenario being considered.

The Pentagon is building resilience around the possibility that a sufficiently serious conflict or attack could interfere with the civilian systems on which military installations normally depend.

The publicly released FORTRESS material specifically discusses:

Cyberattack.

Sabotage.

Grid disruption.

Foreign supply-chain disruption.

Attacks against installations.

And prolonged military contingencies.

That makes the 90-day requirement significant—but it must be described accurately.

Mind Bend Theory verification note:

The September 30 FORTRESS America program itself is documented publicly.

The October 7 implementation memorandum has been reported and described by DefenseScoop.

The 90-day requirement, however, currently comes from documents reviewed by Fox News, rather than a primary 90-day document independently published for the public.

That distinction matters.

We follow the documents as far as they take us—and no farther.

DOCUMENT 03

UNITED KINGDOM — BE READY FOR THREE DAYS

Now cross the Atlantic.

On October 22, the British government launched its new Be Ready campaign.

This time the audience wasn't the military.

It was ordinary households.

The UK government is asking households that are able to do so to prepare to remain self-sufficient for approximately three days during an emergency.

The government specifically discusses disruptions affecting:

Power.

Water.

Phones.

Internet access.

A Parliamentary Written Statement issued the same day explicitly states:

ā€œThe updated advice calls on households to be self-sufficient for three days in the case of an emergency.ā€

The government recommends maintaining three days of bottled water and non-perishable food.

Its expanded preparedness guidance includes:

Approximately three litres of drinking water per person per day

Three days of non-perishable food

Battery-powered or wind-up radio

Torch and spare batteries

Charged power bank

Essential medications

First-aid supplies

Blankets and warm clothing

Important telephone numbers written down

Basic hygiene supplies

Cash

Why cash?

Because during some disruptions, electronic payment systems and ATMs may not function normally.

That creates an important connection between infrastructure and finance.

Electricity isn't isolated from banking.

Communications aren't isolated from payments.

Modern infrastructure is interconnected.

And failure can move through those connections.

DOCUMENT 04

INDIA — ā€œWARS ARE NOT FOUGHT WITH WEAPONS ALONEā€

Three days later, on October 25, another statement appeared.

This one came from Indian Prime Minister Narendra Modi.

Modi was inaugurating the Reserve Bank of India's newly established Data Centre and Cybersecurity Training Institute in Bhubaneswar.

The facilities are designed to strengthen the technological foundations and cybersecurity resilience of India's financial system.

Four data centres will host mission-critical payment and settlement systems.

But Modi's explanation of why this matters went beyond ordinary cybersecurity.

His official statement says:

ā€œNowadays, wars are not fought with weapons alone; a nation can also be weakened by attacking its economy.ā€

He continued by saying India's growing economy requires its banking system to be protected against cyber looters and cyber terrorists.

That puts another critical system into the picture:

Money.

A modern economy depends on digital banking infrastructure almost as heavily as it depends on electricity and telecommunications.

Payment systems move commerce.

Banks hold liquidity.

Settlement systems move money between financial institutions.

Data centres keep those networks functioning.

Disrupt the financial infrastructure badly enough and the consequences don't remain inside banks.

They reach businesses.

Supply chains.

Payroll.

Purchasing.

Markets.

And households.

DOCUMENT 05

BANK OF ENGLAND — WHAT IF CYBER DEFENSE FAILS?

There is another document worth reading.

On June 30, Bank of England Deputy Governor Sarah Breeden delivered a speech titled:

ā€œAgents of Change.ā€

The subject was artificial intelligence and financial stability.

One section deserves particular attention.

Breeden warned that advanced AI systems are becoming increasingly capable of identifying and chaining together cyber vulnerabilities.

That changes the nature of cyber risk.

AI can help defenders.

But the same capabilities can potentially increase the speed and effectiveness of attackers.

The important change in thinking comes afterward.

Preventing attacks is no longer enough.

Financial institutions must also prepare to recover after a successful attack.

Breeden raised the possibility of simultaneous disruption across multiple financial firms.

She then asked whether critical financial institutions may eventually require completely separate failover capabilities—or even the ability to rebuild compromised core systems from ā€œbare metal.ā€

In October, Reuters reported that the Bank of England was pushing financial institutions further toward this type of recovery planning.

That represents a subtle but significant change in the question.

It isn't simply:

How do we stop the attack?

It's becoming:

What happens if we don't?

And:

How do we keep the system functioning afterward?

CONNECT THE DOCUMENTS

Now put the documents beside one another.

UNITED STATES

Military installations are being hardened so essential operations can continue when civilian infrastructure is disrupted.

UNITED KINGDOM

Households are being told to prepare for three days without services they normally assume will remain available.

INDIA

The prime minister publicly warns that modern conflict can weaken a country by attacking its economy and calls for stronger protection of banking infrastructure.

BANK OF ENGLAND

Financial authorities are examining recovery scenarios in which cyber defenses have already failed and multiple institutions could potentially be disrupted simultaneously.

These aren't identical programs.

They aren't even aimed at the same people.

And there is currently no public evidence demonstrating that they were coordinated.

But they share one important assumption:

CRITICAL SYSTEMS CAN FAIL.

And resilience therefore cannot begin after the failure occurs.

It has to exist beforehand.

THE SYSTEM BEHIND THE SYSTEM

This is where the story becomes bigger than individual announcements.

Modern infrastructure isn't a collection of isolated systems.

It's a network.

Consider what happens when electricity fails.

Without power, telecommunications eventually become difficult to maintain.

Without communications, electronic payments can be affected.

Fuel pumps require electricity.

Water systems depend on pumping and treatment infrastructure.

Businesses depend on payment processing.

Supply chains depend on communications, transportation and fuel.

Hospitals require electricity, communications, water, medicine and logistics simultaneously.

A serious disruption doesn't necessarily remain inside the system where it started.

It can propagate.

POWER → COMMUNICATIONS → BANKING → COMMERCE → SUPPLY CHAINS

And the dependency runs in multiple directions.

That interconnectedness is precisely why governments plan for resilience.

WHAT THIS DOES NOT PROVE

Mind Bend Theory exists to examine unusual patterns.

But a pattern isn't automatically proof of a conspiracy.

There is currently no public evidence showing that Washington, London and New Delhi are secretly preparing for the same scheduled event.

There is no verified date for a coming global blackout.

There is no public document establishing an imminent 90-day collapse of the American electrical grid.

And the Pentagon's 90-day military resilience requirement should not be interpreted as a prediction that Americans will lose electricity for 90 days.

That would go beyond the evidence.

What the evidence actually establishes is interesting enough.

Governments increasingly consider disruption of power, communications, supply chains and financial infrastructure plausible enough to justify concrete preparation.

The UK is preparing households.

The United States is hardening military infrastructure.

India is strengthening the technological backbone of its financial system.

The Bank of England is thinking about how banks recover after cyber defenses fail.

That isn't speculation.

It's in the documents.

THE QUESTION

Perhaps the most important change isn't what governments believe will happen.

It's what they're preparing to survive.

For decades, infrastructure security focused heavily on preventing failure.

The emerging model looks different:

Assume something eventually gets through.

Assume something eventually goes down.

Build the ability to continue operating anyway.

The Pentagon calls that resilience.

The UK calls it being ready.

Central banks call it operational resilience.

Different terminology.

Same fundamental question:

WHAT STILL WORKS WHEN THE SYSTEM DOESN'T?

DOCUMENT TRAIL

Read the Evidence Yourself

Mind Bend Theory strongly encourages readers to examine the original material rather than relying solely on our interpretation.

šŸ‡ŗšŸ‡ø DOCUMENT 01 — FORTRESS America Establishment

September 30, 2026

Defense Secretary Pete Hegseth's memorandum establishes FORTRESS America as a Department of Defense resilience program.

The publicly reported memorandum establishes the program around installation resilience, independent energy, strategic reserves, supply chains and related national-defense infrastructure.

Source type: Pentagon memorandum / official announcement.

šŸ‡ŗšŸ‡ø DOCUMENT 02 — FORTRESS America Implementation Memorandum

October 7, 2026

DefenseScoop obtained the memorandum from Under Secretary for Acquisition and Sustainment Michael Duffey directing officials to begin operationalizing the FORTRESS America Program Office.

It identifies five foundational pillars, including energy independence, installation hardening and cyber resilience, strategic reserves and supply-chain resilience.

Source type: Pentagon memorandum obtained by DefenseScoop.

šŸ‡ŗšŸ‡ø DOCUMENT 03 — 90-Day FORTRESS Requirement

October 25, 2026

Fox News reports that documents it reviewed require major continental U.S. installations to sustain essential operations for at least 90 days without outside support.

Source type: Journalistic reporting based on documents reviewed by reporters.

Important: This is not currently being presented by Mind Bend Theory as a publicly released primary 90-day Pentagon document.

šŸ‡¬šŸ‡§ DOCUMENT 04 — UK Cabinet Office Be Ready Announcement

October 22, 2026

The Cabinet Office announces the three-year Be Ready campaign and describes preparation for disruption affecting power, water, phones and internet.

Source type: Official UK government publication.

šŸ‡¬šŸ‡§ DOCUMENT 05 — Parliamentary Written Statement HCWS409

October 22, 2026

The UK Parliament records the government's explicit recommendation that households prepare to remain self-sufficient for three days.

Source type: Official Parliamentary record.

šŸ‡¬šŸ‡§ DOCUMENT 06 — Be Ready Household Emergency Checklist

The government's practical household guidance provides recommendations for water, food, radio, lighting, medication, power banks, emergency cash and other supplies.

Source type: Official UK government preparedness guidance.

šŸ‡®šŸ‡³ DOCUMENT 07 — Prime Minister of India / RBI Cybersecurity Facilities

October 25, 2026

Official statement documenting the opening of the Reserve Bank of India's Data Centre and Cybersecurity Training Institute and Modi's warning that countries can be weakened through attacks against their economies.

Source type: Official Government of India statement.

šŸ‡¬šŸ‡§ DOCUMENT 08 — ā€œAgents of Changeā€ — Sarah Breeden

June 30, 2026

The Bank of England deputy governor discusses rapidly advancing AI cyber capabilities, simultaneous disruption across financial institutions, separate failover infrastructure and potentially rebuilding compromised systems from bare metal.

Source type: Official Bank of England speech.

DOCUMENT 09 — Bank of England Cyber-Recovery Reporting

October 15, 2026

Reuters reports on the Bank of England's push for stronger recovery capabilities against AI-enabled cyberattacks, including bare-metal recovery.

Source type: Independent reporting.

MIND BEND THEORY

Follow the documents. Separate what they prove from what they don't.

Then ask why the preparation is happening now.

Documents attached to the investigation

FORTRESS America — Sept. 30 memorandum record
Pentagon FORTRESS America implementation memorandum — DefenseScoop
FORTRESS America 90-day documents — Fox News investigation
UK Cabinet Office — Be Ready announcement
UK Parliament — Written Statement HCWS409
India PM's Office — RBI Data Centre & Cybersecurity Training Institute
Bank of England — Sarah Breeden, ā€œAgents of Changeā€
Reuters — Bank of England cyber-recovery warning

Source

šŸ™To support my work, Helping to keep the signal high and the noise low:

šŸ‘‰ Cashapp: $thedinarian

šŸ‘‰ Buy me a coffee: https://buymeacoffee.com/thedinarian

šŸ‘‰ PayPal: Scan the QR code below šŸ“² or Click Here:Ā 

šŸ‘‡ Crypto Donations šŸ‘‡

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
September 13, 2026
post photo preview
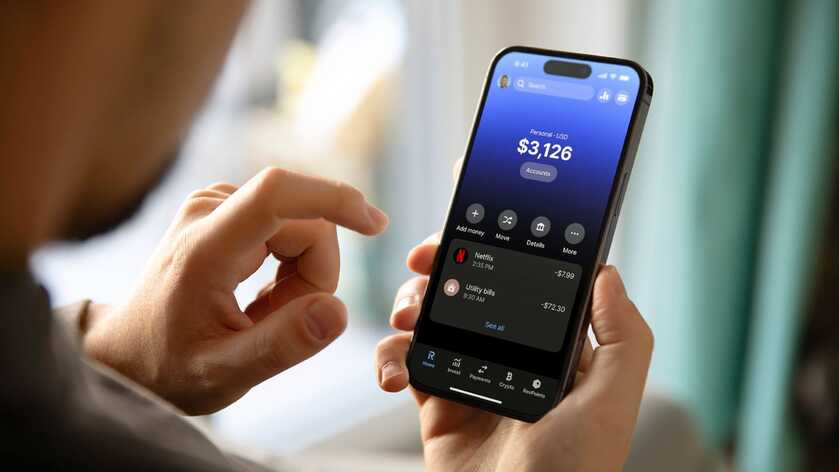
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an ā€œunauthorized third partyā€ reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request ā€œunder the reasonable belief that it was an authentic government agency requestā€ – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a ā€œlimitedā€ number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

šŸ™To support my work, Helping to keep the signal high and the noise low:

šŸ‘‰ Cashapp: $thedinarian

šŸ‘‰ Buy me a coffee: https://buymeacoffee.com/thedinarian

šŸ‘‰ PayPal: Scan the QR code below šŸ“² or Click Here:Ā 

šŸ‘‡ Crypto Donations šŸ‘‡

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
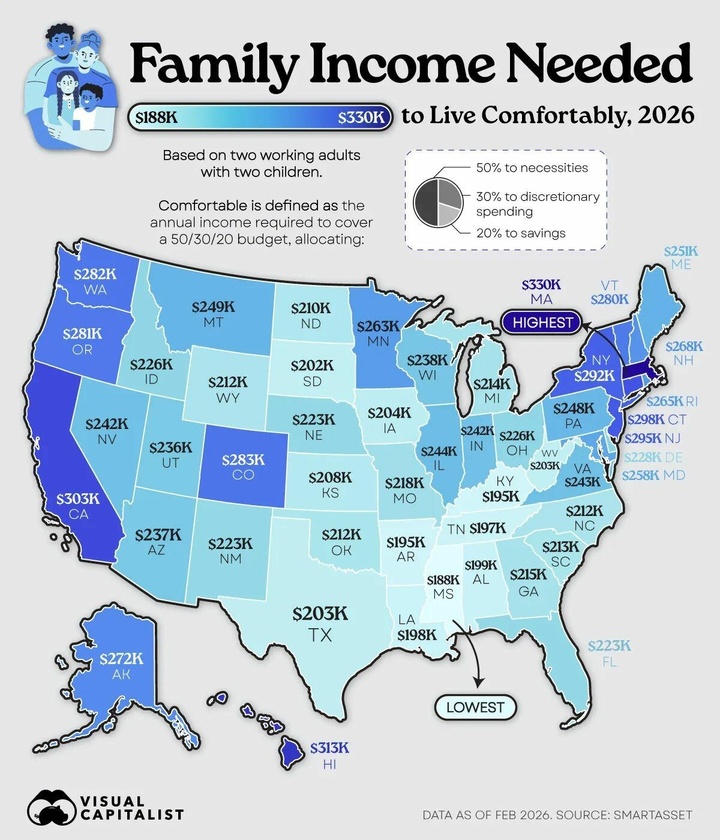
This Is The Income A Family Needs To Live Comfortably In Every US State

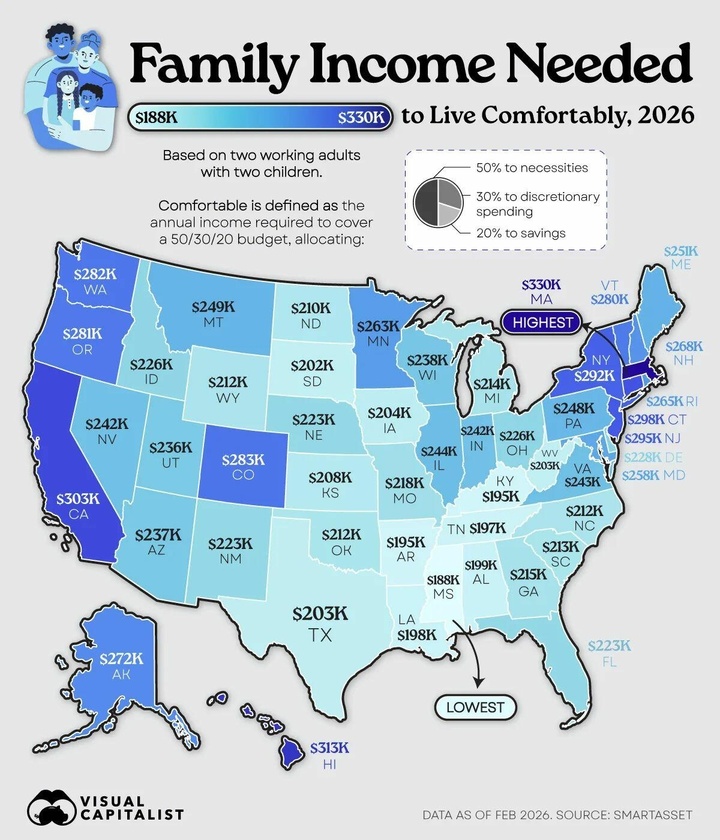
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come fromĀ SmartAssetĀ (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And asĀ Visual CapitalistĀ notes,Ā Massachusetts sits at the very top of that list.Ā Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having theĀ second-smallest populationĀ of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite theĀ wide range in living costsĀ across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky.Ā The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

šŸ™To support my work, Helping to keep the signal high and the noise low:

šŸ‘‰ Cashapp: $thedinarian

šŸ‘‰ Buy me a coffee: https://buymeacoffee.com/thedinarian

šŸ‘‰ PayPal: Scan the QR code below šŸ“² or Click Here:Ā 

šŸ‘‡ Crypto Donations Always Welcome šŸ‘‡

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals