Dinarian888
News • Business • Investing & Finance
Analysis: is a PayPal stablecoin worth the risk?
August 09, 2023
post photo preview

PayPal generated considerable excitement and curiosity when it unveiled its stablecoin PYUSD, which is backed 1:1 by cash and short term government securities. It will be operated by PayPal’s existing crypto partner Paxos, a New York regulated trust company.

Given the current regulatory cloud around crypto, some have questioned why PayPal chose to launch now. It was the first to acquire a crypto custodian (Curv) in 2021 and one of the first incumbent institutions to provide crypto services. 

By making its move now, it will likely accelerate U.S. stablecoin legislation.

The money to be earned form stablecoins

Ultimately the motivation boils down to money. And there are at leat three potential revenue sources: interest on reserves, FX and merchant services.

People commented that PayPal is bigger than Tether, the largest stablecoin. Actually, it is. And it isn’t. 

Tether holds more than twice as much in customer funds as PayPal. The market capitalization of the Tether stablecoin is $82 billion, whereas PayPal holds $39 billion of customer funds.

Yes, PayPal may have exponentially more staff and customers – 433 million active users compared to roughly 42 million Tether wallets if you count the 27 million on the Tron blockchain.  

In the first quarter of 2023 Tether reported a profit of $1.48 billion, almost twice PayPal’s. A proportion is Tether’s returns on relatively risky assets (for a stablecoin) such as Bitcoin, Gold and loans. A more conservative company would have earned closer to half that figure.

To put that in context, PayPal’s first quarter revenues were $7 billion and its net income was $795 million. Based on PayPal’s accounting notes and the level of customer funds, we estimate it earned around $400 million in interest on customer balances in the first quarter.

So if PayPal could build its stablecoin to half the size of Tether’s, at current interest rates, that could add another $400 million in interest before other stablecoin related revenues.

But that’s quite a big ask (in the short term), given that PayPal users currently have crypto balances of less than $1 billion.

Revenues beyond interest

During a CNBC interview (below), PayPal’s SVP and crypto leader Jose Fernandez da Ponte said that crypto was the initial target use case but also identified games and remittances as potential real world applications.

On gaming, Fernandez noted that stablecoins could shorten settlement times for merchants so developers won’t have to wait a couple of weeks for funds to clear. PayPal is eyeing the mainstream $100 billion games market, not just web3 games.

Turning to cross border payments, a recent analysis by FXC Intelligence shows that the proportion of PayPal cross border transactions have been falling for some time, and this is the most profitable segment because PayPal charges hefty margins on FX. I personally reduced usage of PayPal as I found the FX charges too steep.
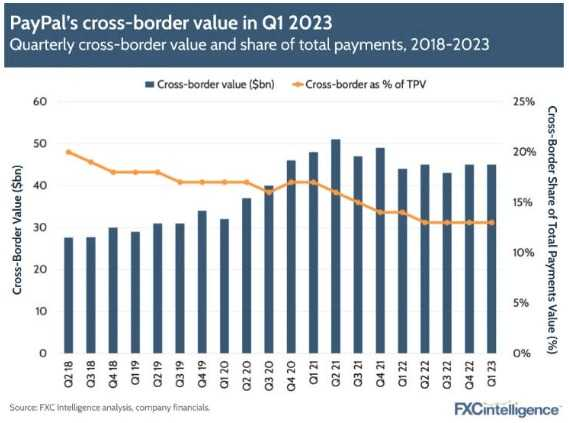
Remittances are definitely a use case for stablecoins. But the true benefits can only be reaped if FX margins are narrower than PayPal charges. Otherwise there’s no comparative advantage. We’re assuming remittances will only kick in once PayPal deploys its stablecoin to blockchains with more affordable transaction costs compared to Ethereum.

Why Ethereum?

PYUSD hasn’t yet launched in earnest, but one of the test transactions in the past couple of days involved a transfer of $2.50, which cost more than $3 in Ethereum gas fees. And that’s on a good day for fees. We can think of a couple of reasons why Ethereum would be the first launch target.

Firstly, Fernandez said that the crypto ecosystem is the initial target market, and for high value transactions, a $3 or $10 gas cost is not that big a deal.

The second reason is speculation – it could be that PYUSD is only authorized for issuance on Ethereum.

The stablecoin partner is Paxos, the New York (NYDFS) regulated trust company. Paxos deserves credit for its role in continually raising the bar on stablecoin reserve quality that others have followed.

Paxos also operates the Binance USD (BUSD) stablecoin and earlier this year, when we asked it about the BUSD pegged stablecoins that Binance issued on other chains, this is what Paxos said: 

“The NYDFS must approve our BUSD operations, including the blockchains on which BUSD tokens may be listed,” Paxos told us via email. “Today, BUSD is approved for issuance only on Ethereum. Paxos is not involved in the management or support of wrapped versions of BUSD.” 

We asked Paxos whether PYUSD is authorized on other blockchains, but didn’t receive a response in time for publication.

By only permitting issuance on Ethereum, NYDFS is potentially limiting the audience to crypto users and throttling mainstream usage at this stage. But that strategy is a risky one. Because one of the biggest risks is wrapped stablecoins, where someone else locks an amount of PYUSD on Ethereum and matches the issuance on another chain. 

Stablecoin KYC 

The problem with wrapped coins is the core stablecoin issuer has far less control and influence, especially over transfer restrictions and KYC. 

Theoretically, if one had a policy of not supporting wrapped stablecoins, you could warn anyone wrapping them that the coins will be frozen pending redemption (burning and refunding fiat currency). We also asked Paxos about the policy on wrapping.

The crypto community seemed to be up in arms about PayPal’s ability to freeze accounts, something that other stablecoins such as Tether and USDC also do.

KYC is one of the major unanswered questions. Will an established institution like PayPal really let its stablecoin transfer out of its walled garden with no safeguards?

Again, PayPal’s Fernandez told CNBC that he expected the stablecoin to be available at “exchanges, wallets, Dapps”.

We wondered about that from a KYC perspective. Because most wallets are traceable back to an onramp, so they’re not really pseudonymous. But some wallets are harder to trace. PayPal was an early investor in blockchain intelligence firm TRM Labs, so it could monitor transactions that use its stablecoin.

If remittances are a use case, it will eventually run into banking regulations – PayPal’s European operations are run as a bank in Luxembourg. While European stablecoins might not require KYC for small transactions with self hosted wallets, anything involving a bank would likely need to comply with banking regulations.

When asked about the advantages PayPal brings to the stablecoin party, Fernandez said there were three things. It has a massive two sided network, provides a linkage to the fiat currency world, and has a regulatory and compliance track record of almost 25 years.

Circling back to the headline. We suspect there isn’t a huge risk to PayPal – at this stage – because it’s likely to take it slow, which might not be it’s own choice. “It’s going to be a process in that we are on the way towards mainstream adoption, but I don’t think you’re going to be paying at your neighborhood store with a stablecoin any time soon,” said Fernandez da Ponte.

But the financial upside is pretty significant.
Link


community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
Ripple President Monica Long announced the use of XRP-POOLS 🤯

Ripple President Monica Long announced the use of XRP-POOLS to leverage XRP as collateral for funding customers’ payments from credit card institutions.

We are talking here about TRILLIONS of DOLLARS on the XRP-Ledger!

OP: Jacktherippler

00:00:28
🔥 Interview With Jacob "Const" Steeves, Co-Founder of Bittensor 🔥

Insane Interview Jacob "Const" Steeves (@const_reborn), Co-Founder of Bittensor and CEO of Affine, for an deep dive into what's coming next for Bittensor! 🧠⚡️

From fighting the AI cabal and competing with frontier labs to revenue models and Gamma Tokens—we covered it all. 🔥

⏱️ Timestamps:

0:00 Meet Jacob "Const" Steeves 👋
0:27 Fighting the AI Cabal 🛡️
8:40 Competing With Frontier Labs ⚔️
11:02 Templar's Departure & Teutonic 🏛️
15:44 Research, Revenue & Gamma Tokens
21:31 What's Next for Bittensor? 🔮

Catch the full conversation below! 📺👇

00:23:20
🪙 Is a Gold-Backed Dollar Making a Comeback? 🇺🇸🟡

The global financial landscape could be on the verge of a historic pivot. The U.S. Treasury has reportedly hired economist Judy Shelton—a vocal advocate for a gold-backed currency for three decades—sparking intense speculation about the future of the monetary system. 📈📉

The Core Proposal & Historical Context 📜⏳

🔹 The Shelton Plan: The proposed mechanism involves issuing a Treasury bond that holders can redeem for either U.S. dollars or physical gold.

🔹 A Nod to the Past: This exact promise was standard on U.S. war bonds until 1933, when Congress ultimately suspended convertibility during the Great Depression. 🏦💵

The Global Gold Rush 🌍🏦

🔹 The Biggest Stack: The United States currently holds 8,133 tonnes of gold—the largest reserve on the planet.

🔹 Global Accumulation: Central banks worldwide are stacking gold at an unprecedented rate. For instance, China has aggressively purchased gold for consecutive months, and ...

00:02:45
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading
Everyone Should Be Backing Up Their Data Using Encrypted Blockchain 😉

Everyone should be doing this, as it encrypts your data on blockchain secured by a private key. I would also recommend signing in with Github vs Google. Don't have a github account? Go create one, its free and can be secured by 2FA. Your data is valuable, secure it as you would silver/gold etc...

🚀 Check out Hippius, distributed cloud storage, Get 10 FREE Gigabytes Of Cryptographically Encrypted Data Storage

Encrypted Drive, S3-compatible storage with no egress fees, and Hippius Hub for all AI models.

https://rebrand.ly/hippius

⚠️ Note: You can create an account for as many emails as you want and get as many 10GB accounts as you want. Why pay Google or Amazon for "CENTRALIZED" storage. This is 100% encrypted storage that you control with a private key built on the Bittensor blockchain.

post photo preview

⚡ Seby Rubino explains how Instant (SN46) is building accelerated inference and tokenized GPU financing ⚡

In Ventura Labs Episode 101, Seby Rubino discusses Instant’s strategy for high-speed AI inference, miner collateral, privacy, hardware access, tokenized GPU lending, and the shift from research-driven subnets toward revenue-producing businesses.

🔑 Key points

🔹 Bittensor requires resilience: Rubino discusses the highs and lows of building in the ecosystem while filtering noise and staying focused on execution.

🔹 Token equity and subnet tokens differ: Equity represents company ownership, while subnet tokens coordinate the economic activity of a decentralized production network.

🔹 Instant evolved through multiple ideas: The project moved from earlier concepts involving residency and ZIP-code data toward accelerated inference.

🔹 Emissions must be monetized: The long-term goal is converting miner emissions and infrastructure into revenue-generating AI services.

🔹 Nova illustrates the ...

post photo preview

🎬 Theta EdgeCloud adds ByteDance’s Seedance 2.5 and BytePlus frontier models 🎬

Theta EdgeCloud is integrating BytePlus’s generative AI portfolio, led by Seedance 2.5, giving developers access to ByteDance models for video, images, audio, language, and multimodal applications.

🔑 Key points

🔹 Seedance 2.5 is the headline model: It supports text, image, video, and audio inputs while generating audiovisual clips of up to 30 seconds.

🔹 Reference assets are supported: Creators can provide up to 50 reference assets and control subjects, motion, composition, camera direction, and audio.

🔹 Video editing is included: Seedance 2.5 supports video extension and targeted editing.

🔹 Seedream 5.0 Pro is also available: The model supports image generation and editing with controls for composition, consistency, materials, color, and text rendering.

🔹 Broader BytePlus models are included: EdgeCloud developers can access video, image, language, speech, and multimodal AI through the same ...

September 13, 2026
post photo preview
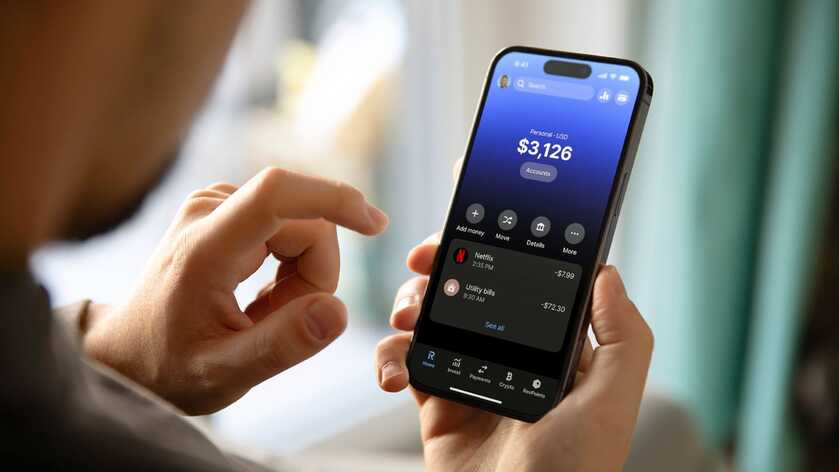
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
This Is The Income A Family Needs To Live Comfortably In Every US State

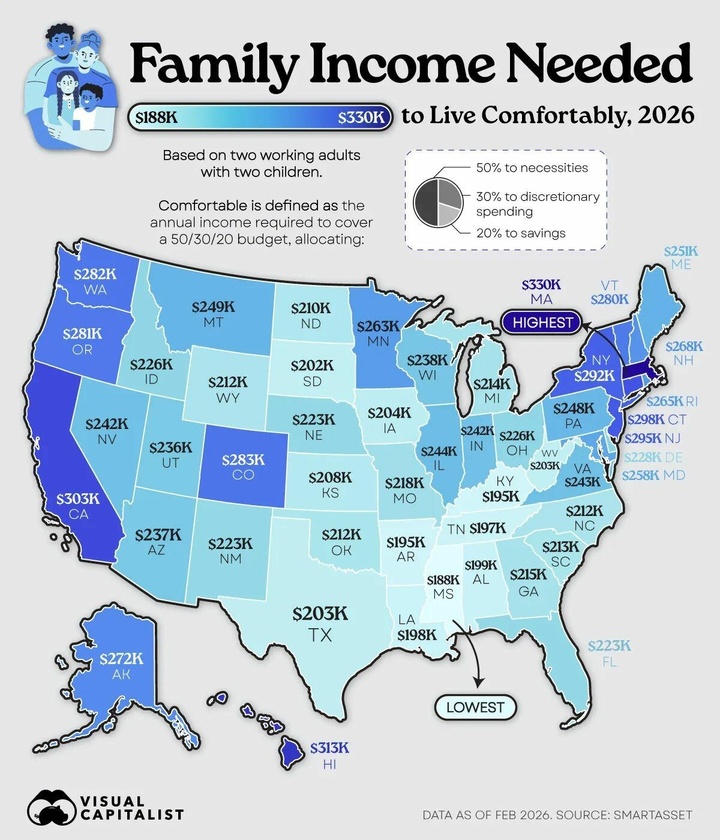
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

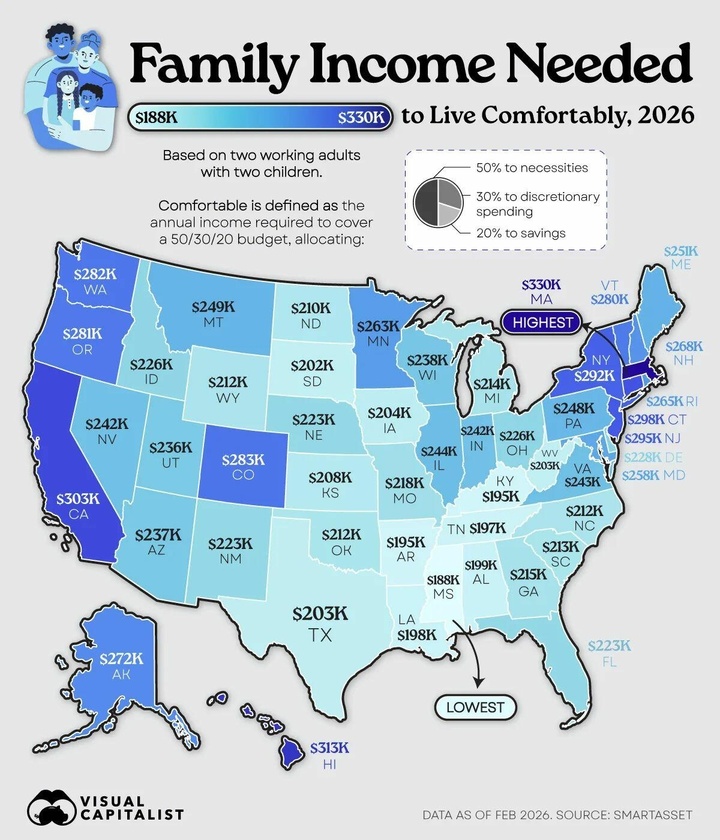
In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notes, Massachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals