We sat down with Luiz Henrique Didier Jr., the CEO of Bexs Banco, at Money 20/20 USA to discuss more about Bexs, its transition to Ebury, recent developments in Brazil, and the company's future goals.
Could you tell us a bit about Bexs, and what problems do you solve for whom?
Bexs initially started out as a foreign exchange brokerage in 1989 and later acquired a bank licence in 2010. This was a significant shift because the bank licence enabled us to fully digitalise FX in Brazil at a scale.
In Brazil, less than 20% of credit cards are authorised to make international purchases. This meant that most Brazilian shoppers could not shop on international ecommerce platforms like AliExpress. We provide a solution to these platforms which converts foreign currency to BRL, facilitates the BRL payments with local methods, as well as handles the FX while eliminating the exchange rate risk, especially given the volatility of the BRL. This helped international merchants sell products to Brazilians without complicating the payment process.
We also applied the same approach to investment, as a large percentage of Brazilians believed it was illegal to invest abroad. However, when conducted in compliance with regulations, investments abroad are possible. Therefore, Bexs helps in digitalising investments, together with our partner Avenue, a US-based brokerage offering direct investments in Nasdaq. We also work with neobanks such as Revolut or Nubank, allowing Brazilians to have wallets in different currencies like USD, GBP or EUR. Bexs helps facilitate the FX transactions in this process.
In essence, we consider Bexs to be an international payment platform with a bank licence. This licence enables us to operate without limitations on transaction volumes, while still complying with Brazilian regulations.
Congratulations on receiving the approval from the Central Bank of Brazil regarding Bexs’ acquisition by Ebury. What would you say is the main value of this acquisition for both Bexs' and Ebury's customers and partners?
The approval from the Central Bank of Brazil for Bexs' transition to Ebury is a big deal on both sides. The value of the acquisition is two-fold.
First, it makes processes much easier for Brazilian companies to do business outside Brazil. Brazil has been restrictive when it comes to moving money in and out of the country, due to the complexity of opening bank accounts in other countries. With this transition to Ebury, we would be able to offer multicurrency accounts worldwide with an integrated FX platform through a single onboarding process for Brazil and the other Ebury entities outside the country.
The second major value this acquisition brings is the ability to offer non-resident accounts to international companies looking to establish a presence in Brazil. To offer a non-resident account to international merchants or SMEs in Brazil, you typically need to be a Brazilian bank with a licence to operate in the country. But with Ebury, we are able to make this process simpler. Once a client is onboarded with Ebury, we can leverage the same onboarding to offer them a non-resident account in Brazil. Bexs would then be able to offer the BRL as a convertible currency, which companies did not have access to until now.
So, in simple terms, this acquisition is valuable because it helps Brazilian companies and SMEs get access to multicurrency accounts abroad on a global scaleand it allows international businesses to open accounts in Brazil.
Can you tell us about a new trend or development in the digital payments space in Brazil and LATAM?
I think the answer to this would definitely be the introduction of Pix, as it was a game-changer for Brazil. What's particularly interesting about Pix, especially when compared to other similar systems, is how the Central Bank of Brazil designed it. It was made mandatory for all major banks, acquirers, brands, and major players in the payment industry to be part of the Pix ecosystem. Right from the beginning, Pix was built to be interoperable, meaning it could work with multiple financial institutions seamlessly, which led to its success.
Currently, the majority of Brazilians are already using Pix because it is instant and available 24/7. This ended up as a significant shift from the past when many people had to handle cash regularly for payments, even for small things such as buying a bottle of water. Now, however, they can make use of digital wallets linked to Pix for convenient transactions.
Pix operates by linking to your bank account, it is also safe because all transactions happen within the secure process of the bank's app. No one involved in the transaction has the full information of the user's account, except for the Central Bank of Brazil. This would make it more challenging for fraudsters to manipulate when compared to some other forms of digital payments.
There seems to be interest in adopting similar systems in other Latin American countries, however, it does require a combination of the public and private sectors working together. In Brazil, the public sector mandated Pix, and the private sector adopted it. I believe that the next step in Brazil is an expansion to all kinds of payment using the Pix ecosystem. Instalment payments, recurring payments, credit services, and more within the same ecosystem.
Looking back at 2023, what achievements or milestones of Bexs do you feel proud of?
Reflecting back, the best achievement of 2023 would be our contribution of allowing Brazilians to use Pix 24/7 to load their wallets, whether it's through partnerships with institutions like Nubank or Revolut.
In the past, when Brazilians travelled, we had to carry a lot of cash and make various arrangements for currency exchange. With Pix, however, it has become as simple as doing a transfer. So, if you find yourself in a place where you need to make a payment but do not have the local currency, you can do a Pix transfer to load money in Revolut or Nubank wallets. Through our partnership with these neobanks, we streamline the process, handling everything related to FX and enabling payments in the desired foreign currency.
Looking ahead, what are Bexs' strategic plans and priorities for future growth and development?
For me, this answer is simple. Bexs' priorities for future growth and development are around expanding our services to the B2B sector. We want to provide the B2B market with international accounts for non-resident international companies, which aligns well with Ebury's focus on FX for B2B.
We want to make the same convenience that Pix offers to individuals available for businesses as well. As I mentioned earlier, Brazilians in the past used to travel with just carrying cash. Now, they have access to another currency in their own account. The next step for us would then be to offer this to B2B, which is much more complex.
Currently, for businesses in Brazil, the process of conducting cross-border transactions can be quite complex. It involves lengthy onboarding processes, KYC checks, and waiting for business days and hours to complete transfers. Our goal is to simplify this process, making it as efficient as the Pix system for individuals.
We want to make it easier for companies to conduct transactions 24/7, both within Brazil and internationally. We anticipate launching this at the beginning of next year.
According to CNBC, SEC Chair Paul Atkins is set to announce NEW crypto rules this Friday! ⚡️🇺🇸
Here is what’s on the horizon for the digital asset space:
🔹 Project Crypto Unleashed: The SEC is moving forward with a dedicated framework for crypto assets, transfer agent updates, and adviser custody guidelines.
🔹 Regulatory Clarity: After years of uncertainty, official rules of the road are finally arriving for token issuers, exchanges, and institutional investors.
🔹 Moving Independent of Congress: Whether or not legislative bills like the CLARITY Act pass, federal regulators are taking direct action to build a modern market architecture.
This could mark a massive turning point for innovation and compliance in the U.S. crypto industry! 🚀📊
Will this ignite the next market rally? Drop your predictions below! 👇🔥
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.
🔑 Key points
🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.
🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.
🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.
🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.
🔑 Key points
🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.
🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.
🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...
👉 Coinbase just launched an AI agent for Crypto Trading
Custom AI assistants that print money in your sleep? 🔜
The future of Crypto x AI is about to go crazy.
👉 Here’s what you need to know:
💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit
👉 What this means for the future of Crypto:
1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025
🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.
👉 Coinbase just launched an AI agent for Crypto Trading
🤖 How Bittensor SN61 RedTeam is building an autonomous cybersecurity immune system 🛡️
Cybersecurity has always been a constant cat-and-mouse game—until now. By incentivizing miners to discover novel ways to break bot detection, device fingerprinting, and geolocation systems, RedTeam transforms attacker ingenuity into fuel for an adaptive defense network.
Every exploit submitted becomes an input into an autonomous "immune system" that:
🛠️ Reverse-engineers miner techniques
🔍 Identifies the underlying exploit
🧬 Generates new attack variants
🛡️ Develop realtime detection mechanism
In this deep dive, Oscar and Javokhir unpack how RedTeam evolved from manually breaking competing security products into a commercial cybersecurity platform now protecting over 125 million daily active users across its customer base. 🚀
🏦 Three Fortune 500 banks reportedly enter RedTeam’s cybersecurity pipeline 🏦
RedTeam (SN61) says three Fortune 500 banks are now in its commercial pipeline, signaling growing interest in its AI-driven approach to adversarial security testing.
🔑 Key points
🔹 Three major banks are evaluating RedTeam: The institutions are reportedly considering SN61 for fraud detection, bot defense, device intelligence, and security testing.
🔹 Pipeline is not revenue: Being in a sales pipeline does not mean the banks have signed contracts or deployed the product.
🔹 RedTeam attacks detection systems: Its network of security researchers and miners searches for ways to bypass fraud and identity protections.
🔹 AI agents expand testing: Automated systems can generate and test attack variations faster than traditional manual security teams.
🔹 Financial institutions are high-value targets: Banks face constant threats involving bots, account takeover, synthetic identities, credential theft, and payment fraud.
🚀 Bittensor Subnet 78 (SN78): UMI AMA Highlights! 🌐✨
Subnet 78 transitioned into UMI (Universal Motion Intelligence) — building AI that bridges human physical motion, expression, and meaning! 🤖👋
🔑 Key Takeaways from the AMA:
🌊 What is UMI?
UMI stands for Universal Motion Intelligence (and "Umi" means ocean in Japanese 🌊).
It moves beyond text and voice to train AI on complex human movement, gestures, and facial expressions.
🤟 Solving Sign Language Translation First
UMI is tackling American Sign Language (ASL) to voice/text translation. Beyond hand shapes, UMI captures facial expressions, body language, spatial relationships, and temporal context over time.
📱 BitSign (First Commercial Product): Launching BitSign (bitsign.ai) to deliver accessible two-way translation. Multi-tiered rollout: From everyday iOS apps to medical-grade (HIPAA & ADA compliant) solutions for healthcare, banking, and retail.
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.
Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.
The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.
Revolut claims that derived biometric face data was not.
The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.
The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.
Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.
Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.
Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.
The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.
The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.
One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.
This means that even if you close your account, your identity documents don’t disappear.
And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.
This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.
It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.
The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.
This Is The Income A Family Needs To Live Comfortably In Every US State
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:
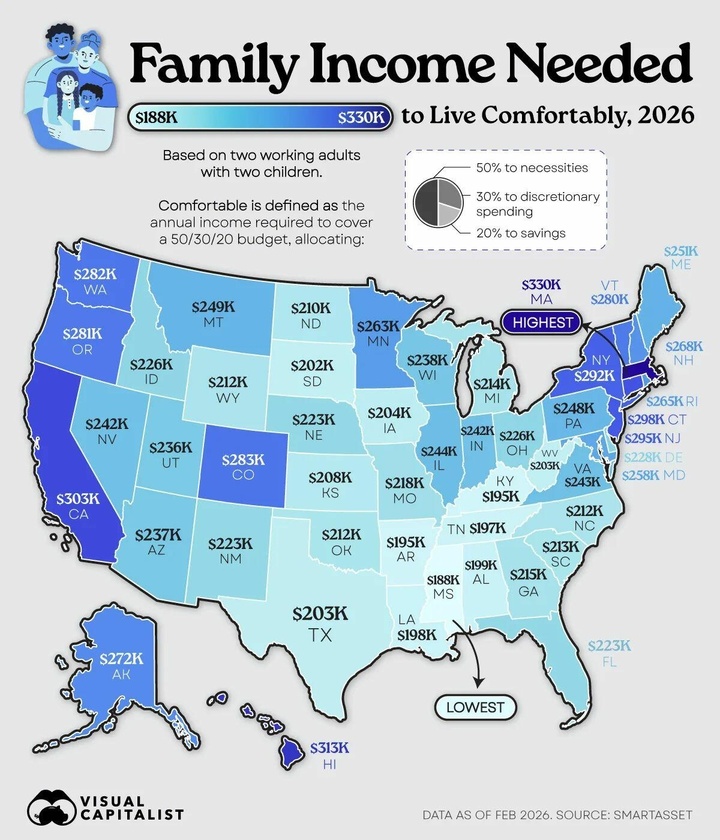
In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.
So… how much does a family of four need in your state?
This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.
The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.
And asVisual Capitalistnotes, Massachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.
Hawaii follows at $313,165, while California ranks third at $302,682.
Rank State Income needed for family of four (2026)
1 - Massachusetts - $329,555
2 - Hawaii - $313,165
3 - California - $302,682
4 - Connecticut - $298,189
5 - New Jersey - $295,110
6 - New York - $291,533
7 - Colorado - $283,213
8 - Washington - $281,798
9 - Oregon - $280,966
10 - Vermont - $280,384
11 - Alaska - $272,064
12 - New Hampshire - $267,904
13 - Rhode Island - $264,659
14 - Minnesota - $263,078
15 - Maryland - $257,837
16 - Maine - $250,931
17 - Montana - $249,434
18 - Pennsylvania - $247,936
19 - Illinois - $244,109
20 - Virginia - $242,944
21 - Nevada - $242,278
22 - Indiana - $241,696
23 - Wisconsin - $238,451
24 - Arizona - $236,870
25 - Utah - $235,789
26 - Delaware - $228,134
27 - Ohio - $226,221
28 - Idaho - $226,054
29 - Florida - $223,392
30 - New Mexico - $223,142
31 - Nebraska - $223,059
32 - Missouri - $217,734
33 - Georgia - $214,573
34 - Michigan - $214,323
35 - South Carolina - $212,909
36 - North Carolina - $212,410
37 - Wyoming - $212,410
38 - Oklahoma - $211,910
39 - North Dakota - $210,496
40 - Kansas - $207,917
41 - Iowa - $204,422
42 - Texas - $203,424
43 - West Virginia - $202,592
44 - South Dakota - $201,760
45 - Alabama - $198,931
46 - Louisiana - $197,933
47 - Tennessee - $197,267
48 - Arkansas - $195,437
49 - Kentucky - $194,854
50 - Mississippi - $187,533
Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.
Colorado and Vermont Make the Top 10
As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.
However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.
Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.
Just Six States Come in Below $200,000
Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.
Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.
The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
Now that AI is moving into the physical world, many are asking a bigger question:
Will these same companies end up controlling robotics too?
It's a valid concern.
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
That movement is decentralized AI.
Why Decentralized AI Exists
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
Why This Matters for Robotics
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
This is where decentralized systems become interesting.
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
Imagine a future where:
Warehouse robots contribute operational data.
Delivery robots contribute navigation data.
Factory robots contribute manipulation data.
Developers contribute models.
Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
That vision is beginning to emerge.
Bittensor's Move Toward Physical AI
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
In other words, the pieces are starting to appear.
Not a decentralized robot network yet.
But the infrastructure that could support one.
Beyond Bittensor: The Rise of Physical AI Networks
Bittensor isn't alone.
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
The goal is not simply decentralization for its own sake.
The goal is resilience.
If one server fails, the system continues.
If one company disappears, the network survives.
If one participant leaves, innovation continues.
But Here's the Reality
Decentralized AI faces the same challenge every decentralized technology faces.
Big Tech has resources. A lot of resources.
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
The challenge isn't just decentralizing intelligence.
It's decentralizing intelligence while maintaining performance.
That's much harder.
The Most Likely Outcome
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
The companies building robots may use NVIDIA hardware.
Train on Azure.
Run foundation models from OpenAI.
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
The Bigger Question
The real question isn't whether decentralized AI can eliminate Big Tech.
It can't.
At least not anytime soon.
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
Because the battle for the future of robotics is no longer about hardware.
Sign Up for free to see more from this community or subscribe to Dinarian888 for $5/month to support Dinarian888 for more interaction and exclusive content.
Welcome to the Dinarian on Locals, where we discuss everything blockchain and digital asset related. We are here to learn from one another as this is a new and ever evolving space. Please post and share what you like, but be respectful to others as they are here to learn as well.
Knowledge is power, using that knowledge can be extremely powerful,
The Dinarian