Dinarian888
News • Business • Investing & Finance
From PoC To Production: FIs Lead The Way With Tokenized Real World Assets
(Forbes)
November 18, 2023
post photo preview

This week, the digital assets autumn conference season saw Digital Asset Week (DAW23) come to London following fixtures in San Francisco and Singapore. The conference brought together leading global financial institutions and their later stage fintech partners, to announce the launch of the next wave of production digital assets applications for financial institutions (FIs).

Top tier players from JP Morgan, BNY Mellon, Standard Chartered, BlackRock, Invesco, UBS, BNP Paribas, Deutsche Bank, Goldman Sachs, State Street, SocGen, ABN Ambro, Citi, and Mastercard laid bare their playbooks for moving from proof of concept (POC) to production applications.

The launch pad has a steady stream of new digital assets apps moving into production from FIs furnished by their fintech partners from Ownera, Archax, Digital Asset’s Canton Network, TomNext, LRC, Consello Digital, HQLAx, Arta, LRC, Tokeny, Invenium, and many others.

This is what we learned.

The Offense Playbook: Liquidity Liquidity Liquidty

It’s all about liquidity: delivering better, faster, cheaper products to clients enabling greater and more liquid markets - the mobility of assets, collateral, and markets. Capital and operational efficiency is at the top of the list with products that improve balance sheet, treasury and collateral management driving lower prices, decreasing bid offer spreads, and reducing expenses.

Expect more over the coming months on “vanilla products” like the tokenization of ETFs, money markets, securities lending, and repo. Also continuing its run is the tokenization of fixed income where there is a lot of variation driving middle and back-office efficiencies gained through the transformation to digital assets.

The tokenization of precious metals and property are lining up, and the tokenization of private markets is coming back into focus after a lull for a few years, driven by higher interest rates -watch these spaces for early breakthroughs.

Private protocols and networks will lead for institutional real-world digital assets, public protocols may not stand up to scrutiny of the many jurisdictional laws and regulations, for a range of reasons.

As FIs build out on the “new rails”, don’t expect the “old rails” to disappear quickly. It took nearly 50 years for automobiles and tractors to displace horses on U.S. farms, Netflix hasn’t killed the cinema yet, you get the picture.

T0 (T Zero) settlement is a bit of a misnomer as the sector heads down the path of accelerated settlement times thanks to DLT – the new tech can do it, but most heritage products, businesses, tech, and some people can’t.

FIs are focused on “atomic settlement” occurring when and with the precision needed in the settlement window to meet clients and counterparty requirements. There are as many valid commercial reasons for T+settlement for fiduciary controls and assurance across products and services, as there are reasons for the new T0 ones.

2024 is pitted as the year to keep heads down and move more digital financial market infrastructure (dFMI) and digital assets into production with greater scaling and adoption forecast for 2025 and beyond.

Buy Side education is at the top of the list for many. Ultimately, it is not about tokenizing real world digital assets, it’s about how easy it is to buy and sell great new products that make you or save you more money than the products you are buying or selling now.

The Defense Playbook: Show Me The Money

There are barriers to scaling digital assets into mature marketplaces and digital money is the first real one. Cash on ledger is the killer app that delivers a digital currency on the internet, the fiat on and off ramp for digital assets, and an enabler for the execution of atomic instructions.

Deposit tokens and institutional settlement tokens will lead here as most FI’s cannot wait for (wholesale) CBDCs. However, some remain mildly optimistic over the medium term, that commercial and viable CBDC solutions may make it to market. Stablecoins are rarely a consideration for the non-retail markets.

Digital asset asset servicing, custody, and settlement remain the Gordian Knot of scaling digital asset markets. Central security depositories (CSDs), central records of account, end of day accounting, and delivery versus payment (DVP) are just some of the areas that will need to be digitally redesigned for DLT. The opportunity to add yield to custodied monies money could accelerate this.

Protocol interoperability is the biggest friction point for greater digital assets scalability and true mobility across digital markets. No one wants to see their digital assets stranded on token island in a walled garden franchise. Protocol level interoperability standards are required for all digital asset classes, and not just digital securities, and are required now.

The Players Out In Front

Ownera, TomNext and Archax have launched a Money Market Fund, distributed via the Archax digital platform, across the Ownera FinP2P network in token form. Through the TomNext software, clients can access yield bearing money market funds intraday, enabling investors to benefit from tokenized access to this asset.

“Gone are the days of the proof of concepts” says Graham Rodford, Archax co-founder and ceo,


“We are now moving into production with several innovative projects which will start to demonstrate why we have been talking about this technology when applied to real world assets for over five years”.

JP Morgan, Ownera, HQLAx, and wematch.live will launch the world’s first intraday repo trading product supporting DVP transactions across DLT in January 2024. Traders can negotiate the exchange of securities with cash held at JP Morgan and settlement and maturity times can be negotiated to the minute. Interest is only accrued for the duration of the repo contract rather than overnight.

“The full potential of the intraday repo market cannot be realized unless capital can be swiftly deployed to meet changing intraday requirements and settlement times can be reduced to lower counterparty risk,” says Anthony Woolley, head of business development at Ownera,


“We now have leading companies such as HQLAx that are able to mobilize digital collateral and major banks with forms of digital cash such as JPM Coin.”

Digital Asset’s Canton Network has engaged several leading FIs with production applications across fixed income, repo, collateralized lending, and deposit tokens in a pilot with over 40 institutions to help scale production digital asset use cases and further develop interoperable standards for digital assets across different DLT protocols. The pilot will report out early in the New Year.

Yuval Rooz, co-founder and ceo of Digital Asset says, “Since the introduction of Canton Network earlier this year, we have witnessed tremendous engagement from global market participants. The pilot program has demonstrated the demand for interoperability for regulated institutions. For the first time, there is an open blockchain network that provides the privacy and control essential for financial markets, coupled with the interoperability and scalability necessary to maximize the technology's potential."

Larry Fink of BlackRock said in March that tokenization will be "the next generation for markets," and fired the starting gun. In October JP Morgan's Onyx launched the Tokenized Collateral Network (TCN) with BlackRock tokenizing shares in a money market fund and pledging them as collateral with Barclays for a derivatives contract.

Citi recently launched two digital asset Tokenized Deposits solutions under the umbrella of “Citi Token Services” targeting institutions, one enabling organizations to send tokenized money between Citi branches worldwide and 24/7, the other providing smart contract based bank guarantees for global trade.

Euroclear has just announced digital bond issue a year on from issues from UBS and Six Digital Exchange and the EIB Bond issue involving Goldman Sachs, SocGen, and Santander. Euroclear has also launched its Digital Securities Issuance service facilitating the issuance, distribution, and settlement of fully digital international securities.

HSBC has launched tokenized ownership of physical gold on DLT that is held in its London vault that can be traded between HSBC and institutional investors on its Evolve platform. HSBC has also entered the digital asset custody market using technology from digital custody firm Metaco, joining BNY Mellon, and Standard Chartered’s Zodia in the digital custody race.

DTCC recently acquired Securrency in the U.S. to bolster its digital asset custody services while Copper acquired Securrency’s business in the Emirates, further heating up the competition in the market for digital asset securities servicing.

Goldman Sachs led the latest $95 million funding round for U.S. based Fnality with BNP Paribas, DTCC, Euroclear, Nomura, and WisdomTree signaling the importance of settlement tokens.

"Fnality’s application of blockchain technology offers a resilient way for institutions to use central bank funds across a wide set of potential use cases, including instantaneous, cross-border, cross-currency payments, collateral mobility and security transactions," said Mathew McDermott, Goldman's global head of digital assets.

The U.K Rules Officials And Referees

London is a global financial center, and the talk of the conference was around how (global) FIs, highly experienced with regulated securities, are mostly clear about how to deliver tokenized digital assets within jurisdictional securities regulations. However, reducing the friction points on the old rails while moving to the new rails is at the top of the agenda for most of the front line players.

Solutions to some of these friction points will be able to be tested in the new Digital Securities Sandbox to be launched by HM Treasury in the first quarter of 2024. The sandbox is intended to be a safe testing ground for new DLT based financial market infrastructure to help to determine if exiting securities legislation or regulations require revisions to principles to better reflect the enhanced capabilities offered by new blockchain and digital technologies.

The Financial Conduct Authority (FCA) has signaled its doors are open to FIs and fintechs and is encouraging a greater dialogue with industry on digital assets and securities regulations. This is a welcome signal and one that the sector is hopeful will usher in a new era of (more) open collaboration with regulators, including cross border collaboration on digital asset trade and settlement.

As the digital space race heats up in financial services, the U.K. is doing everything it can to maximize its strength as a global financial services center and fintech hub, to attract FIs and dFMI in the race to become a premier global hub for digital assets.

With the new Financial Services and Markets Act and the Electronic Trades Document Act, also know as the blockchain bill that doesn’t mention blockchain, the U.K. Government has demonstrated it can pass progressive digital legislation at breathtaking pace.

A new Digital Assets Bill is on its way and will enshrine digital assets as new category of property, composed of electronic data, in law with the legal rights of property ownership.

Lord Holmes of Richmond, in his keynote address to delegates at Digital Assets Week London, summed up the U.K. Government’s contribution to the digital space race saying, “The Electronic Trade Documents Act clearly demonstrates how the U.K. can effectively legislate for the opportunities of our new technologies. We can develop this approach with the draft Digital Assets Bill, similarly, drafted by Professor Green and her excellent team at The Law Commission.


“This incremental, pacey approach to technology neutral and technology future proofed legislation, will enable citizens, companies, cities and the whole of the country to gain optimum advantage from the U.K.’s unique combination of its financial services ecosystem, new technologies businesses, and our great good fortune of English common law.”
Link

community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
🚨IT'S OFFICIAL: The Florida legislature has approved the ABOLITION of statewide PROPERTY TAXES.🔥
00:00:25
September 22, 2026
They Are Making It Easier And Easiet For The Average Joe To Trade 😉

X partners with crypto and stock exchanges to allow trading from the timeline.

•GGeiin
•Kraken
•Moomoo
• Coinaas

00:00:40
September 22, 2026
Bill Gates just said we may have to suffer a “BIG CYBER ATTACK”

Bill Gates just said we may have to suffer a “BIG CYBER ATTACK” before we “respond as fully as we should” to AI.

That sounds like a threat to me.

AI false flag risk remains HIGH.

00:00:23
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading

⚙️ Bittensor runtime v468 completes Root Reborn with copy-trading and active basket yields ⚙️

Runtime v468 completes Bittensor’s Root Reborn upgrade, giving root validators greater control over subnet-token rewards earned by their stakers.

🔑 Key points

🔹 Automatic conversion changed: Previously, subnet rewards earned through root were automatically converted into TAO, creating regular selling pressure on subnet tokens.

🔹 Rewards now remain in baskets: Root rewards are held as subnet tokens inside validator-linked baskets.

🔹 Validators can manage baskets: They can move value between subnets, reduce positions, or hold part of the basket in TAO.

🔹 Copy-trading is introduced: Stakers’ rewards can follow the allocation strategy managed by their selected root validator.

🔹 Original TAO stake remains separate: The basket contains earned rewards, while the staker’s original TAO position remains distinct.

🔹 Stakers retain control: Users can claim rewards, switch validators, or leave ...

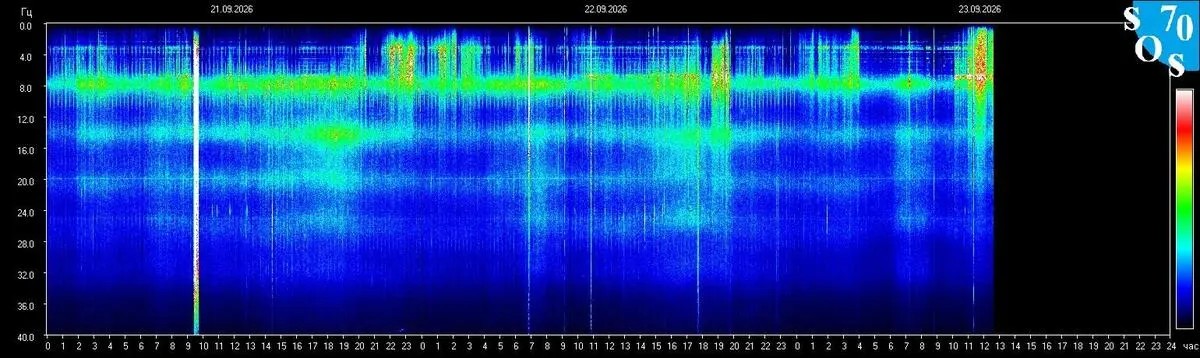
🌎 Schumann Resonance Today 9/23 🌎

Right now the Schumann resonance fundamental sits at 7.83 Hz, with geomagnetic activity quiet (Kp 2.0).

post photo preview

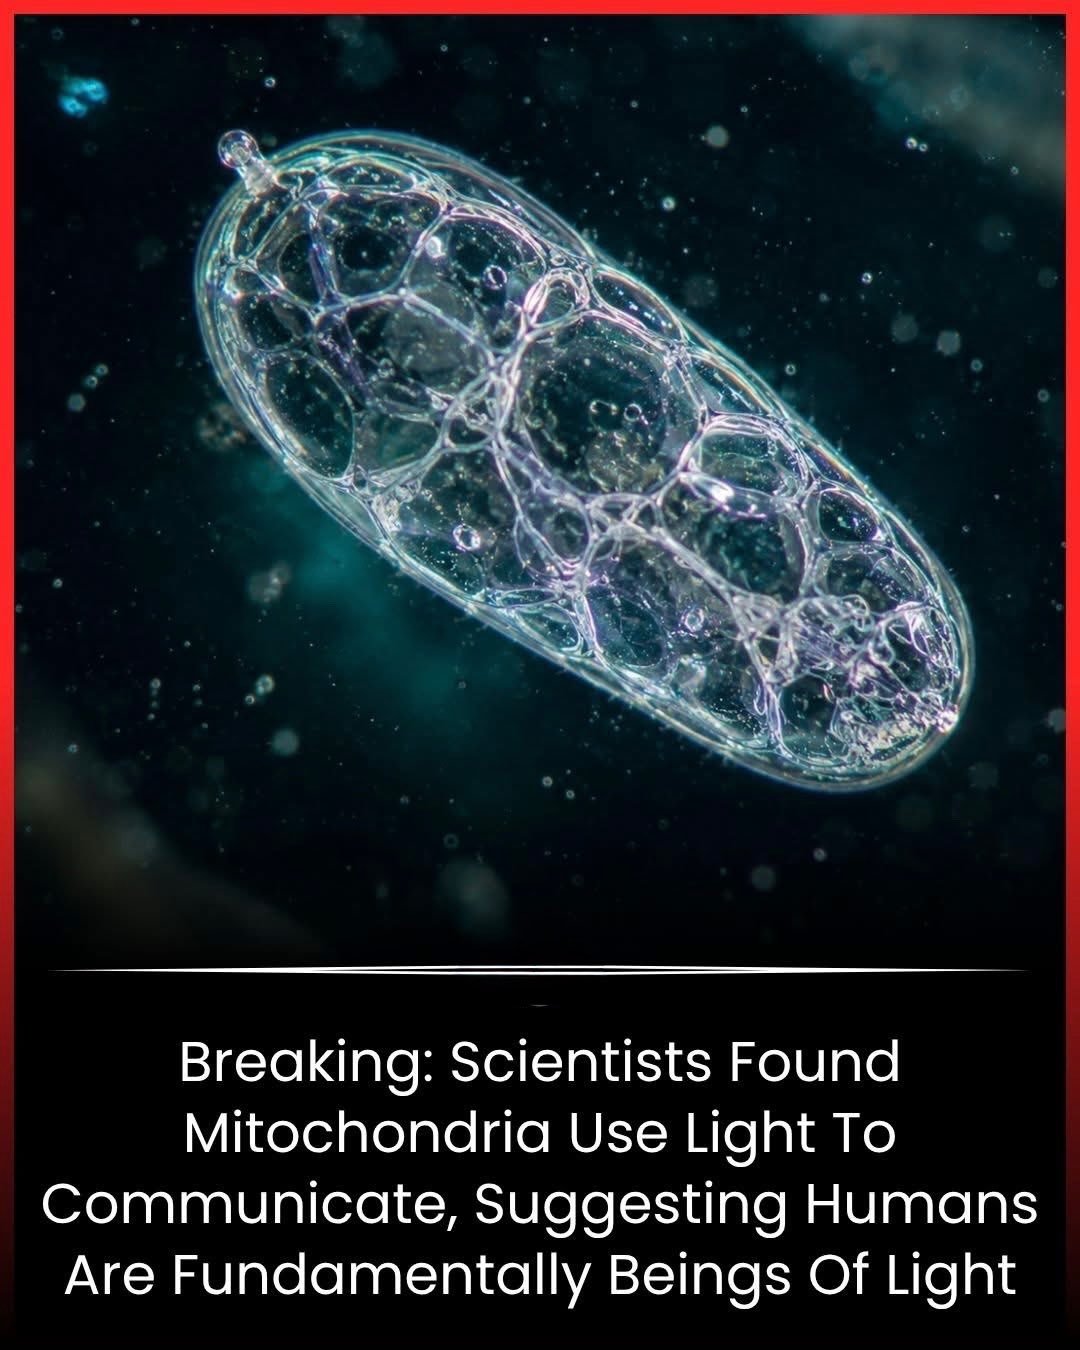
✨ Scientists study how living cells may communicate through light ✨

Researchers are investigating ultra-weak flashes of light, known as biophotons, that are produced inside living cells and may be connected to mitochondrial activity.

🔑 Key points

🔹 Biophotons are extremely weak light emissions generated by living cells.

🔹 Mitochondria are considered an important source because cellular energy production involves electron movement and oxidative reactions.

🔹 The emissions are invisible to the human eye and require highly sensitive photon-detection equipment.

🔹 Researchers are exploring whether biophotons may help coordinate activity inside cells or between nearby cellular structures.

🔹 Mitochondrial stress and metabolic changes may influence the intensity and pattern of these emissions.

🔹 Biophoton activity may be connected to cellular signaling, energy regulation, repair processes, and responses to environmental stress.

🔹 The research connects biology, photochemistry, mitochondrial...

post photo preview
September 13, 2026
post photo preview
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
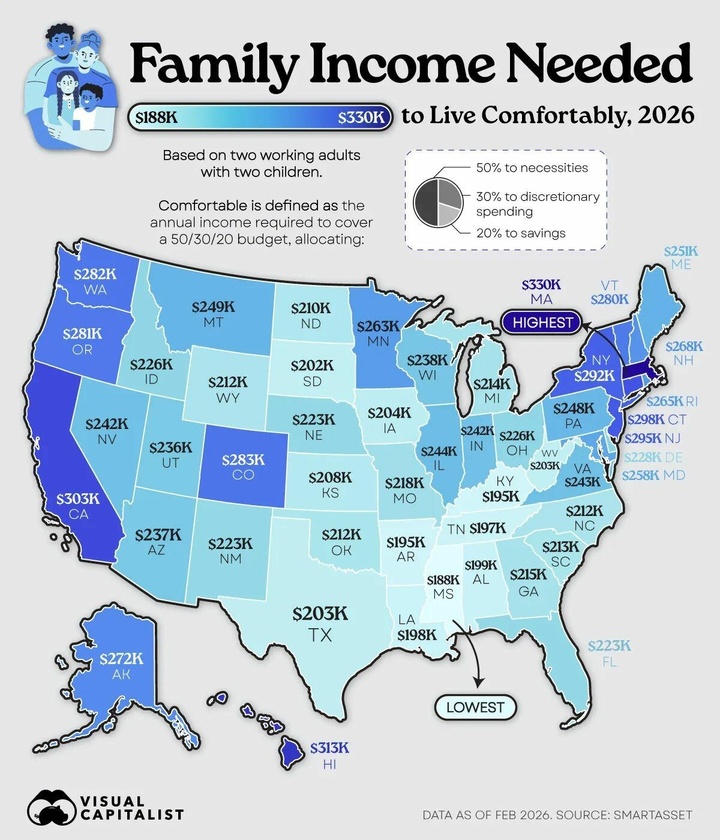
This Is The Income A Family Needs To Live Comfortably In Every US State

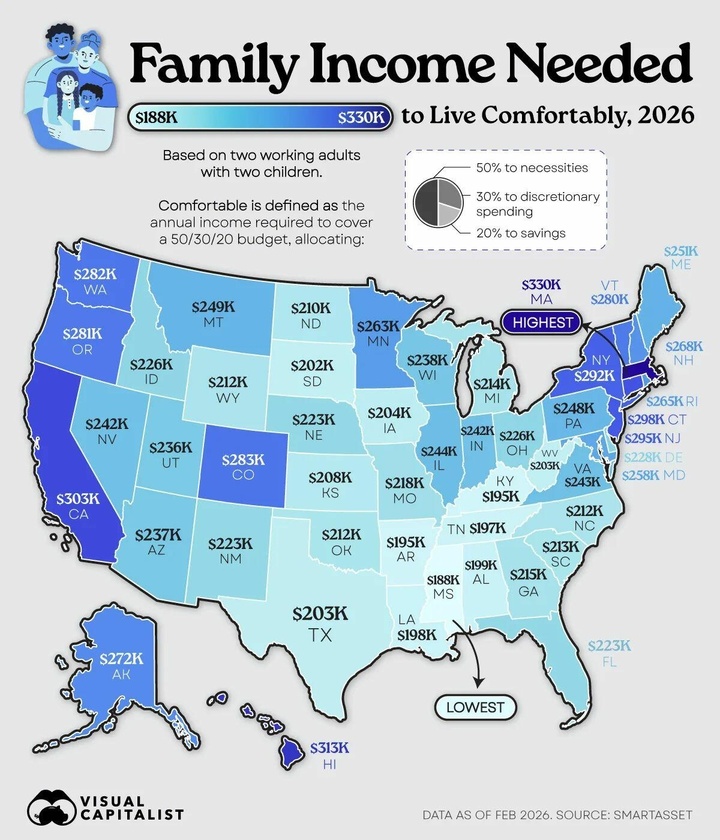
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notesMassachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals