Dinarian888
News • Business • Investing & Finance
BlackRock alters role of Coinbase among 6 changes to ETF filing to cover regulatory concerns
Coinbase transitions to Prime Execution Agent in BlackRock's latest iShares Bitcoin Trust ETF filing.
December 19, 2023
post photo preview

The recent amendment to the S-1 form for the iShares Bitcoin Trust introduces six substantial changes in the management and operational structure concerning its Bitcoin and cash holdings.

BlackRock’s last update introduced 21 core amendments; however, the Dec. 18 filing exhibits substantially fewer, potentially indicating final refinements before launch. The notable changes in the most recent filing are listed below:
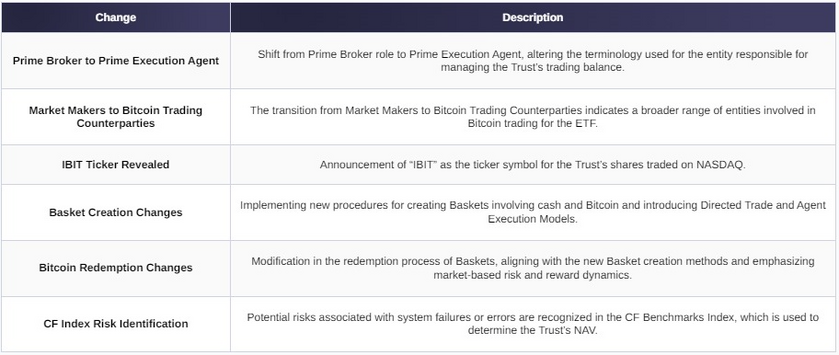
Prime Broker to Prime Execution Agent.

BlackRock introduces a shift in its operational strategy. The Trust has replaced the “Prime Broker” role with a “Prime Execution Agent,” signaling a restructured approach to managing the Trust’s trading balances for Bitcoin and cash assets.

A Prime Broker generally provides a suite of services that enable large institutions, traders, and hedge funds to implement their trading strategies at a cost. These services typically include cash management, securities lending, trade clearing, and settlement, among others.

On the other hand, an Executing Agent is a broker or dealer who processes a buy or sell order on behalf of a client. The executing broker within the prime brokerage will locate the securities for a purchase transaction or find a buyer for a sale transaction. This intermediary service is essential because a large transaction must be done quickly and at a low cost for the client.

The change in Coinbase’s role from Prime Broker to Prime Execution Agent suggests a potential shift in the perceived responsibilities that Coinbase will have concerning BlackRock’s ETF. As a Prime Execution Agent, Coinbase’s perceived primary role is to process buy or sell orders on behalf of the ETF rather than providing the broader range of services typically associated with a Prime Broker. However, much of the language in this section remains consistent with the last filing. Updating terminology to align with SEC guidance rather than introducing material differences is a trend seen across other filings, such as the language regarding a “direct exposure” to Bitcoin.

“Although the Shares are not the exact equivalent of a direct investment in Bitcoin, they provide investors with an alternative method of achieving investment exposure to Bitcoin through the securities market, which may be more familiar to them.”

Under the new Directed Trade Model (see Basket Creation Changes below) and the Agent Execution Model. This amendment delineates the cost responsibilities between the Trust and the Authorized Participants (AP), or their agents, the Non-AP Arbitrageurs, in scenarios where there is a discrepancy between the market price of Bitcoin and its value as calculated for the Net Asset Value (NAV) per Share of the Trust.

When an Authorized Participant, or a Non-AP Arbitrageur acting on their behalf, places a purchase order, they are now financially responsible for covering the difference if the price paid for acquiring Bitcoin is higher than the Bitcoin price used in the NAV calculation. This responsibility implies that any additional cost incurred due to a higher market price during acquisition falls on the Authorized Participant or the Non-AP Arbitrageur.

Conversely, if the Trust secures Bitcoin at a price lower than that utilized in the NAV calculation, the Authorized Participant or Non-AP Arbitrageur benefits by retaining the dollar value of this difference. This provision allows them to profit from favorable market conditions where the actual purchase price is less than the NAV-based price.

Similarly, for redemption orders, the financial responsibility model is mirrored. In cases where the Trust sells Bitcoin for less than the NAV-calculated price, the Authorized Participant or the Non-AP Arbitrageur is obligated to bear the cost difference. This arrangement places the risk of lower market prices during liquidation squarely on them.

However, suppose the Trust sells Bitcoin at a higher price than the one used in the NAV calculation. In that case, the Authorized Participant or Non-AP Arbitrageur again stands to benefit, keeping the surplus dollar value from this transaction.

This amendment introduces a significant risk-reward dynamic for Authorized Participants and Non-AP Arbitrageurs, aligning their financial interests with market fluctuations and the Trust’s NAV calculations.

Retained Responsibilities as Prime Execution Agent.

Under this new framework, the Trust’s assets are still subject to an omnibus claim rather than a direct claim on specific Bitcoin or cash. This approach, along with most of this section, is consistent with the previous arrangement and maintains the pro rata share system for asset entitlement.

Further, the Trust’s cash management strategy remains essentially unchanged, with continued use of bank accounts and Money Market Funds. When it comes to executing Bitcoin sales, the Trust will operate through approved trading venues, though specifics may vary under the new agent. The agreement also includes provisions for suspension or termination by either party under certain conditions, mirroring the clauses in the previous Prime Broker Agreement.

Regarding executing Bitcoin sales, the Trust will continue working through approved trading venues, a process similar to that the Prime Broker employs. However, the specifics of these venues and the due diligence process may differ under the new Prime Execution Agent.

This shift from a Prime Broker to a Prime Execution Agent suggests a reevaluation and possible enhancement of the operational structure for managing the Trust’s Bitcoin and cash holdings. However, many fundamental asset handling and risk management aspects remain consistent with the previous arrangement.

Market Makers to Bitcoin Trading Counterparties.

In another development, BlackRock has revamped the roles and compliance responsibilities within the ETF. The replacement of “Market Makers” with “Bitcoin Trading Counterparties” suggests a potential broadening of entities involved in Bitcoin trading and a more proactive approach to transaction execution.

Now, not only do Authorized Participants and Bitcoin Trading Counterparties need to have compliance programs for sanctions and anti-money laundering laws, but the Prime Execution Agent also has to maintain similar programs. This change highlights an increased focus on regulatory compliance and the prevention of illicit activities.

Furthermore, the Trust’s acceptance of Bitcoin is now explicitly extended to include those acquired through the Prime Execution Agent, in addition to those from Bitcoin Trading Counterparties. This broadens the sources from which the Trust can receive Bitcoin, potentially enhancing the Trust’s ability to manage its Bitcoin holdings more effectively.

Lastly, there is an emphasis on the Prime Execution Agent’s ongoing due diligence and monitoring responsibilities for its customers, including those related to Authorized Participants. This added layer of scrutiny is aimed at bolstering the Trust’s compliance with legal and regulatory requirements, particularly in relation to suspicious activities and transactions.

Basket Creation Changes.

BlackRock has introduced notable changes to its operational structure, particularly in how it handles the creation and redemption of its Baskets, which are the units of the ETF.

Previously, the creation of a Basket was solely dependent on delivering a specific amount of Bitcoin, which varied daily based on factors like sales of Bitcoin, losses, and accrued expenses. The Basket Bitcoin Amount was adjusted daily and made available to Authorized Participants. Now, the Trust has introduced a dual component: a cash amount and a Bitcoin amount for each Basket, reflecting a more complex structure. This change allows for a more flexible and dynamic approach to creating Baskets, accommodating both cash and Bitcoin in varying proportions.

This change introduces two new operational models for handling Bitcoin transactions within the Trust. The first is the Directed Trade Model, where the Trust engages with Bitcoin Trading Counterparties. These Counterparties, who are not registered broker-dealers, enter into written agreements with the Trust to trade Bitcoin. They may be affiliates of Authorized Participants or different broker-dealers known as Non-AP Arbitrageurs. In this model, the Bitcoin Trading Counterparties act in their own interest (in a principal capacity) when trading with the Trust. The second model is the Agent Execution Model. Here, the Prime Execution Agent conducts Bitcoin purchases and sales on behalf of the Trust, acting as an agent. This is done through the Coinbase Prime service under the Prime Execution Agent Agreement.

For Baskets creation, the Authorized Participants need to submit purchase orders, which are acknowledged by BRIL unless the Trustee or Sponsor refuses them. The timing for these submissions varies between the two models. For the Directed Trade Model, orders are placed on the trade date, while for the Agent Execution Model, there’s an earlier cutoff time, potentially the evening before the trade date. These orders determine the cash needed for the deposit and the corresponding Bitcoin amount the Trust needs to purchase.

The fee structure remains consistent, with a standard creation transaction fee for each order, which includes an ETF Servicing Fee and Custody Transaction Costs. BRIL, an affiliate of the Trustee, handles these services and fees.

The process of accepting purchase orders has also been streamlined. Upon acceptance by the Trustee, BRIL communicates the required Basket Amount to the Authorized Participant for the cash to be delivered in exchange for the Baskets. This system underlines a shift towards a more cash-centric approach in the Trust’s operation, diverging from the direct use of Bitcoin in transactions.

Bitcoin Redemption Changes.

The Trust has provided a structure similar to creations for redemptions, with the same Directed Trade Model and Agent Execution Model. This symmetry ensures consistency in the Trust’s operational framework for creations and redemptions.

The amendment has also introduced a new dynamic to determining the Basket Amount regarding redemptions. In addition to the daily adjustment, an indicative Basket Amount for the next business day will be made available to Authorized Participants, providing them with guidance for future transactions.

Moreover, the Trust has emphasized the potential for delays in Bitcoin transactions due to network issues, highlighting the inherent risks in dealing with digital assets.

Under the direction of the Sponsor, the Trustee has also been granted the authority to suspend the acceptance of purchase orders or the delivery or registration of transfers of Shares in certain circumstances, adding a level of control to manage unforeseen events or market disruptions.

These changes reflect a more sophisticated and nuanced approach to the operation of the iShares Bitcoin Trust, considering both Bitcoin’s volatility and the regulatory environment it operates within. The introduction of cash components, dual trade models, and potential for borrowing Trade Credits indicate a move towards a more flexible and responsive ETF structure, aiming to cater to varying investor needs and market conditions.

CF Index Risk Identification.

BlackRock has also highlighted a potential issue related to the Index Administrator, specifically system failures or errors. This amendment addresses the possibility that the computers or facilities used by the Index Administrator, data providers, or Bitcoin platforms could malfunction, leading to delays in calculating and disseminating the CF Benchmarks Index. This index is crucial as it is used to determine the Trust’s net asset value (NAV).

The amendment elaborates that errors in the CF Benchmarks Index data, computations, or construction could occur and might go unidentified or uncorrected for some time or even indefinitely. Such mistakes could adversely impact both the Trust and its Shareholders. In essence, if the CF Benchmarks Index encounters errors, it could lead to investment outcomes that differ from what would have occurred if these errors had not occurred.

Furthermore, it is specified that the Trust and its Shareholders will generally bear any losses or costs associated with these errors or related risks. The Sponsor, its affiliates, or its agents do not offer any guarantees against these risks.

The amendment also states that if the CF Benchmarks Index is unavailable or deemed unreliable by the Sponsor, the Trust’s holdings might be valued based on fair value policies approved by the Trustee. This revaluation could lead to discrepancies between the valuation and the actual market price of Bitcoin. Such a situation could result in the Shares’ price no longer accurately tracking the price of Bitcoin, either temporarily or over a more extended period. This misalignment could adversely affect investments in the Trust and the value of the Shares, potentially diminishing investor confidence in the Shares’ ability to track the price of Bitcoin.

IBIT Ticker Revealed.

Lastly, BlackRock has confirmed the ticker symbol for the Trust’s shares on NASDAQ as “IBIT,” facilitating easy identification for investors interested in tracking the ETF’s performance.
 

Link


community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
🇺🇸 CFTC Releases Video Unveiling Proposed Rules

🇺🇸 CFTC Chair Mike Selig releases video unveiling proposed rules to regulate US crypto markets.

"Clear rules of the road start now."

00:01:29
Dr. John Trump was awarded the National Medal of Science by President Ronald Reagan in 1983. 🇺🇸

🔻WATCH: A special tribute video honoring President Donald J. Trump’s uncle, Dr. John Trump, plays at the New Golden Age Summit.

00:01:36
🤖 China’s AI livestream economy is replacing human hosts with 24/7 virtual salespeople 🤖

Chinese e-commerce operators are using AI-generated avatars, synthetic voices, and automated scripts to sell products around the clock without requiring a human host to remain on camera.

🔑 Key points

🔹 AI avatars stream continuously: Virtual presenters can operate 24/7 across livestream platforms.

🔹 No human host is required on screen: The avatar delivers scripted product pitches using synthetic video, voice, facial movement, and gestures.

🔹 Multiple streams can run at once: Operators can manage several AI salespeople across different products, platforms, and time zones.

🔹 Product scripts are automated: AI hosts can repeat product descriptions, promotions, prices, and calls to action without fatigue.

🔹 Real-time interaction is developing: Some systems can respond to viewer comments, questions, and purchase behavior.

🔹 Revenue potential is significant: One AI streamer reportedly generated more than 10,000 yuan in a single hour, while other claims suggest some streams can generate up to $100 per...

00:00:19
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading

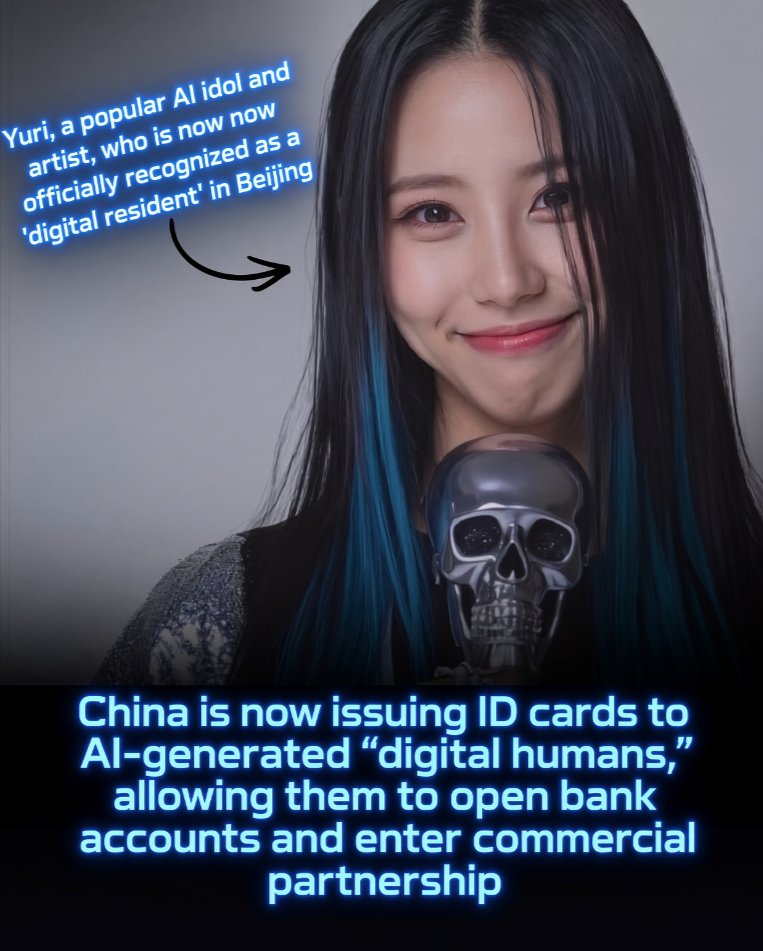
China is officially issuing government ID cards to AI-generated “digital humans,” so virtual influencers can open bank accounts and conduct business. These state-issued IDs, which include a name, birthday, address, and facial features, give virtual personas the legal ability to open digital-currency wallets, sign contracts, and form commercial partnerships.

Among the first to receive this recognition is Yuri, a popular AI-generated virtual idol and artist, who is now officially recognized as a “digital resident” in Beijing. The step comes as China’s digital-human market expands, with more than 1.3 million active firms and a sector value past $10 billion.

Supporters describe the IDs as a way to protect intellectual property and hold creator companies legally accountable for virtual actions. Critics warn that placing synthetic entities in official state systems could expand government surveillance in the digital space. Some companies are offering everyday citizens up to $20,000 to ...

post photo preview

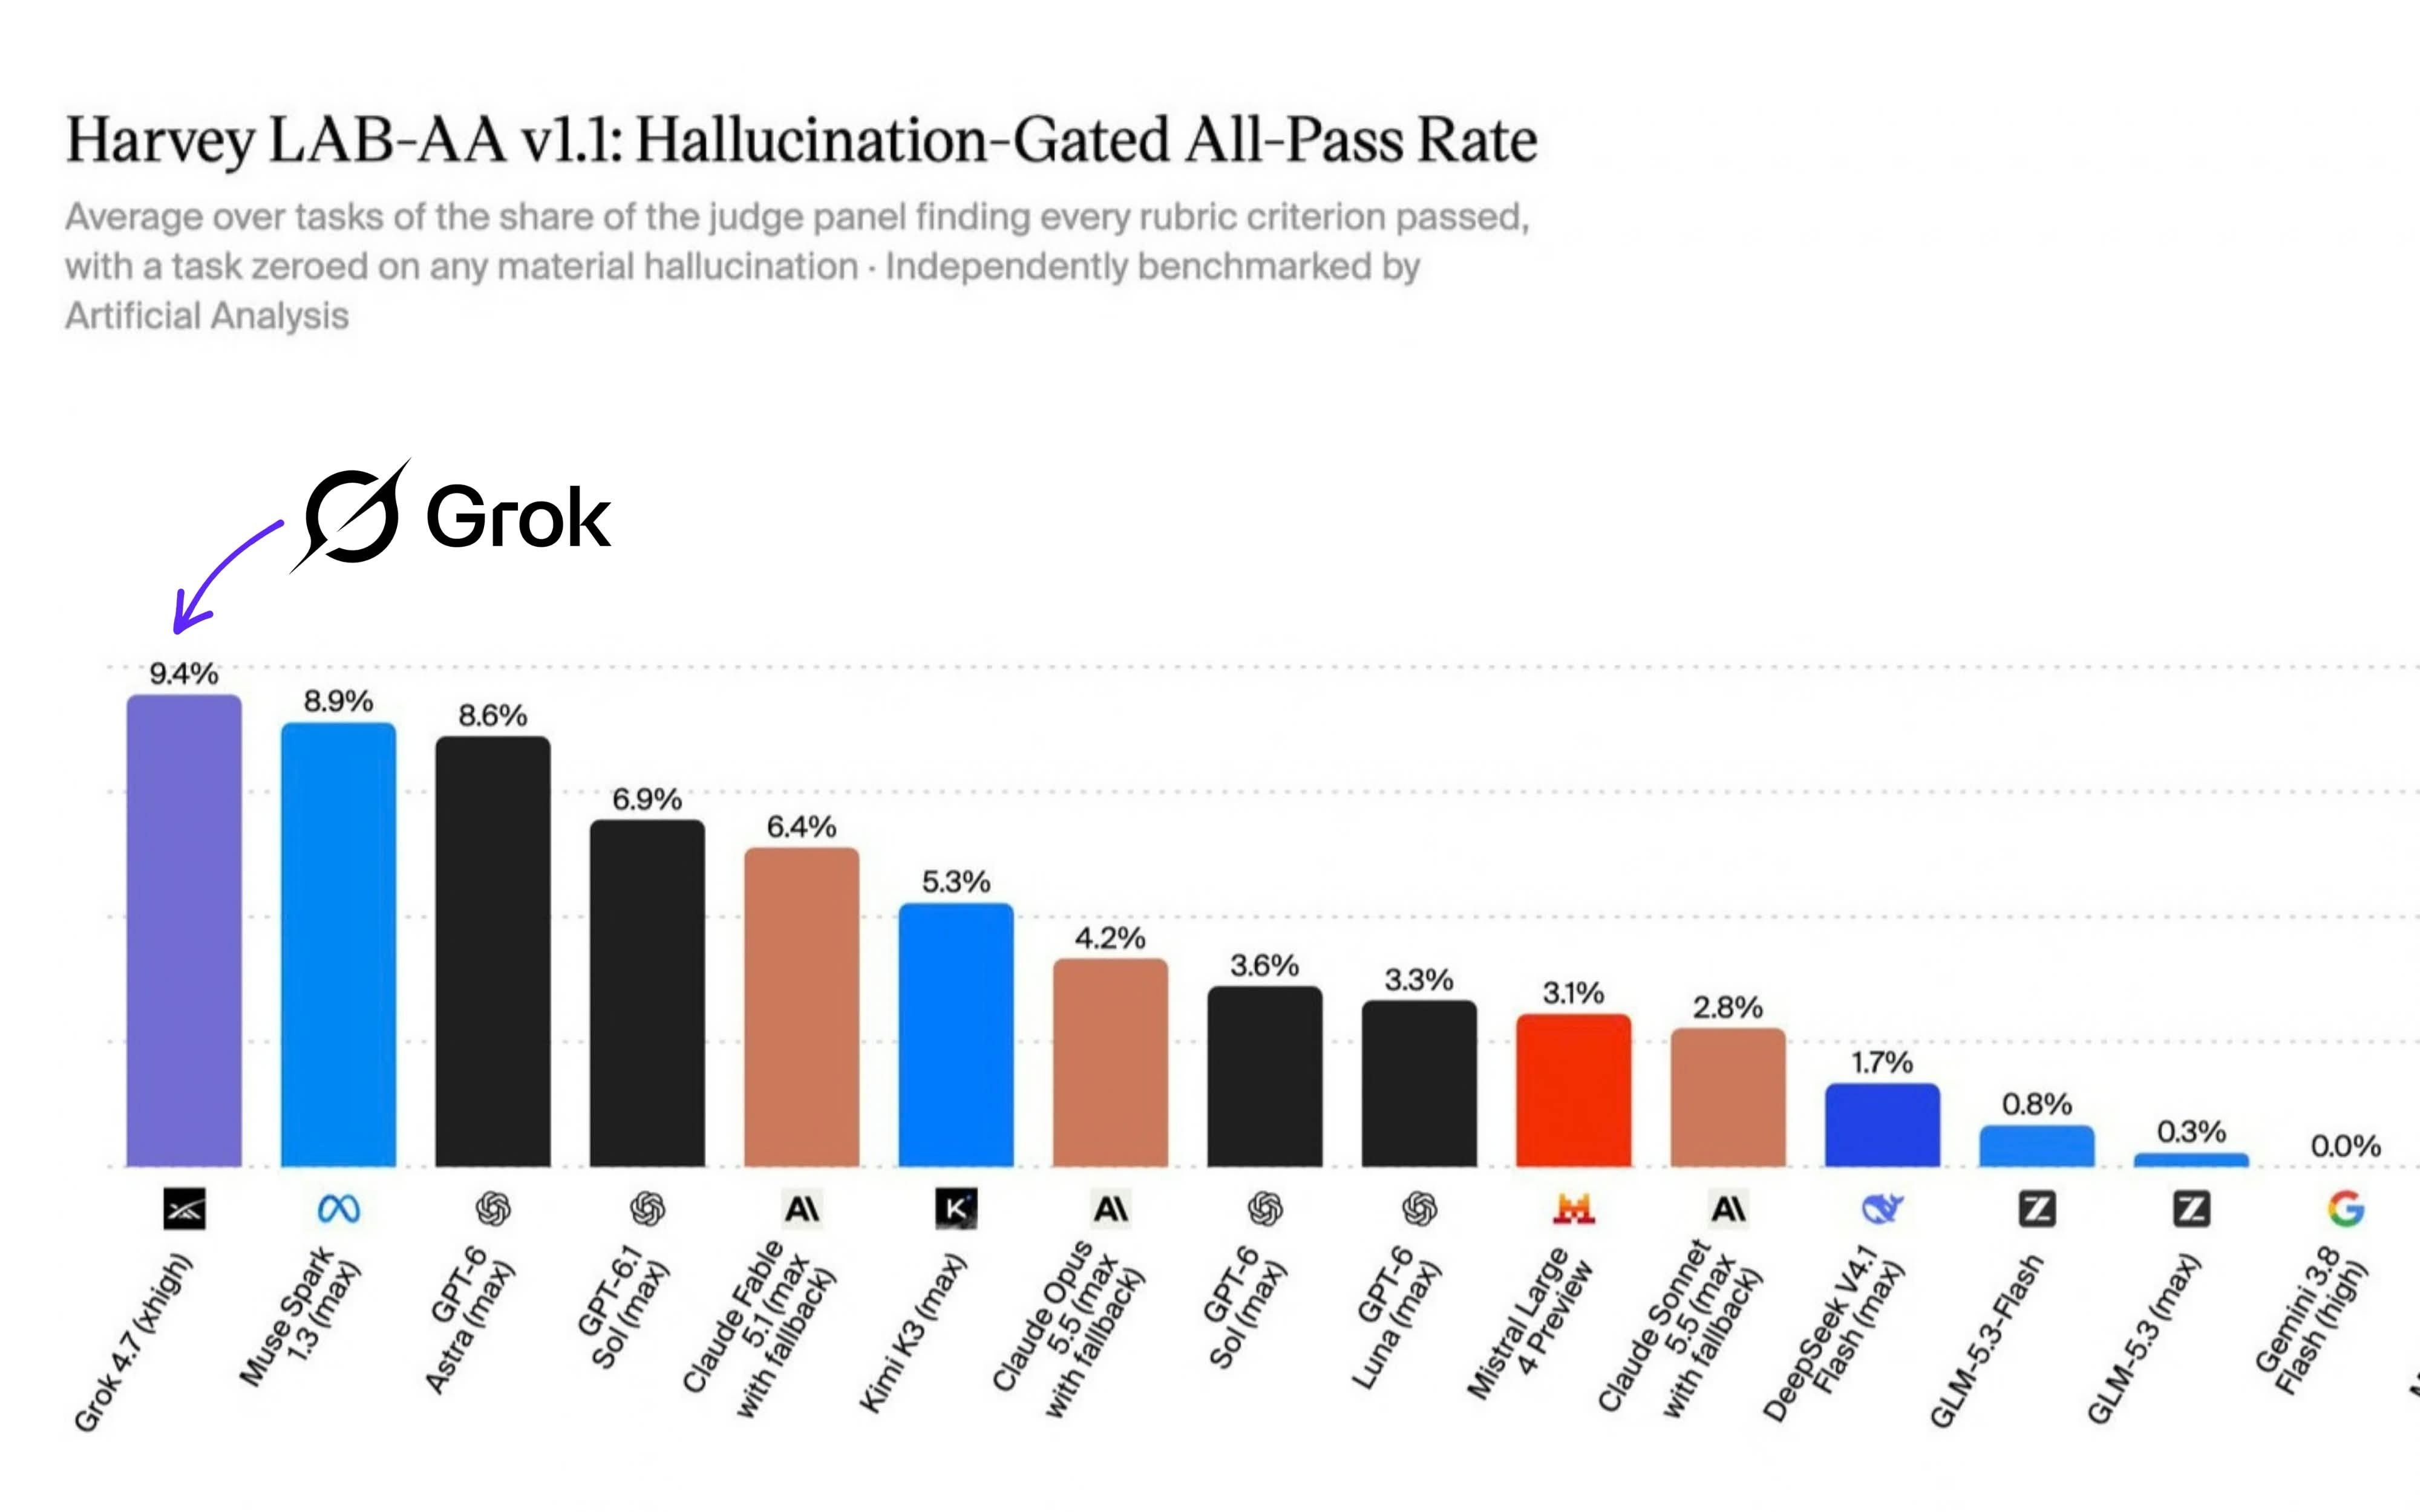
Grok 4.7 just ranked #1 on Harvey LAB-AA v1.1

Outperforming Claude Opus 5.5, GPT-6 Astra, Muse Spark 1.3, and others on the leaderboard.

The benchmark is brutal: a single material hallucination means the entire task gets zeroed.

This isn’t just about getting answers right... it’s about completing the entire task correctly without making material hallucinations.

Grok 4.7 is becoming an absolute monster at high-stakes reasoning.

post photo preview

Elon Musk just revealed that Grok Bots will manage Grokipedia.

“We’re just going to have @Grok Bots manage Grokipedia”

That means autonomous SI agents managing, reviewing and updating millions of articles as Grokipedia continues to evolve.

You can now watch Grokipedia evolve in real time.

Live edits are happening constantly across the platform as Grok reviews, updates and improves articles.

You can literally follow the knowledge base changing as it happens.

Pretty wild to watch an SI-maintained encyclopedia update itself live.

https://grokipedia.com/live

September 13, 2026
post photo preview
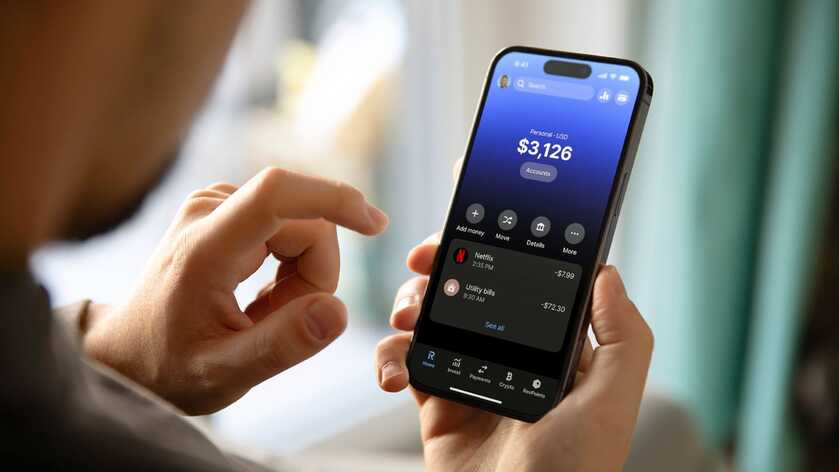
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
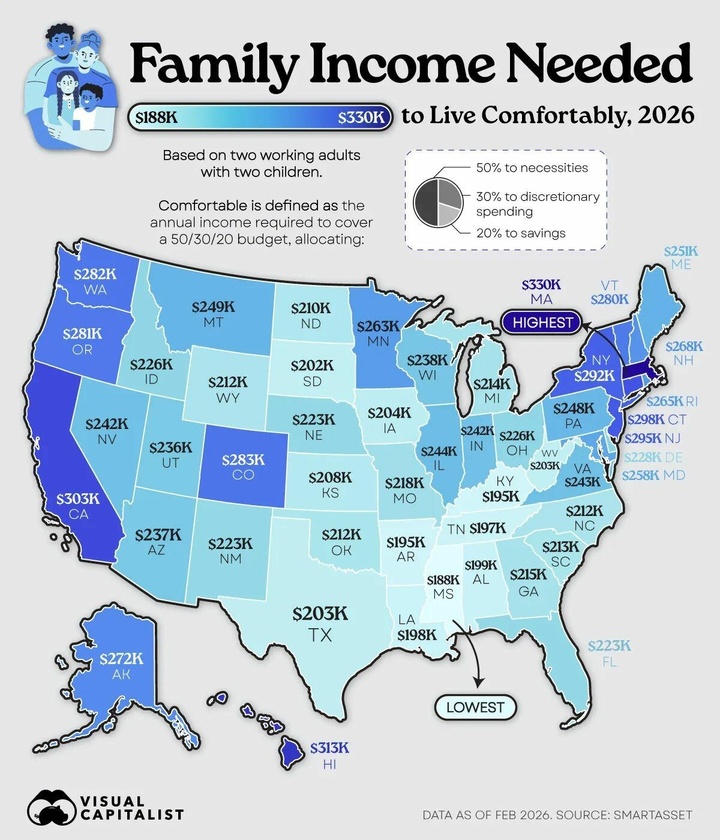
This Is The Income A Family Needs To Live Comfortably In Every US State

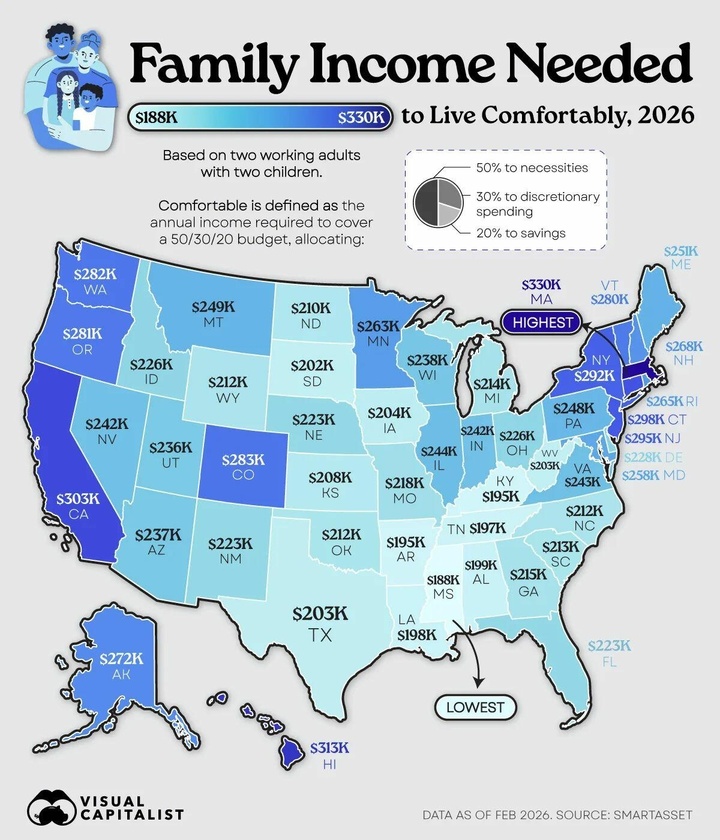
Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notes, Massachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here: 

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals