Dinarian888
News • Business • Investing & Finance
Institutional DeFi on the XRP Ledger: What's Live and What's Next
March 01, 2025
post photo preview

Institutional adoption of blockchain-powered finance has accelerated in the past year, with tokenized real-world assets (RWAs)stablecoins, and decentralized liquidity markets as major drivers of growth. Yet, for this transformation to scale, financial institutions need a robust, compliance-focused, and interoperable blockchain infrastructure—one that can support digital assets, seamless cross-border transactions, and institutional-grade decentralized finance (DeFi).

The XRP Ledger (XRPL) meets this challenge head-on, building on its core strengths—a native DEX, low fees, rapid settlement times, and a compliance-friendly architecture—to create an advanced institutional DeFi ecosystem. Several key capabilities are live, with others on their way, which will support the XRPL as a safe, secure, and scalable layer 1 for financial institutions looking to use blockchain in a regulated environment.

What’s Live on the XRP Ledger: Expanding Institutional DeFi Infrastructure

XRPL has made significant strides in enhancing liquidity, improving price transparency, and introducing new compliance tools to better cater to the needs of institutions.

While this blog highlights several of the newest features live on the XRP Ledger, they build upon core functionalities that have been supporting financial use cases for over a decade. The move towards a more automated and integrated system within XRPL’s native Decentralized Exchange (DEX) is designed to facilitate greater institutional participation by ensuring constant liquidity and minimal slippage. XRPL’s Central Limit Order Book (CLOB) has powered decentralized trading since its inception, providing efficient price discovery and deep liquidity across assets

Meanwhile, Payments—one of the ledger’s first native capabilities—continues to facilitate fast, low-cost global transactions, with additional payment primitives like Payment Channels for scalable micropayments, Checks for deferred settlement, and Escrows for conditional transfers. These are just some of the long-standing features that, combined with recent innovations, make XRPL one of the most mature and robust blockchains for institutional DeFi. With over 2.8B transactions having been processed to date, XRPL continues moving from strength to strength.

XRPL’s Automated Market Maker (AMM), built on the XLS-30 standard, introduces protocol-level liquidity for tokenized assets, stablecoins, and real-world assets (RWAs). Unlike traditional AMMs, XRPL’s version integrates directly with its native order book (CLOB)-based DEX, and enables price optimization to determine whether swapping within a liquidity pool, through the order book, or both provides the best rate and executes accordingly. Its continuous auction mechanism mitigates impermanent loss, making liquidity provision more appealing to institutional players. 

Thanks to AMM Clawback, all key tokens, including Ripple USD (RLUSD), can fully leverage the network’s AMM liquidity pools. By enabling issuers to “claw back” funds from a trustline in specific circumstances—like lost account access or malicious activity—this amendment satisfies crucial regulatory requirements for fraud prevention and transaction reversals. Clawback remains an optional feature, intentionally disabled by default that can only be enabled for issued assets and never for XRP.

Key Use Cases

  • Institutional Liquidity Provisioning – Funds and market makers can deploy capital in AMM pools to generate yield.

  • Tokenized RWA Trading – Previously illiquid assets, such as tokenized treasuries and real estate, can be efficiently traded.

  • Arbitrage & Cross-Chain Swaps – Ensuring pricing accuracy across different DeFi ecosystems.

Decentralized Identity (DID) 

Now that XLS-40 is live, institutions and developers can create and manage decentralized identifiers (DIDs) directly on the Ledger. This feature enables self-sovereign identity, allowing users to establish verifiable identities without relying on centralized intermediaries. 

By leveraging DIDs, institutions can enhance security, privacy, and compliance while maintaining decentralization. This lays the groundwork for permissioned access to financial markets, identity verification for tokenized real-world assets (RWAs), and broader institutional adoption of DeFi.

Key Use Cases

  • Privacy-Preserving KYC & AML Compliance – Institutions can verify identity attributes without exposing sensitive personal data.

  • Permissioned Finance & Access Control – Gate entry to regulated trading venues using onchain credentials.

  • Institutional Onboarding – Streamline identity verification for tokenized securities, RWAs, and lending platforms.

Price Oracles: Bringing Market Data Onchain

Real-time and accurate price feeds are critical for institutional DeFi—especially when dealing with tokenized assets and cross-chain transactions. To meet this need, the XRP Ledger integrates protocol-native oracles, providing a built-in mechanism for bringing off-chain data (like stablecoin rates and real-world asset valuations) onchain. Because these oracles are embedded directly into the XRPL—much like its native AMM—they avoid reliance on separate third-party layers, ensuring more efficient and trustworthy data flows. 

Providers such as Band Protocol and DIA are already live on the XRPL mainnet, delivering robust price feeds that span both crypto and traditional markets. This is essential for institutions, given that much of the data required still resides in legacy Web2 systems.

Key Use Cases

  • Accurate RWA Valuation – Ensuring tokenized assets remain pegged to their real-world counterparts.

  • Cross-Chain Interoperability – Providing price feeds for assets moving across different blockchain networks.

  • Institutional-Grade Risk Management – Enabling more reliable onchain lending and derivatives.

What’s Coming to the XRP Ledger: Expanded Compliance Features, Institutional Lending, and Programmability

XRPL is evolving with new features that bring greater compliance functions, expanded lending, and more ways to build onchain financial products. These changes will enable institutions to meet regulatory requirements, offer new lending options, and give developers more flexibility to build and deploy financial applications.
Building on DID: Permissioned DEX, Credentials & Compliance Innovations

Enhancing the ‘Identity Stack’ in finance tools will enable institutions to build secure, compliant trading venues on XRPL.

Credentials are designed to be a lightweight feature and are additive to the recent Decentralized Identity (DID) standard. The Credentials standard introduces a new ‘Credential’ ledger object along with new transaction types for creating, accepting, and deleting credentials. The XLS-70 spec for Credentials on the XRPL is currently undergoing the amendment voting process as part of the rippled 2.3.0 release.

Ripple Senior Software Engineer, Mayukha Vadari, recently outlined how to consider Credentials as a modular building block to DID. It can be applied to attest to specific criteria (e.g. KYC) pertaining to a user and issued to their DID. This is critical in terms of enabling a smooth onboarding process when accessing products like tokenized RWAs.

Credentials and DID give rise to two additional features, Permissioned Domains and a Permissioned DEX, that help facilitate a flexible, institutional-grade identity system on XRPL.

Permissioned Domains allow entities, such as financial institutions, to establish environments on the XRPL that require specific credentials for access. This setup enables organizations to define membership criteria, such as Know Your Customer (KYC) credentials from trusted issuers, and manage participation within their domain. Importantly, this system preserves user privacy by verifying credential validity without exposing personal information

Building upon this, the Permissioned DEX extends the XRPL’s native DEX to operate within these controlled domains, ensuring that only accounts with valid credentials can create or fill orders. This approach allows institutions to engage in decentralized trading while adhering to regulatory requirements, such as Anti-Money Laundering (AML) and KYC rules, all within a decentralized framework.

While DIDs serve as a foundational “fingerprint” for each user, Credentials provide the identity and compliance layer required for different scenarios. Building on these foundations, Permissioned Domains and Permissioned DEX protocols enforce membership and compliance rules by requiring the appropriate DID-based Credentials, all while preserving the open nature of the XRPL.

Multi-Purpose Token (MPT): A New Standard for Tokenized Assets

Traditional financial instruments such as stocks, bonds, and other securities possess intricate data requirements that can be challenging to represent onchain as fungible tokens. For instance, two bonds may be identical in all regards except their expiry dates, which is a critical detail and makes it inappropriate to present both as equivalent. 

To solve this, the XRPL developer community has introduced Multi-Purpose Tokens (MPTs) which bridge the gap between fungible and non-fungible tokens. They are akin to “semi-fungible” tokens whereby key associated metadata can be attached. This provides them with more flexibility than fungible tokens, while they’re not truly unique such as with NFTs.

Currently undergoing validator voting, MPT introduces a more flexible, efficient, and metadata-rich token standard that allows institutions to tokenize and trade bonds, RWAs, and structured financial products with enhanced functionality.

Key Use Cases

  • Tokenized Bonds – Represent fixed-income assets on XRPL with precise metadata storage.

  • Grade Asset Management – Better compliance features, efficiency, and control over tokenized securities.

XRPL Lending Protocol: Credit-Based DeFi for Institutions 

The XRP Ledger-native lending protocol adds a pivotal dimension to the XRPL’s DeFi capabilities. This proposed amendment will enable crypto-native businesses to integrate lending with Ripple Payments, DEX, RWAs, and stablecoins, using a default RLUSD vault to reduce liquidity fragmentation and AMM for seamless FX swaps. It will also look to streamline asset allocation and fund admin for crypto-native managers with automated returns, real-time valuations, diversified strategies, and compliant execution via RWAs and onchain KYC.

Institutional DeFi requires robust, scalable, and secure financial products. The XRPL-native lending protocol addresses these needs by providing a decentralized, protocol-native solution for lending that reduces reliance on intermediaries, enhances transparency, and offers a higher degree of security.

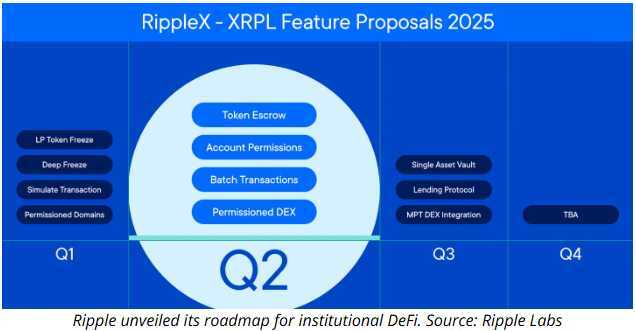
The lending protocol specs, XLS-65d, will allow for the pooling of assets (public or private) represented by Vault shares, with optional Permissioned Domain access, while XLS-66d will introduce on-ledger, fixed-term, uncollateralized lending with off-chain underwriting and first-loss capital protection, allowing financial institutions to issue credit and manage risk directly on the blockchain. You can expect these developments to undergo voting in Q2 of 2025.

Key Use Cases:

  • Institutional Lending Markets – Banks, fintechs, and funds can tokenize and distribute loans onchain.

  • Stablecoin & RWA Integration – Lending backed by tokenized assets and compliance-focused stablecoins.

Expanding Programmability 

As announced in September, Ripple, in collaboration with the community, is committed to bringing permissionless programmability to the XRPL. Programmability on the XRPL offers an opportunity to seamlessly connect its powerful, native building blocks with the flexibility of custom on-chain business logic. This vision focuses on preserving what makes the XRPL special—its efficiency, reliability, and simplicitywhile empowering builders to unlock new possibilities. This goal requires a measured approach, with careful steps that ensure the robustness of the network. 

Native Programmability

The first step of this broader effort will see the introduction of 'Extensions,’ a feature that allows developers to attach small pieces of code to existing XRPL primitives, enhancing their functionality without the need for entirely new smart contracts

This approach can enable the customization of features like escrows, automated market makers (AMMs), and tokens, making them more adaptable to specific use cases while maintaining efficiency and security. For instance, “Smart Escrows” allow developers to incorporate custom release conditions, such as notary approvals or price-based triggers, without needing to rebuild the escrow mechanism from scratch. This method preserves the robustness of XRPL’s native features while offering tailored solutions for complex requirements.

The timeline toward deployment is outlined below:

  • Q1: Early devnet for smart escrows

  • Q2: Full-functional Smart Escrow devnet

  • Q3: Release Smart Escrows in an amendment for voting

  • Q4: Smart Contract devnet

For a detailed overview on ‘Extensions’ and broader programmability efforts you can dive into RippleX Devto blog.

XRPL EVM Sidechain

The XRPL EVM sidechain serves a complementary role to the XRPL, but is not a replacement for mainnet programmability. 

Set for Mainnet launch in Q2 2025, the XRPL EVM Sidechain offers a great opportunity to attract EVM ecosystem developers to the XRPL ecosystem. It can also be used to launch protocols that are not currently possible on the XRPL - especially ones that are already written in Solidity, or specifically require the EVM. This bridged solution, using a cross-chain approach, is useful if a project requires an alternative form of programmability.

Key Benefits:

  • First-Mover Advantage: Be among the first to deploy cross-chain or EVM dApps on an emerging sidechain ecosystem tied to XRPL.

  • Access a Vast Ecosystem: Tap into the 5.7M+ XRP wallet holders and gain exposure to a thriving, established blockchain community.

  • Seamless Development: Use familiar EVM tools to build, port, or fork dApps quickly, with minimal barriers to entry.

Looking Further Ahead

As tokenization and decentralized finance continue to evolve, XRPL is positioning itself as a leader in regulated onchain finance. With deep liquidity, compliance-friendly features, and seamless institutional integration, the next phase of Institutional DeFi will be built on XRPL. 

While a dedicated roadmap page is in development, the broader XRPL ecosystem is actively shaping the future of institutional DeFi through innovations such as Automated Market Makers (AMMs), Price Oracles, Decentralized Identifiers (DIDs), and new tokenization standards. These developments reflect ongoing collaboration across the network to enhance security, efficiency, and institutional-grade financial tools. 

For deeper insights into XRPL’s future, join us at XRPL Apex 2025, where David Schwartz will outline the roadmap and explore the latest advancements driving Institutional DeFi forward.
Reasons for optimism

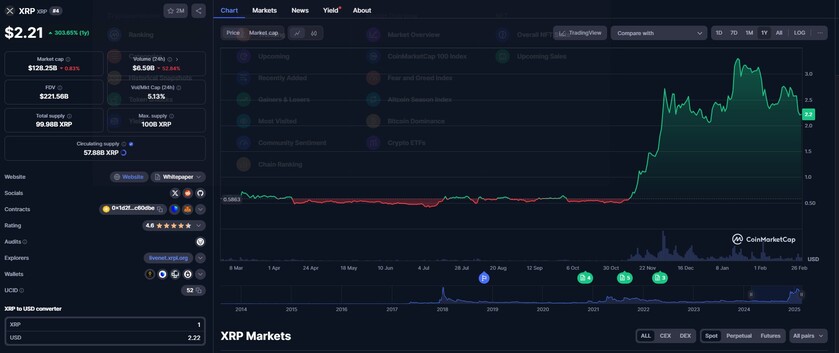
Ripple hopes that leaning into institutional DeFi, including real-world assets (RWAs), will supercharge the network’s growth, according to the blog post.

Tokenized RWAs represent a $30-trillion market opportunity globally, Colin Butler, Polygon’s global head of institutional capital, told Cointelegraph in an interview.

Trump, who has promised to turn the US into the “world’s crypto capital,” plans to tap industry-friendly leaders to head key financial regulators, including the US Securities and Exchange Commission.

Several asset managers have applied to list XRP exchange-traded funds (ETFs) in the US, which JPMorgan expects could attract billions in investor inflows.

Some experts have suggested that the SEC case against Ripple, ongoing since 2022, could be paused or withdrawn entirely.

On Feb. 25, the US regulator dropped its probe into Uniswap, a DEX, as part of a broader pivot on crypto policy under Trump. 
 

Source


community logo
Join the Dinarian888 Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Videos
Podcasts
Posts
Articles
🤯Our Military Is FAR More Advanced Than Your Imagination Can Conceive🤯

Chief of Space Operations Gen. Douglas Schiess at #AFA2026

🤯"Let me be crystal clear. Today, Guardians operate on-orbit weapons that can defend the joint force against space-enabled attacks."🤯

OP: https://x.com/USSpaceForce/status/2100940411174838394?s=20

00:00:31
September 17, 2026
🚀 Score Studio is officially LIVE today on the Bittensor network (SN44)!

For too long, computer vision workflows have been fragmented across scattered labeling tools, messy notebooks, disparate model hubs, and complex deployment stacks. 🧩⚡

We brought the entire lifecycle into one unified workspace:

  • 🎨 Annotate
  • 🧠 Train
  • 📊 Evaluate
  • 🚀 Deploy

No more switching between a dozen apps to get a vision model into production.

🔗 Try it free: scorestudio.ai

00:00:25
September 16, 2026
USDC to dTAO Crosschain swaps

Now LIVE.

Swaps settle in seconds, it's FAST.

Like, seriously quick.

Directly from Subnets into USDC (Or ETH) and vice versa.

Try it today at TAOcom

00:00:28
🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨

Chutes is gaining attention as a decentralized AI inference platform that claims to combine real usage, cryptographic verification, confidential computing, and open-source infrastructure into a working production system. The thesis is simple: instead of trusting Big Tech clouds with AI workloads, users get a distributed compute layer built around verification and privacy.

🔑 Key points

🔹 Chutes is live in production and reportedly scaled to more than 1,170 active GPU nodes, including large numbers of Nvidia H200s and Blackwell-class hardware.

🔹 The platform says it has processed nearly 38 trillion tokens since launch across 53 deployed applications and more than 700,000 registered users.

🔹 The team reportedly cut unprofitable usage programs, reduced total token volume, and still improved revenue efficiency, with revenue per GPU rising sharply after removing subsidized traffic.

🔹 Chutes is using post-quantum cryptography, trusted execution environments, and Nvidia confidential ...

🚨 Chutes is being framed as a Hyperliquid-style breakout for decentralized AI inference, with live revenue, verified GPU infrastructure, and a direct challenge to centralized cloud AI 🚨
🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨

A new clash is emerging between legacy finance and crypto legislation after JPMorgan CEO Jamie Dimon reportedly warned that the CLARITY Act could let crypto firms offer bank-like products without bank-level oversight. The dispute is quickly turning into a larger fight over regulation, competitiveness, and who controls the future architecture of digital finance in the United States.

🔑 Key points

🔹 Jamie Dimon reportedly called the CLARITY Act a threat to the financial system, arguing it could allow crypto firms to offer yield-like products while avoiding the capital, reserve, and oversight burdens traditional banks face.

🔹 Senator Cynthia Lummis pushed back publicly, framing the issue as a global strategic race and warning that if the U.S. does not set digital asset standards, other powers will.

🔹 The core tension is whether the bill creates legitimate regulatory clarity or simply opens the door to regulatory arbitrage for crypto platforms operating outside the traditional banking...

🚨 JPMorgan’s criticism of the CLARITY Act is fueling a fresh power struggle over who gets to write America’s crypto rules 🚨
👉 Coinbase just launched an AI agent for Crypto Trading

Custom AI assistants that print money in your sleep? 🔜

The future of Crypto x AI is about to go crazy.

👉 Here’s what you need to know:

💠 'Based Agent' enables creation of custom AI agents
💠 Users set up personalized agents in < 3 minutes
💠 Equipped w/ crypto wallet and on-chain functions
💠 Capable of completing trades, swaps, and staking
💠 Integrates with Coinbase’s SDK, OpenAI, & Replit

👉 What this means for the future of Crypto:

1. Open Access: Democratized access to advanced trading
2. Automated Txns: Complex trades + streamlined on-chain activity
3. AI Dominance: Est ~80% of crypto 👉txns done by AI agents by 2025

🚨 I personally wouldn't bet against Brian Armstrong and Jesse Pollak.

👉 Coinbase just launched an AI agent for Crypto Trading

🤖 Citrini Research says robotics may be approaching a major tipping point 🤖

A new Citrini Research report argues that falling hardware costs, improving AI models, and expanding industrial demand could push robotics from experimental deployments into a mainstream economic force.

🔑 Key points

🔹 AI is improving robot capability: Better perception, planning, imitation learning, and control systems are helping robots operate in less-structured environments.

🔹 Hardware costs are falling: Advances in sensors, actuators, batteries, chips, and manufacturing could make capable robots cheaper to produce.

🔹 Industrial adoption comes first: Warehouses, factories, logistics centers, agriculture, and construction offer structured environments where robots can deliver measurable returns.

🔹 Humanoid designs are gaining attention: Human-like robots can potentially use existing tools, workstations, and facilities without requiring every environment to be rebuilt.

🔹 Labor shortages create demand:...

⚖️ ECB President Christine Lagarde reportedly intervened in Binance’s EU MiCA licensing effort ⚖️

A Wall Street Journal report cited by CoinDesk claims that European Central Bank President Christine Lagarde intervened to oppose Binance receiving a MiCA license in the European Union.

🔑 Key points

🔹 Binance’s EU licensing effort faced resistance: The exchange reportedly sought authorization to operate under the bloc’s Markets in Crypto-Assets framework.

🔹 Lagarde was allegedly involved: The report claims she raised concerns about Binance’s regulatory history and potential access to the EU market.

🔹 The ECB does not issue MiCA licenses: Authorization is generally handled by national competent authorities, although the ECB can influence banking and financial-stability discussions.

🔹 MiCA creates passporting rights: A licensed crypto-asset service provider can potentially operate across EU member states after receiving approval in one jurisdiction.

🔹 Binance’s ...

📜Defense Intelligence Reference Documents📜

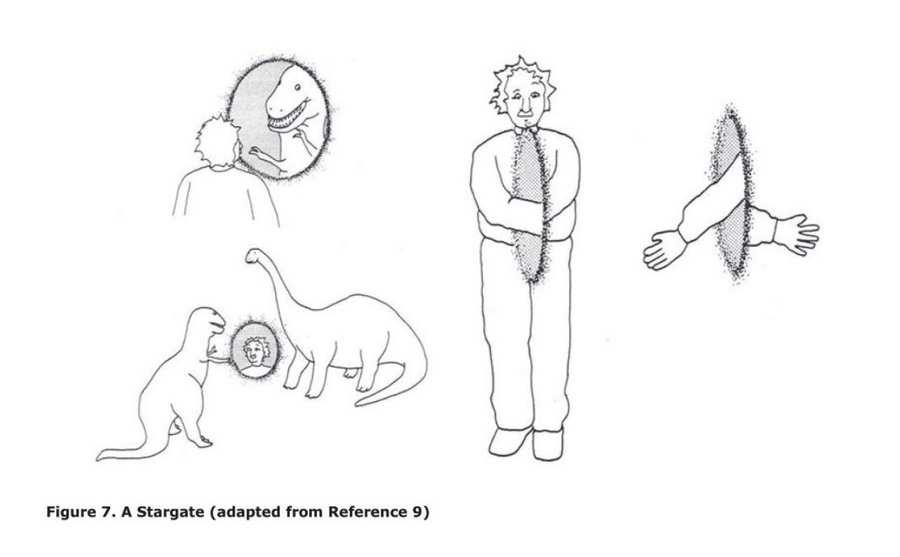
This has been around for ages and it comes from one of the Defence Intelligence Reference Documents (DIRDs) I believe this DIRD was authored by Dr. Eric W. Davis and it will be in relation to Traversable Wormholes. 🤯For those that don't know, this is not new information, this is one image from a larger document which represents one document out of 37 DIRD's which were publicly released years ago.

This is the key section of the DIA/AAWSAP papers where Dr. Eric Davis lays out the fundamental physics of why traversable wormholes and "stargates" aren't just sci-fi tropes, but mathematically valid solutions under General Relativity! 🌌⚡️

Why Page 8 (and the surrounding energy conditions analysis) is huge:

🌀 The Throat Mechanics: Classical general relativity requires "exotic matter"—specifically negative energy density—to keep a wormhole throat open and prevent immediate gravitational collapse.

🚪 Flat Entry/Exit Openings: Davis details how a modified metric allows for ...

post photo preview
September 13, 2026
post photo preview
Revolut Leak Shows the Cost of Constant ID Collection
Revolut’s mistake is the news, but the bigger problem is the growing number of companies being encouraged or required to keep copies of our most sensitive identity documents.

Online bank Revolut has revealed that it gave out sensitive personal and financial information of an undisclosed number of its customers in response to a fake government request.

The information that was handed over to an “unauthorized third party” reportedly includes names, dates of birth, occupations, addresses, phone numbers, account numbers, transaction histories (including Bitcoin), and even copies of government-issued IDs and onboarding verification selfies.

Revolut claims that derived biometric face data was not.

The company said that the data was handed over in response to an email that came from a real government agency’s domain, but was not actually sent or authorized by that agency.

The email passed several authentication checks (SPF, DKIM, and DMARC) that are designed to establish the authenticity of a message’s origin and integrity, but do not verify the legitimacy of the legal request itself.

Revolut said that it complied with the request “under the reasonable belief that it was an authentic government agency request” – and only later found out that it was not.

Revolut said it later realized its mistake, blocked the email address, and reported the incident to the relevant authorities.

Revolut said that only a “limited” number of its customers were affected by the data leak, and that the company’s systems were not hacked, nor was any money stolen.

The story broke on September 11 when Revolut customers started receiving an email notice about a data leak, and the news was picked up by media outlets the following day.

Revolut notice explaining customer identity and financial data was shared after an unauthorized government email request.

The reason this is a recurring problem is that companies are keeping highly sensitive information about their customers’ identities, and sometimes even financial transactions, for a long time, and this data is then available to be disclosed to third parties – either in response to valid legal requests, or, as in the case of Revolut, fake ones.

One reason for this is know your customer (KYC) and anti-money laundering (AML) rules. Revolut’s current UK customer privacy notice spells it out: the company generally keeps personal data of UK customers for no more than seven years after the relationship ends, and sometimes longer – for legal reasons.

This means that even if you close your account, your identity documents don’t disappear.

And while the incident with Revolut happened in the financial sector, it’s by no means the only one that requires customers to hand over sensitive identity information. Discord, a popular chat service, said in an October 9, 2025 security update that government ID photos of approximately 70,000 users may have been exposed after a third-party customer service provider got hacked.

This was not a financial service, nor the same type of attack. But the result was similar – because the underlying business process was the same: requiring and storing sensitive identity documents. In the case of Discord, these were used to review age-related appeals.

It’s hard to do anything about a copy of your old passport, or a photo of your face, or a record of your past transactions. These can be used to identify and profile you, and can be used to carry out targeted fraud. And this can happen even if the initial disclosure didn’t result in financial loss.

The more companies are forced to collect and store such information, and the more of it they have, the more opportunities there are for this data to be leaked, either by the company itself or a third party it works with. That's what makes governments' push for more ID checks just to access ordinary parts of life so reckless.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
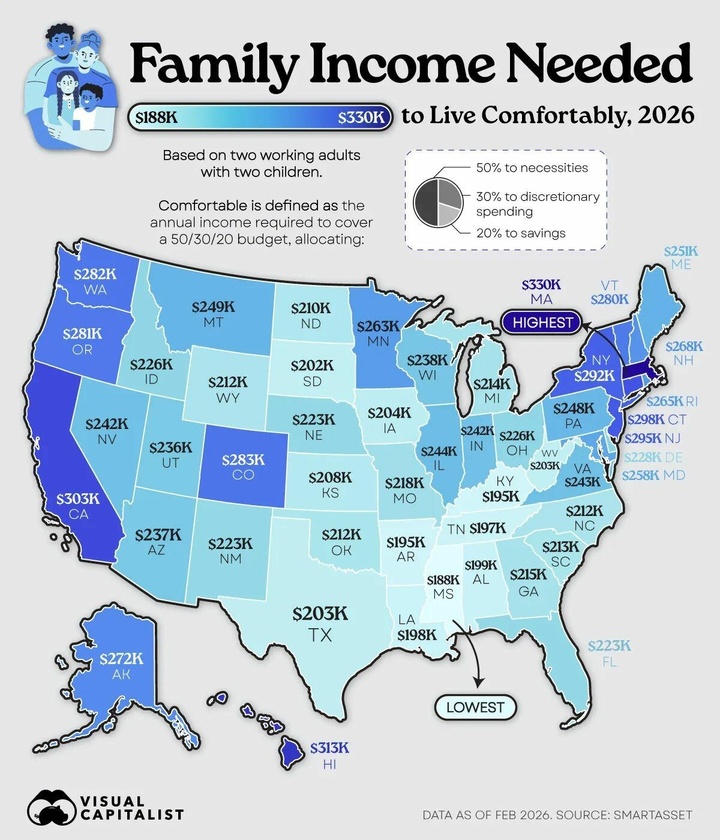
This Is The Income A Family Needs To Live Comfortably In Every US State

Here’s the short version of what it takes for a family of four to live comfortably in 2026 by state:

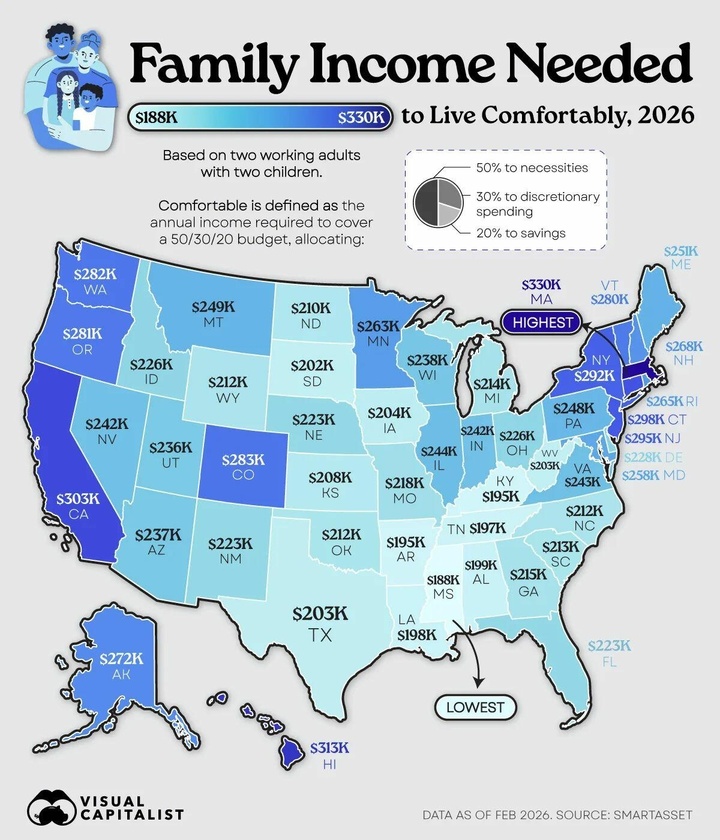
In Massachusetts, you’d need nearly $330,000 a year - the highest figure in the entire country. Only three states clear the $300,000 mark: Massachusetts, Hawaii, and California. At the other end of the spectrum, Mississippi is the most affordable at about $188,000. That’s a full $142,000 less than what you’d need in Massachusetts.

So… how much does a family of four need in your state?

This map shows the pre-tax income a household with two working adults and two kids needs to live comfortably in every U.S. state.

The numbers come from SmartAsset (as of February 2026). They’re based on the familiar 50/30/20 budget: 50% for necessities, 30% for discretionary spending, and 20% for savings or other goals. These aren’t bare-minimum survival numbers—they’re what it takes to live pretty well while still putting money aside.

And as Visual Capitalist notesMassachusetts sits at the very top of that list. Massachusetts tops the ranking, with a family of four needing $329,555 per year to meet the 50/30/20 benchmark.

Hawaii follows at $313,165, while California ranks third at $302,682.

Rank State Income needed for family of four (2026)

  • 1 - Massachusetts - $329,555
  • 2 - Hawaii - $313,165
  • 3 - California - $302,682
  • 4 - Connecticut - $298,189
  • 5 - New Jersey - $295,110
  • 6 - New York - $291,533
  • 7 - Colorado - $283,213
  • 8 - Washington - $281,798
  • 9 - Oregon - $280,966
  • 10 - Vermont - $280,384
  • 11 - Alaska - $272,064
  • 12 - New Hampshire - $267,904
  • 13 - Rhode Island - $264,659
  • 14 - Minnesota - $263,078
  • 15 - Maryland - $257,837
  • 16 - Maine - $250,931
  • 17 - Montana - $249,434
  • 18 - Pennsylvania - $247,936
  • 19 - Illinois - $244,109
  • 20 - Virginia - $242,944
  • 21 - Nevada - $242,278
  • 22 - Indiana - $241,696
  • 23 - Wisconsin - $238,451
  • 24 - Arizona - $236,870
  • 25 - Utah - $235,789
  • 26 - Delaware - $228,134
  • 27 - Ohio - $226,221
  • 28 - Idaho - $226,054
  • 29 - Florida - $223,392
  • 30 - New Mexico - $223,142
  • 31 - Nebraska - $223,059
  • 32 - Missouri - $217,734
  • 33 - Georgia - $214,573
  • 34 - Michigan - $214,323
  • 35 - South Carolina - $212,909
  • 36 - North Carolina - $212,410
  • 37 - Wyoming - $212,410
  • 38 - Oklahoma - $211,910
  • 39 - North Dakota - $210,496
  • 40 - Kansas - $207,917
  • 41 - Iowa - $204,422
  • 42 - Texas - $203,424
  • 43 - West Virginia - $202,592
  • 44 - South Dakota - $201,760
  • 45 - Alabama - $198,931
  • 46 - Louisiana - $197,933
  • 47 - Tennessee - $197,267
  • 48 - Arkansas - $195,437
  • 49 - Kentucky - $194,854
  • 50 - Mississippi - $187,533

Connecticut, New Jersey, and New York aren't far behind, bringing the number of states with comfortable-income thresholds above $290,000 to six.

Colorado and Vermont Make the Top 10

As expected, many of the highest income thresholds are concentrated in the Northeast and along the West Coast.

However, Colorado has the seventh-highest threshold in the country at $283,213, ranking above Washington and Oregon.

Vermont rounds out the top 10 at $280,384, despite having the second-smallest population of any U.S. state. Meanwhile, nearby states like New Hampshire, Maine, and Rhode Island all fall outside the top 10.

Just Six States Come in Below $200,000

Despite the wide range in living costs across the country, only six states have a comfortable-income threshold below $200,000 for a family of four.

Mississippi ranks lowest at $187,533, followed by Kentucky. The states of Arkansas, Tennessee, Louisiana, and Alabama also fall below the $200,000 mark.

The gap between Massachusetts and Mississippi exceeds $142,000 per year, meaning the Massachusetts benchmark is about 76% higher.

Source

🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations Always Welcome 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
post photo preview
🤖Can Decentralized AI Stop Big Tech from Owning the Future of Robotics?🤖
The race to build the future of robotics is no longer just about robots. It's about who controls the intelligence behind them.
 
Over the last three years, a small group of companies has emerged as the backbone of the AI revolution. Microsoft provides cloud infrastructure. NVIDIA supplies the chips. Google, OpenAI, Anthropic, Meta, and others develop the models. Together, they control much of the compute, data, and software stack powering modern AI.
 
Now that AI is moving into the physical world, many are asking a bigger question:
 
Will these same companies end up controlling robotics too?
 
It's a valid concern.
 
The latest generation of robots relies on enormous amounts of compute, simulation, training data, and foundation models. Many robotics startups today are built on infrastructure provided by large technology companies. NVIDIA's Omniverse is becoming a key simulation environment for robot training. Microsoft Azure is powering the training of robotics foundation models. Physical AI startups increasingly depend on hyperscale cloud infrastructure to train and deploy intelligent systems. Recent partnerships across the industry show just how central Big Tech has become to robotics development.
But while Big Tech is building the highways, another movement is trying to ensure it doesn't own every destination.
 
That movement is decentralized AI.
 
Why Decentralized AI Exists
 
The idea behind decentralized AI is simple. Instead of a handful of companies owning the models, compute infrastructure, data pipelines, and intelligence networks, these resources are distributed across thousands of participants.
 
This means anyone can contribute compute, contribute models, validate outputs and can participate.
The most visible example today is the decentralized AI network known as Bittensor (@bittensor). The network has evolved into a large ecosystem of specialized AI markets called subnets, where participants compete to provide useful machine intelligence and are rewarded based on performance. Rather than relying on a single company, intelligence is generated and validated by a distributed network of miners and validators.
 
Think of it as an attempt to build an open marketplace for AI instead of a world where intelligence is rented from a few centralized providers.
 
Why This Matters for Robotics
 
Robotics has a unique problem. Unlike chatbots, robots operate in the physical world. They need to perceive environments, make decisions, move safely and they need to learn continuously.
 
The challenge is that collecting and training on real-world robotic data is incredibly expensive. That's one reason large companies have such an advantage. They can afford the compute, simulation environments, and data infrastructure needed to train robotics models at scale.
 
This is where decentralized systems become interesting.
 
Instead of one company collecting all the data and training all the models, decentralized networks could allow thousands of contributors to participate in building robotic intelligence.
 
Imagine a future where:
  • Warehouse robots contribute operational data.
  • Delivery robots contribute navigation data.
  • Factory robots contribute manipulation data.
  • Developers contribute models.
  • Validators evaluate performance.
The resulting intelligence becomes a shared network rather than a proprietary asset.
 
That vision is beginning to emerge.
 
Bittensor's Move Toward Physical AI
 
While many people associate Bittensor (@bittensor) with language models and AI services, parts of the ecosystem are increasingly exploring embodied intelligence and robotics.
 
One example is Kinitro, a subnet focused on incentivizing the training and evaluation of embodied AI systems. The goal is to create competitive environments where developers build robotic intelligence and are rewarded based on performance.
 
The broader Bittensor ecosystem has also expanded into compute marketplaces, distributed inference systems, bandwidth infrastructure, and AI coordination layers that could eventually support robotics workloads. Several subnets now focus on decentralized compute, confidential inference, data transfer, and model training, critical components for future robotic systems.
 
In other words, the pieces are starting to appear.
 
Not a decentralized robot network yet.
 
But the infrastructure that could support one.
 
Beyond Bittensor: The Rise of Physical AI Networks
 
Bittensor isn't alone.
 
Across the industry, researchers and builders are experimenting with decentralized approaches to physical AI.
 
New research published in 2026 introduced the concept of DAO-enabled decentralized physical AI, or DePAI. The idea combines robotics, decentralized infrastructure, AI models, governance systems, and human oversight into a single framework. Instead of centralized control, robots and physical infrastructure could be coordinated through transparent rules and distributed ownership models.
 
At the same time, developers are exploring decentralized operating systems for robots that allow machines to communicate directly with each other and with distributed compute resources. These architectures are designed to make robotic systems more resilient and less dependent on a single cloud provider.
 
The goal is not simply decentralization for its own sake.
 
The goal is resilience.
 
If one server fails, the system continues.
 
If one company disappears, the network survives.
 
If one participant leaves, innovation continues.
 
But Here's the Reality
 
Decentralized AI faces the same challenge every decentralized technology faces.
 
Big Tech has resources. A lot of resources.
 
Training advanced robotics models requires enormous compute budgets, sophisticated simulation environments, access to specialized hardware, and vast amounts of real-world data.
 
That's why many robotics startups still partner with major cloud providers and AI companies. It's often the fastest path to deployment.
 
And there are legitimate concerns about whether decentralized networks can maintain quality, reliability, and security at the scale required for industrial robotics. Even researchers studying decentralized AI systems have highlighted risks around concentration, incentives, governance, and network security.
 
The challenge isn't just decentralizing intelligence.
 
It's decentralizing intelligence while maintaining performance.
 
That's much harder.
 
The Most Likely Outcome
 
The future probably won't be fully centralized. And it probably won't be fully decentralized either. Instead, we're likely heading toward a hybrid model.
 
Large technology companies will continue providing chips, cloud infrastructure, simulation platforms, and foundational research.
 
At the same time, decentralized AI networks will emerge as alternative coordination layers where intelligence, data, and economic value can be shared more openly.
 
The companies building robots may use NVIDIA hardware.
 
Train on Azure.
 
Run foundation models from OpenAI.
 
But they may also participate in decentralized data networks, decentralized compute markets, and decentralized intelligence protocols.
 
The future of robotics could end up looking less like a monopoly and more like an ecosystem.
 
The Bigger Question
 
The real question isn't whether decentralized AI can eliminate Big Tech.
 
It can't.
 
At least not anytime soon.
 
The real question is whether decentralized AI can prevent a future where a handful of companies control every robot, every model, every dataset, and every decision made by the machines operating around us.
 
As robots become workers, assistants, delivery drivers, factory operators, and even economic agents, that question becomes increasingly important.
 
Because the battle for the future of robotics is no longer about hardware.
 
It's about who owns the intelligence.
 
And that battle is just getting started.


🙏To support my work, Helping to keep the signal high and the noise low:

👉 Cashapp: $thedinarian

👉 Buy me a coffee: https://buymeacoffee.com/thedinarian

👉 PayPal: Scan the QR code below 📲 or Click Here

👇 Crypto Donations 👇

XRP: r9pid4yrQgs6XSFWhMZ8NkxW3gkydWNyQX
XLM: GDMJF2OCHN3NNNX4T4F6POPBTXK23GTNSNQWUMIVKESTHMQM7XDYAIZT
XDC: xdcc2C02203C4f91375889d7AfADB09E207Edf809A6

Read full Article
See More
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals